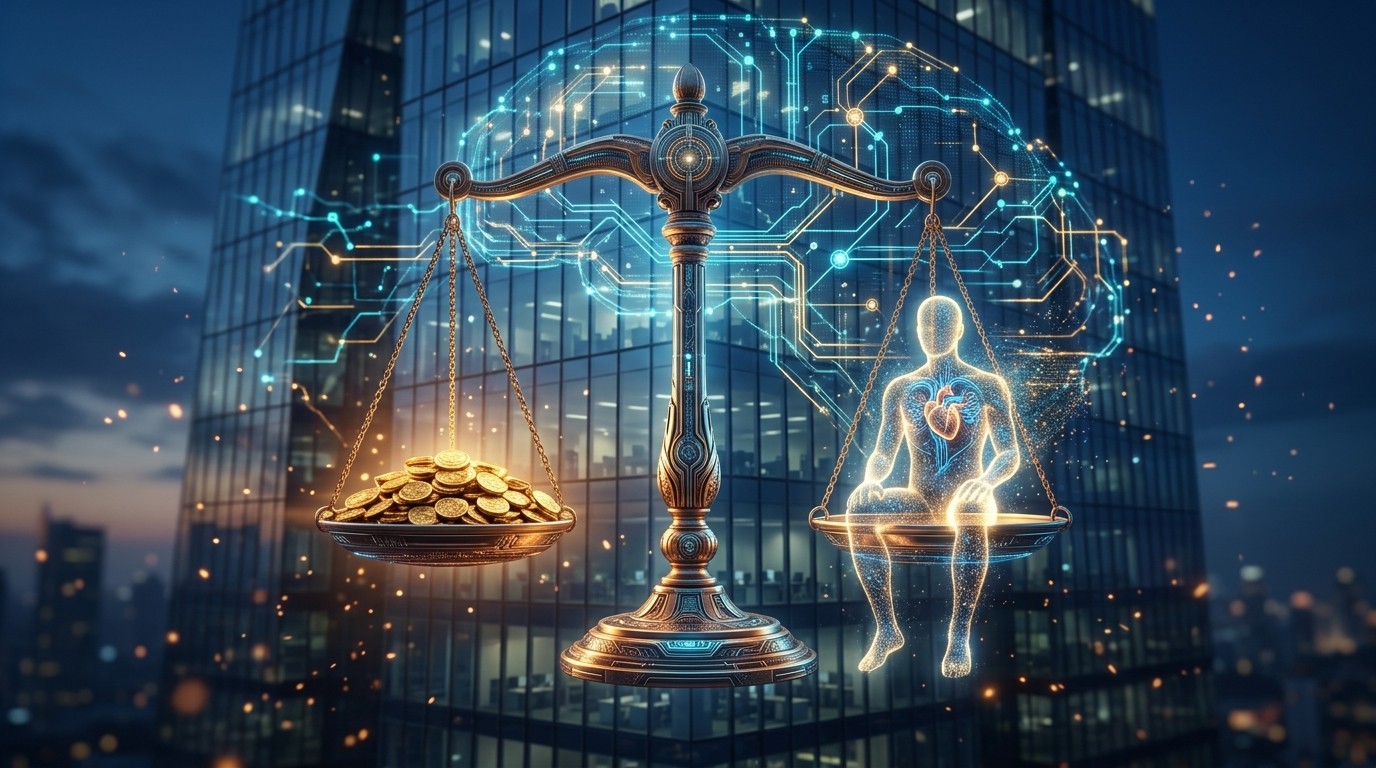

What happens when a company racing toward a trillion-dollar valuation tells the market it will sometimes put public good ahead of pure profit? That is the quiet puzzle sitting at the center of Anthropic’s planned public debut. Most investors are used to clear lines. A corporation exists to maximize returns for shareholders. Everything else ranks second. Anthropic is deliberately blurring those lines, and the decision could reshape how the market prices the next generation of artificial intelligence companies.
Understanding The Unusual Corporate Choice
Anthropic intends to go public as a public benefit corporation. That legal form is still uncommon among large technology firms seeking broad public ownership. In practical terms the board must weigh three obligations at once: the financial interests of stockholders, the well-being of people affected by the company’s actions, and a specific public purpose written into the corporate charter. The stated purpose is the responsible development of advanced artificial intelligence for the long-term benefit of humanity.
I have watched similar dual-mandate structures before. They sound elegant on paper. In the day-to-day grind of quarterly earnings and competitive pressure they create friction. Directors receive legal cover to make decisions that reduce short-term profit if those decisions advance the declared public benefit. Shareholders, especially those focused on rapid growth, may find that cover frustrating when results lag expectations.
How The Balance Requirement Actually Works
The word that keeps appearing in the legal language is “balance.” Directors must balance pecuniary interests against the public mission. The trouble is that no clear formula exists for that balance. One attorney who has spent decades studying these statutes put it bluntly: if you ask what balance really means, the honest answer is good luck. There is no objective test that tells a court when the public purpose should outweigh profit or the reverse.
That ambiguity cuts both ways. It gives management room to maneuver when safety concerns or ethical considerations arise. It also makes it harder for shareholders to succeed in any later claim that the board ignored their financial interests. Proving that directors simply mismanaged money is already difficult in ordinary corporations. Adding the public-benefit defense makes the path steeper still.
The obligation of directors is to balance achievement of purpose with achievement of profit, and if you ask me what that means – to balance – I would say, good luck.
In my experience, markets dislike open-ended discretion of this kind. Investors prefer predictability. When a company can legitimately choose a slower growth path because of a safety or societal concern, the usual valuation models become less reliable. Discount rates rise. Multiples compress. The market begins to price in optionality that management may exercise against pure shareholder return.
Control Mechanisms Already Built In
Beyond the public benefit form itself, Anthropic has layered additional governance features that further limit traditional shareholder power. A long-term benefit trust oversees certain business practices. A public benefit fund holds a meaningful block of special shares representing roughly five percent of fully diluted equity. Seven co-founders, through a single special share, control just over half of the total voting power on matters that come to a shareholder vote. The company has stated that those individuals are uniquely positioned to serve as stewards of the mission.
This arrangement is not unique in technology, yet the combination with the public benefit status creates a denser web of constraints. An independent trust helps elect a majority of directors. Founders keep voting control. The board must still weigh the public purpose. Ordinary public shareholders therefore sit several layers removed from operational influence. That distance can be comforting if one trusts the mission. It becomes a concern if results disappoint or if capital needs force repeated trips to the market.
Capital raising itself introduces another tension. Companies that continue to need large amounts of external funding usually must stay attentive to investor preferences. Dual-class or multi-class structures already command higher costs of capital because they dilute ordinary voting rights. Layering a public benefit obligation on top of those structures adds still more uncertainty about how future investment decisions will play out. Investors typically demand compensation for that uncertainty in the form of lower entry prices or higher expected returns.
Safety Choices Versus Revenue Growth
One concrete arena where the dual mandate will be tested is model release policy. Anthropic has already restricted access to certain systems it judges too capable or too risky for wide public deployment. That practice may continue even when broader release would accelerate revenue and market share. In ordinary corporate logic such restraint looks costly. Under the public benefit charter it can be framed as fulfillment of the core purpose.
I find this particular trade-off the most interesting for valuation purposes. Markets currently assign high multiples to companies that demonstrate rapid user growth and monetization. If Anthropic deliberately slows that growth to manage risk, the gap between potential and realized performance could widen. Analysts will need to decide whether the safety posture creates durable brand value that eventually supports higher pricing power, or whether it simply leaves market share on the table for less cautious competitors.
The same tension appears in product design choices. A commitment never to insert advertising into core conversational products sounds admirable from a user-trust perspective. It also removes a revenue stream that many other platforms treat as essential. Investors will watch closely to see whether alternative monetization paths can fully replace the forgone income without compromising the stated mission.
What Wall Street Analysts Are Already Flagging
Several research desks have noted that the public benefit status appears early and prominently in the registration materials. That placement is deliberate. Management wants the market to understand the constraints from day one rather than discover them later. One technology analyst observed that the company essentially leads with the idea that the stock should not trade above the underlying value of the enterprise, then immediately lists practices that are not purely profit-maximizing. The message is clear: this will not be a conventional growth story.
Another noted that governance limits shareholder influence in three distinct ways. The board must weigh mission alongside returns. An independent trust elects a majority of directors. Co-founders hold absolute voting majority. Taken together those features reduce the ordinary levers available to public investors who might otherwise push for faster commercialization or cost discipline.
Still, the structure is not permanent in every respect. Companies have changed or abandoned public benefit status in the past when circumstances demanded. The industrial organization of the artificial intelligence sector remains fluid. Large-scale combinations, new forms of public-private partnership, and evolving regulatory expectations could all prompt adjustments. Investors therefore need to treat the current framework as the starting point rather than a fixed endpoint.
Valuation Implications In A High-Multiple Sector
The company is aiming for a valuation that would place it among the most highly valued technology listings in recent memory. At those levels any structural uncertainty carries heavier weight. Markets already struggle to assign precise numbers to frontier artificial intelligence capabilities. Adding governance that prioritizes non-financial objectives increases the range of possible outcomes. Some investors will see that range as attractive optionality. Others will demand a larger discount.
Consider the capital intensity of the field. Training and deploying leading systems requires continuous heavy investment. If the dual mandate causes the company to forgo certain commercial opportunities or to invest more heavily in safety research than pure profit logic would dictate, free cash flow trajectories change. Discounted cash flow models become more sensitive to assumptions about when and how the public purpose will constrain spending or revenue.
I have found that in similar situations the market often applies a governance discount that persists until management demonstrates consistent delivery under the dual constraints. Early trading may therefore exhibit higher volatility than the underlying technology alone would justify. Patient capital with a long horizon and alignment with the mission may find the discount attractive. Shorter-term oriented funds may stay on the sidelines or demand clearer evidence that growth and purpose can advance together.
Historical Parallels And Important Differences
Other companies have operated under public benefit or similar frameworks. Some consumer brands have used the form to reinforce identity around sustainability or social impact. A few have later dropped the designation during restructuring. The artificial intelligence context differs in scale and speed. Decisions about model capability and release can affect not only revenue but also broader societal risk. The stakes attached to the public purpose are higher, and the competitive pressure is more intense.
One useful comparison is the informal cultural commitment some earlier technology companies made to avoid certain harms. Those commitments lived mainly in culture and codes of conduct rather than in binding corporate law. Anthropic has chosen the stronger path of embedding the purpose in the legal structure itself. That choice raises the cost of later reversal and signals genuine commitment. It also locks in the balancing obligation for as long as the structure remains.
Perhaps the most interesting aspect is how this experiment will influence other frontier laboratories. If the public market accepts the structure at a high valuation, peers may feel freer to adopt similar frameworks. If the market applies a persistent discount, the experiment may remain isolated. Either outcome will shape the governance norms of the entire sector for years.
Practical Considerations For Prospective Shareholders
Anyone evaluating an investment needs to ask several concrete questions. First, how much weight does personal alignment with the long-term benefit mission carry relative to pure financial return? Second, how comfortable is the investor with limited influence over board composition and major strategic decisions? Third, what discount rate feels appropriate given the open-ended nature of the balancing obligation?
- Assess personal tolerance for mission-driven decisions that may slow near-term growth
- Examine the multi-class share structure and resulting voting power distribution
- Model scenarios in which safety restrictions materially reduce addressable market
- Consider the likelihood of future capital raises under the current governance constraints
- Evaluate potential impact on merger and acquisition flexibility
These questions do not have universal answers. They depend on time horizon, risk appetite, and belief in the durability of the company’s technological edge. What remains clear is that the public benefit form introduces variables rarely present in standard technology listings.
The Broader Market Context
The artificial intelligence sector continues to attract enormous capital because the underlying capability improvements remain rapid. At the same time, questions about safety, concentration of power, and long-term societal impact have moved from academic discussion into mainstream policy debate. Anthropic has positioned itself as the laboratory most willing to internalize those concerns into its legal DNA. The public offering will test whether that positioning commands a premium, a discount, or simply a different investor base.
Regulatory attention is also intensifying. Officials have begun exploring audit mechanisms and development standards. A company already structured around public benefit may find itself better aligned with emerging expectations than pure profit maximizers. That alignment could reduce certain regulatory risks even as it increases others related to transparency and accountability.
In my view the structure is neither inherently superior nor inferior. It is different. Difference creates both opportunity and friction. The market will eventually settle on a price that reflects the net effect of those two forces. Until that discovery process runs its course, volatility around any major decision that invokes the public purpose is likely to remain elevated.
Possible Paths Forward After Listing
Once shares begin trading, several scenarios become plausible. Management could demonstrate that purpose and profit reinforce each other, gradually closing any governance discount. Alternatively, competitive pressure could force more commercial aggressiveness, testing the limits of the balancing obligation. A third path involves external events—regulatory shifts, major capability jumps, or industry consolidation—that make the current structure either more valuable or more constraining.
Investors should also watch for any formal proposals to amend or terminate the public benefit status. Precedent exists for such changes. The process is rarely simple, yet it remains available. The existence of that option itself affects the long-term risk profile. A structure that can be altered is less binding than one that cannot, yet the political and reputational cost of alteration may still be high.
Capital allocation decisions will offer ongoing signals. How much incremental spending goes into safety research versus product commercialization? How are release decisions justified when commercial opportunity is obvious? The answers to those questions will reveal how the board actually exercises the discretion the law grants.
Longer-Term Industry Implications
If the offering succeeds at a high valuation despite the structural constraints, other laboratories may adopt similar frameworks. That outcome would gradually normalize dual-mandate governance across the frontier of artificial intelligence. If the market instead insists on a material discount, pure profit-oriented structures may remain dominant. Either result will influence how capital flows and how risk is managed in the years ahead.
The experiment also matters beyond pure finance. Public markets have long served as a mechanism for aligning private enterprise with broader ownership. Embedding an explicit public purpose into that mechanism tests whether markets can price and support more complex objective functions. Success would expand the toolkit available to founders who care about outcomes beyond quarterly results. Failure would reinforce the traditional hierarchy of pure shareholder primacy.
I keep returning to the practical reality that directors must still make decisions under uncertainty. The public benefit form does not eliminate hard trade-offs. It merely changes the legal vocabulary in which those trade-offs are discussed and defended. Investors who understand that distinction will be better prepared for the inevitable moments when purpose and profit pull in different directions.
Key Takeaways For The Investment Decision
The decision to invest ultimately rests on a personal assessment of whether the technological opportunity outweighs the governance complexity. The public benefit structure adds real constraints on board discretion and shareholder influence. It also provides a coherent framework for decisions that many observers already expect leading artificial intelligence companies to make. The market price will eventually reflect the net present value of that package of rights and obligations.
Prospective shareholders should examine the multi-class voting arrangements, the role of the long-term benefit trust, and the explicit public purpose language with the same care they apply to revenue projections and competitive positioning. Those governance features are not secondary details. They sit at the core of how value will be created and distributed over time.
In the end the listing will serve as a live experiment in whether public markets can support a company that openly refuses to treat profit as the sole objective. The outcome will matter far beyond any single stock price. It will help define the institutional architecture available to the next generation of transformative technology firms. That is why the structural questions deserve careful attention alongside the more familiar metrics of growth and margin.
The coming months will reveal how the market digests these unusual features. Early trading patterns, analyst commentary, and management communication around the first few major decisions will all provide useful data. Until then the prudent approach is to treat the public benefit form as a first-order variable rather than a footnote. Investors who do so will enter the process with clearer eyes and more realistic expectations about both the upside and the constraints that come with it.
Artificial intelligence continues to advance at a pace that challenges traditional corporate forms. Anthropic’s choice to list under a public benefit structure is one response to that challenge. Whether the response proves durable and value-accretive remains an open question. The answer will emerge not from theory but from the concrete decisions the board makes when purpose and profit next diverge. Watching those moments with attention will tell investors more than any prospectus language ever could.
The structure forces a continuous conversation about what long-term benefit actually requires in a fast-moving competitive field. That conversation itself has value. It keeps safety and societal impact on the formal agenda rather than in the realm of optional culture. For investors who believe those considerations will ultimately determine which companies thrive, the framework offers a degree of alignment that pure profit mandates cannot match. For those who prioritize maximum near-term financial flexibility, the same framework represents an ongoing tax on optionality. Both perspectives are legitimate. The market will sort them according to the prices participants are willing to pay.
Ultimately the public debut will test more than demand for a particular set of shares. It will test the market’s capacity to value a company that has deliberately chosen a more complex objective function. The results of that test will influence governance design across the sector for a long time to come. That broader significance is what makes the structural details worth understanding in full before any capital is committed.