
What if a major policy shift designed to boost domestic energy output and ease costs ended up moving the needle on oil prices by less than the cost of a cup of coffee? That is the picture emerging from the latest economic modeling around proposed changes to methane rules. I have been following energy policy twists for a while now, and this one stands out because the numbers feel almost surprisingly modest. The projected drop in U.S. crude prices sits at roughly 11 cents a barrel in 2027. That works out to about 0.14 percent. Production might rise by a slim 0.09 percent in the same year. Meanwhile the longer-term emissions picture looks noticeably different.
Understanding The Limited Price And Production Effects
The proposal aims to lighten certain methane requirements for oil and gas operators. Officials have framed it as a way to cut regulatory burdens and support more American energy production. The idea sounds straightforward: lower compliance costs should encourage more output and, eventually, softer prices for consumers. Yet the agency’s own projections tell a quieter story. An 11-cent reduction on a barrel of crude does not reshape household budgets or industrial fuel costs in any dramatic fashion. In my view that modest figure already signals how complex the real-world response from producers is likely to be.
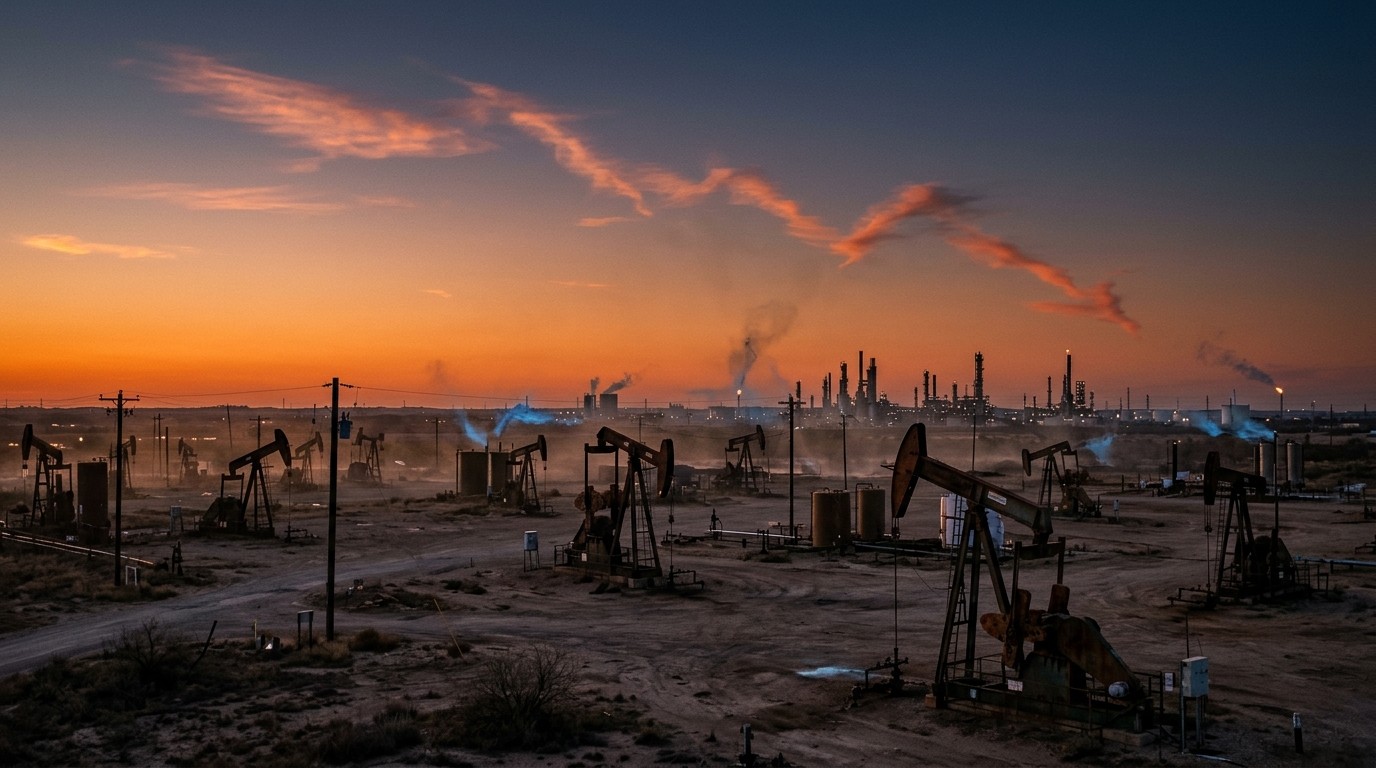
Domestic oil production is expected to increase by just 0.09 percent under the changes. Put another way, that is roughly one extra barrel for every thousand that would have been produced anyway. Many operators already plan their activity around broader market signals rather than a single set of rules. When crude prices sit comfortably above levels that keep most wells profitable, the extra regulatory breathing room helps at the margins but does not suddenly unlock large new volumes.
Why Producers May Hold Back On Rapid Expansion
Uncertainty plays a bigger role here than many headlines suggest. Policy durability across different administrations remains an open question. Operators tend to think in multi-year investment cycles. If they suspect rules could shift again after the next election cycle, they often prefer to wait and see rather than commit capital aggressively. I have noticed this pattern repeatedly in energy markets: the promise of lighter regulation creates optimism, yet actual drilling schedules respond more slowly.
Another factor involves the type of wells most affected. Marginal wells make up a large share of active sites across the United States yet contribute a relatively small slice of total output. These lower-volume wells can stay online longer when compliance costs fall. That slows natural production declines rather than triggering a surge in new drilling. The net result is a gentle lift in supply instead of a flood.
When owners and operators can produce, America benefits with lower prices.
That statement captures the intended spirit of the proposal. Still, the modeled price effect stays small. Analysts who track shale activity note that with oil prices expected to remain elevated, many wells already clear their economic hurdles without needing extra regulatory relief. The changes therefore touch only a limited portion of overall market activity.
The Role Of Marginal Wells And Existing Infrastructure
Marginal wells deserve a closer look because they sit at the heart of the limited supply response. These sites often produce modest daily volumes. Their economics can tip from viable to uneconomic with relatively small cost increases. Easing methane rules can keep some of them running longer. Over time that helps stabilize production levels. Yet because their individual contribution stays small, the aggregate impact on national output remains modest.
Existing infrastructure also matters. Operators do not build new pipelines or processing plants overnight. Even if more associated gas becomes available, the ability to capture and sell it depends on nearby facilities. In some basins that capacity already runs tight. The proposal allows greater flexibility around flaring under certain conditions, which can reduce the pressure to invest in capture equipment right away. That flexibility saves money in the short run but also means less gas reaches the market as a saleable product.
Projected Emissions And Economic Trade-Offs
One clear outcome from the modeling involves methane emissions. The proposal could lead to roughly 60 million additional short tons of methane released between 2027 and 2050. That figure stands out because methane is a potent greenhouse gas. The same analysis estimates overall economic savings near 45 billion dollars over that period. Most of those savings, about 42 billion dollars, come from lower compliance costs. At the same time operators are expected to capture less gas for sale or onsite use, creating roughly 4.2 billion dollars in lost revenue. That revenue loss is already folded into the compliance savings number.
These numbers invite a practical question. How should decision makers weigh modest near-term price relief and production support against a measurable rise in emissions? Different stakeholders will answer that question differently. Energy producers focus on operational flexibility and cost control. Environmental advocates highlight the cumulative climate impact. Consumers mostly notice the price at the pump or the heating bill. In this case the modeled price change stays so small that many households would struggle to detect it.
Key Elements Inside The Proposed Changes
The proposal explores lighter requirements based on a well site’s production levels or the distinction between conventional and unconventional extraction methods. It would also eliminate the Super Emitter Program that currently relies on approved third-party monitors to flag large methane releases. Separately, operators would gain more room to manage associated gas through flaring that achieves at least 95 percent destruction efficiency.
These adjustments aim to reduce administrative and technical burdens. Smaller operators in particular have argued that certain monitoring and repair requirements create outsized costs relative to their production volumes. Whether the final rule preserves that relief will depend on the public comment process and subsequent agency review. Nothing is locked in yet. Rulemaking still has several steps ahead.
- Production-based or method-based lighter methane requirements
- Removal of the third-party Super Emitter monitoring program
- Expanded flexibility for high-efficiency flaring of associated gas
- Projected compliance cost reductions measured in tens of billions over decades
- Modest near-term effects on crude prices and domestic output
Each of those points carries practical consequences. Removing third-party monitoring shifts detection responsibility more fully onto operators and regulators. Allowing more flaring can simplify operations at remote sites yet reduces the volume of gas that might otherwise enter the market. The overall package prioritizes cost relief and operational simplicity over maximizing captured methane volumes.
Market Context And Broader Energy Policy Moves
This methane proposal arrives alongside other efforts aimed at easing fuel price pressures. Separate discussions have touched on sanctions related to certain diesel flows. The combination suggests a broader interest in expanding available supply through multiple channels. Still, global oil markets respond to many forces at once: geopolitical events, inventory levels, demand trends in major economies, and decisions by large producers elsewhere. A domestic regulatory change of this scale rarely overrides those larger drivers.
I find it useful to keep perspective. An 11-cent price movement in 2027 sits well inside the normal daily volatility of crude markets. Traders routinely see swings of several dollars. Households notice changes measured in tens of cents per gallon at the pump far more than fractional shifts in the underlying barrel price. The production increase of less than one-tenth of one percent likewise remains small against total U.S. output.
How Operators Are Likely To Respond In Practice
Most producers will evaluate the final rule against their specific asset base. Companies with large portfolios of low-volume wells stand to gain more operational breathing room. Those already running modern, high-volume pads with existing capture systems may see smaller relative benefits. Capital allocation decisions will still hinge primarily on expected oil and gas prices, drilling costs, and available pipeline capacity.
Some operators may choose to keep certain wells online longer rather than accelerating new drilling. That pattern would align with the modeling that points to slower declines rather than sharp production growth. In basins where associated gas has limited offtake options, the flaring flexibility could prove especially practical. Elsewhere, companies that have already invested in methane detection technology may simply continue current practices because the systems deliver operational insights beyond regulatory compliance.
Perhaps the most interesting aspect is how investment decisions will balance short-term cost savings against longer-term policy risk. Energy projects often require years to plan and execute. If executives believe future administrations could reinstate stricter requirements, they may treat the current proposal as temporary relief rather than a permanent change in operating conditions. That mindset naturally limits the upside to near-term production rates.
Looking At The Numbers Side By Side
A simple comparison helps clarify the scale. On the price side the projected 2027 impact is 11 cents per barrel. On the production side the lift is 0.09 percent. On the emissions side the cumulative addition reaches 60 million short tons of methane across more than two decades. On the economic side the estimated savings approach 45 billion dollars, driven mostly by lower compliance outlays. These figures do not cancel one another out; they simply describe different dimensions of the same policy choice.
| Metric | Projected Impact | Time Frame |
| U.S. Crude Price | Down 11 cents per barrel (0.14%) | 2027 |
| Domestic Oil Production | Up 0.09% | 2027 |
| Additional Methane Emissions | 60 million short tons | 2027–2050 |
| Estimated Economic Savings | About 45 billion dollars | 2027–2050 |
| Compliance Cost Reduction | Roughly 42 billion dollars | 2027–2050 |
Seeing the data together underscores the modest near-term market effects alongside more noticeable longer-term environmental and cost implications. Decision makers and market participants can now weigh those trade-offs with clearer numbers in hand.
What Comes Next In The Rulemaking Process
The proposal still faces a public comment period and further internal review before any final rule can take effect. Stakeholders from industry, environmental groups, and state regulators will likely submit detailed feedback. That input can shape the ultimate language around production thresholds, monitoring expectations, and flaring standards. Nothing about the current projections is guaranteed until the process concludes.
In the meantime operators continue their ordinary planning cycles. Many already factor potential regulatory shifts into their internal forecasts. The difference this time is that the agency itself has published specific quantitative estimates for price, production, emissions, and cost impacts. Those estimates provide a useful baseline for everyone watching the sector.
I keep coming back to the core observation that the modeled price relief stays small. Policy makers can still decide that the compliance savings and operational flexibility justify moving forward. Markets, however, appear unlikely to reprice crude in any meaningful way solely on the basis of these changes. Broader supply and demand forces will continue to set the tone.
Practical Implications For Different Market Participants
For large integrated producers the proposal may represent incremental cost relief rather than a strategic game changer. Their capital budgets respond more to commodity price outlooks and global project economics. Independent operators focused on mature fields or lower-volume wells could experience more tangible benefits if the final rule reduces the expense of keeping those assets online.
Service companies that supply monitoring equipment or emissions control technology may see softer demand for certain products if requirements ease. At the same time, the industry still faces growing interest from investors and customers in overall methane performance. Some operators will continue voluntary programs even if regulatory pressure lightens, simply because those programs support broader business goals.
Consumers and industrial users of oil and gas products are unlikely to notice an 11-cent shift in the crude price. Retail gasoline and diesel prices move with refining margins, taxes, distribution costs, and local competition far more than with fractional changes in the feedstock. The real story for end users remains overall market balance and geopolitical developments.
Balancing Flexibility And Longer-Term Considerations
Every regulatory adjustment involves trade-offs. Greater operational flexibility and lower near-term costs sit on one side. Higher cumulative methane emissions and reduced gas capture sit on the other. The modeling quantifies both. Whether the balance feels appropriate depends on priorities. Some will emphasize energy security and affordability. Others will emphasize the climate implications of additional methane over the coming decades.
What feels clear is that the price and production effects remain limited according to the available projections. The policy may help certain well operators manage costs and keep assets producing longer. It is less likely to deliver the kind of supply surge or price drop that would reshape broader energy markets. That distinction matters for anyone trying to separate realistic expectations from more optimistic talking points.
As the rulemaking process continues, updated analysis could refine these numbers. Public comments often surface practical implementation details that alter cost or emissions estimates. Until then the current figures offer the best available guide. An 11-cent price impact, a fractional production increase, tens of billions in compliance savings, and tens of millions of additional short tons of methane form the core of the story.
Energy policy rarely delivers simple outcomes. This proposal is no exception. It illustrates how even substantial regulatory changes can produce only modest market price effects when the underlying industry already operates near economic thresholds set by global commodity prices. The coming months of review will determine the final shape of the rules and, with them, the precise mix of costs, benefits, and emissions that operators and the broader public ultimately experience.
Looking ahead, market participants will watch both the final regulatory text and the actual response of producers on the ground. Investment patterns, well shut-in rates, and flaring volumes will reveal more than any single projection. For now the data points to limited near-term relief on oil prices and a more noticeable long-term shift in methane emissions and compliance burdens. That combination defines the practical outlook.
The discussion around domestic energy production and regulatory design will continue. Proposals that aim to support output while managing environmental performance always invite close scrutiny of the numbers. In this case the numbers themselves suggest a measured rather than transformative impact on crude markets. Operators, investors, and policymakers can all plan accordingly.
One final observation stays with me. Policy announcements often generate strong immediate reactions. The detailed modeling that follows can quiet some of that noise by showing the scale of expected effects. Here the scale on prices and production looks small. The scale on cumulative emissions and cost savings looks larger. Holding both realities in view offers the most useful path forward as the process unfolds.