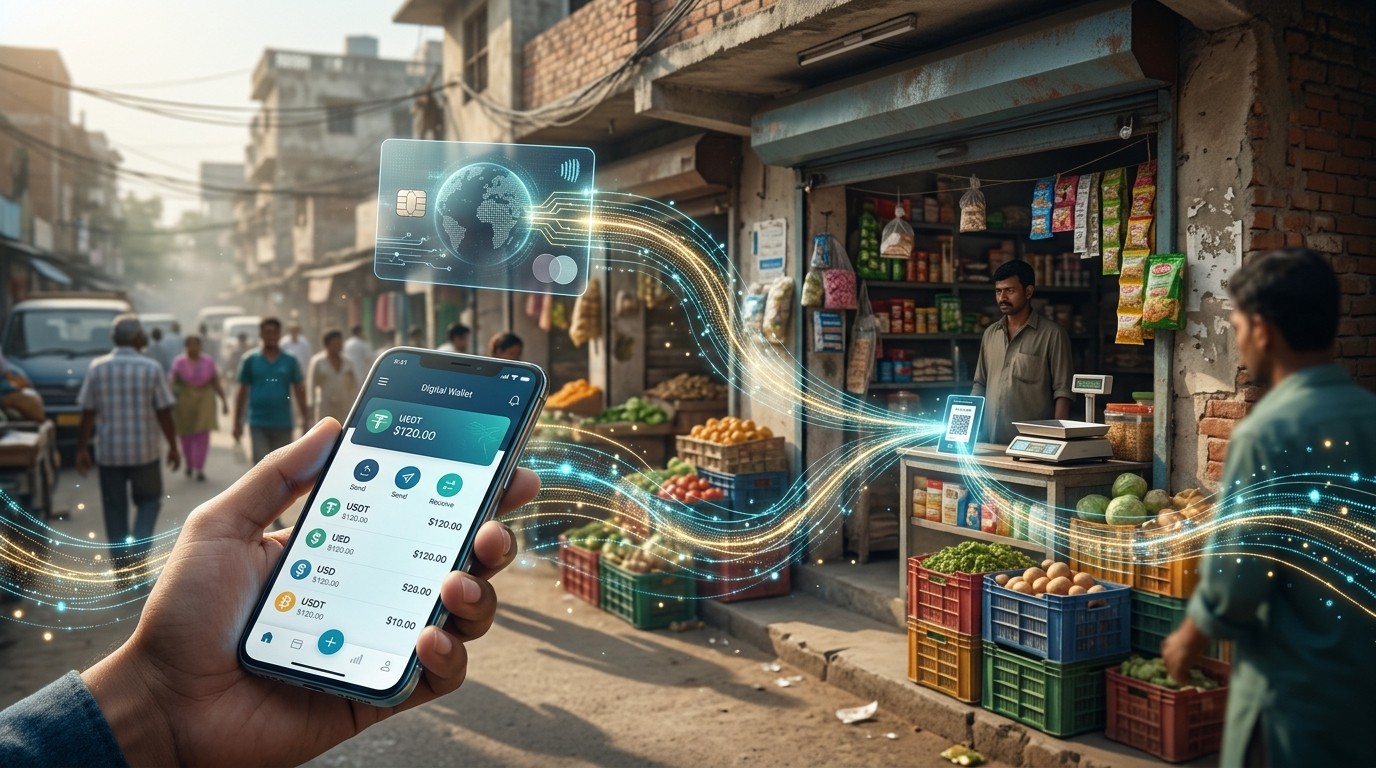

I’ve been watching digital wallets try to bridge the gap between crypto balances and real-world spending for years, and most attempts still feel clunky. That changed a bit when news broke about Airtm linking up with Mastercard’s BVNK unit. Suddenly the idea of paying a local shopkeeper straight from a stablecoin wallet without extra steps starts to look practical rather than experimental.
How The Airtm And BVNK Deal Changes Everyday Payments
The partnership centers on letting people in emerging markets spend digital dollars held in their Airtm wallets at retailers that already work with BVNK. No need to cash out first or jump through multiple conversion layers. The whole flow sits on the Stellar network, chosen for its low fees and speed when moving value across borders.
Airtm Connect is the new bridge that makes this possible. Think of it as a doorway that lets outside financial services plug directly into Airtm’s existing user base. Once the connection is live, a customer can open the wallet, select a supported merchant, and complete the purchase without leaving the app. In my view that simple continuity matters more than any technical white paper.
Why Emerging Markets Stand To Gain The Most
Many users in these regions already rely on digital dollars for everyday life. They receive remittances, hold value against local currency swings, and try to access goods that local banking systems make difficult. Traditional rails often leave them stuck between a crypto balance and the actual store shelf.
This deal aims to shrink that friction. By giving Airtm access to Mastercard’s Global Money Platform through BVNK, the company can offer more ways to fund wallets, accept incoming transfers, and push payments out to merchants. The platform itself handles traditional currency accounts, stablecoin movements, and cross-border transfers under one roof. That combination feels practical rather than flashy.
We believe payments should move natively on-chain – it’s simply a better way to move money.
– Rubén Galindo Steckel, CEO of Airtm
Steckel has spent a decade building tools that connect underserved users to the broader dollar economy. His point about native on-chain movement is fair. Once money sits on a chain that already supports fast, cheap transfers, forcing it back into slower systems just to spend it feels backwards. The partnership tries to keep the money where it already lives while still reaching everyday commerce.
What Airtm Connect Actually Delivers
Airtm Connect is not just another marketing label. It functions as the technical and commercial layer that lets digital-asset companies attach their services to Airtm’s network of users. In practice that means BVNK becomes one more infrastructure option alongside the providers Airtm already uses. Choice remains central to the strategy.
Customers will eventually be able to fund wallets through additional routes, receive payments more flexibly, and spend balances at participating retailers. The first wave is scheduled for the fourth quarter of 2026. Exact countries and merchant lists have not been released yet, which leaves some healthy uncertainty about the early scope.
I’ve found that announcements like this often sound broader than the initial rollout. Still, the underlying architecture looks solid. Stellar already supports transfers designed for low-cost movement, and BVNK added the network to its platform earlier. Businesses can now reach more than 130 markets through that single connection without building separate blockchain rails.
The Role Of Mastercard’s Global Money Platform
Mastercard finished its acquisition of BVNK in August under a deal valued at up to 1.8 billion dollars. The purchase brought stablecoin settlement tools, international payout capabilities, and treasury functions into Mastercard’s broader payments business. The Global Money Platform is the public face of that integration.
Through a single API, fintechs and businesses can manage multicurrency accounts, convert currencies, issue payment cards, and arrange local bank transfers. Mastercard expects local bank payouts via Mastercard Move to cover more than 40 currencies across over 200 countries and territories by 2027. For Airtm the platform supplies extra banking and payment infrastructure while the company keeps its direct relationship with users.
Other early participants preparing to use the platform include several well-known payment and fintech names. That shared environment suggests Airtm is not experimenting alone. Shared infrastructure often speeds up merchant acceptance because retailers already know the rails.
Why Stellar Fits The Use Case
BVNK added Stellar support in September. The network was already designed for low-cost, high-volume transfers, which matches the needs of remittances and merchant payments in markets where every fraction of a percent matters. Businesses can now access Stellar through BVNK’s existing API without rewriting their payment stack.
The announcement stayed quiet on which specific stablecoins will be spendable at launch. That detail will matter once the service reaches users. Still, the underlying network choice signals a preference for practicality over hype. Stellar has spent years focusing on exactly these kinds of real-world transfers rather than speculative trading features.
In my experience the chains that win everyday payment volume are the ones that stay boringly reliable. Speed and cost matter more than flashy marketing once a shopkeeper needs to settle a sale. Stellar’s profile matches that requirement reasonably well.
Broader Infrastructure Strategy At Airtm
Airtm already works with multiple infrastructure providers so it can serve customers across jurisdictions that differ in banking access, stablecoin rules, and liquidity. Adding BVNK expands the menu rather than replacing existing partners. Steckel has been clear that the company does not want to depend on any single provider or blockchain.
Our infrastructure strategy has always been about choice for Airtm and for our users.
– Rubén Galindo Steckel
That philosophy shows up in the practical details. Different markets often require different funding routes. Some regions favor certain local payment methods, others have tighter banking restrictions, and liquidity for particular stablecoins can vary. Having several options lets the company route around bottlenecks instead of forcing every user through the same pipe.
The partnership also strengthens Airtm’s ability to handle customer deposits and incoming transfers. When someone receives an international payment, the funds can land more smoothly into a wallet that already connects to spending rails. That closed loop is what many users have been waiting for.
Practical Benefits For Everyday Users
Imagine receiving a remote work payment or family remittance in digital dollars. Until now the next step often meant converting to local currency through an exchange or service that charged fees and introduced delays. With the new setup, the same balance can move straight to a participating retailer. The reduction in steps alone changes the experience.
Merchants gain access to a pool of customers who already hold spendable digital value. For smaller retailers in emerging markets, accepting those payments without building their own crypto infrastructure is attractive. BVNK’s existing merchant network supplies the acceptance side while Airtm supplies the user side.
- Direct wallet-to-merchant payments without intermediate cash-outs
- Additional funding routes for wallet top-ups across different countries
- Access to Mastercard’s broader multicurrency and transfer tools
- Lower-cost transfers through Stellar’s payment design
- Greater flexibility when local banking conditions change
None of these points is revolutionary on its own. Together they form a more complete loop for users who live partly in digital dollars and partly in local cash economies. That hybrid reality is common in many of the markets Airtm serves.
Timeline And Remaining Questions
Both companies plan to begin the rollout in the fourth quarter of 2026. That gives them several months to finalize technical integration, compliance checks, and merchant onboarding. Early markets and the first wave of retailers have not been named. The absence of those details is normal at this stage, yet it leaves room for speculation.
Will the service launch first in Latin American markets where Airtm already has strong presence? How quickly will mid-sized retailers join larger chains? Which stablecoins will appear in the initial spendable set? These questions will shape the practical value for users. Until answers arrive, the partnership remains a promising architecture rather than a finished product.
I’ve seen similar announcements generate excitement that later met slower adoption. Merchant education, local regulatory clarity, and reliable liquidity all take time. Still, the combination of an established wallet network, a major payments company, and a purpose-built blockchain creates better odds than most earlier experiments.
Looking At The Bigger Picture For Stablecoin Spending
Stablecoins have spent years proving they can move value efficiently. Spending them at the corner store or online retailer has lagged behind. Each new partnership that removes conversion steps pushes the industry closer to ordinary utility. The Airtm and BVNK arrangement is one more data point in that longer trend.
Mastercard’s decision to acquire BVNK and build the Global Money Platform shows traditional payments firms now treat stablecoins as infrastructure rather than novelty. When a company of that scale invests heavily, the surrounding ecosystem tends to follow. Airtm’s participation gives the platform a ready user base that already understands digital dollars.
Perhaps the most interesting aspect is how quietly practical the design feels. There is no claim that every transaction will suddenly become free or that cash will disappear. Instead the focus stays on reducing friction for people who already live between two financial systems. That restrained ambition may prove more durable than bolder promises.
What Users Should Watch Next
Anyone holding balances in Airtm wallets will want to track the Q4 2026 launch window. Early participating countries will reveal whether the service prioritizes remittance corridors or domestic commerce. Merchant density will determine whether the feature becomes a daily tool or an occasional convenience.
Fee structures also deserve attention once they are published. Low network costs on Stellar help, yet the total cost to the user depends on how the companies share revenue and handle conversions when needed. Transparency around those numbers will shape adoption speed.
Support for additional stablecoins beyond the initial set will expand usefulness. Many users already hold more than one dollar-linked token. Broader support reduces the need to swap assets just to spend them.
The partnership does not solve every friction point in emerging-market finance. Local regulations still vary, internet reliability is uneven, and cash remains essential in many daily interactions. Yet the direction is clear. Digital wallets are moving closer to the point of sale, and major payments infrastructure is meeting them halfway.
For users who have spent years converting digital dollars back into local currency just to buy groceries or pay a bill, the ability to spend directly from the wallet is meaningful progress. Whether the rollout meets its timeline and reaches enough merchants will decide how quickly that progress turns into routine habit. For now the architecture is in place, the partners are aligned, and the next few months will show how far the idea travels once real customers start tapping “pay.”
In the longer view this kind of integration may become ordinary. Wallets will connect to multiple payment networks the same way banking apps already connect to card schemes. When that happens, the distinction between holding a stablecoin and holding a traditional balance will matter less to the person standing at the checkout. The money simply moves, and the underlying rails stay invisible. That is the quiet goal behind announcements like this one, and it is worth watching closely as the pieces continue to lock into place.