
Have you ever wondered what really happens when a major bank gets caught letting billions in questionable money slip through its systems? It is the kind of story that makes you stop and think about how the financial world actually operates behind the polished exteriors and reassuring ads. I have followed these cases for years, and this latest development involving one of the nation’s largest banks feels particularly striking because the civil penalties, while enormous on paper, may not go far enough for some powerful voices in Washington.
The Call for Stronger Accountability After Massive Penalties
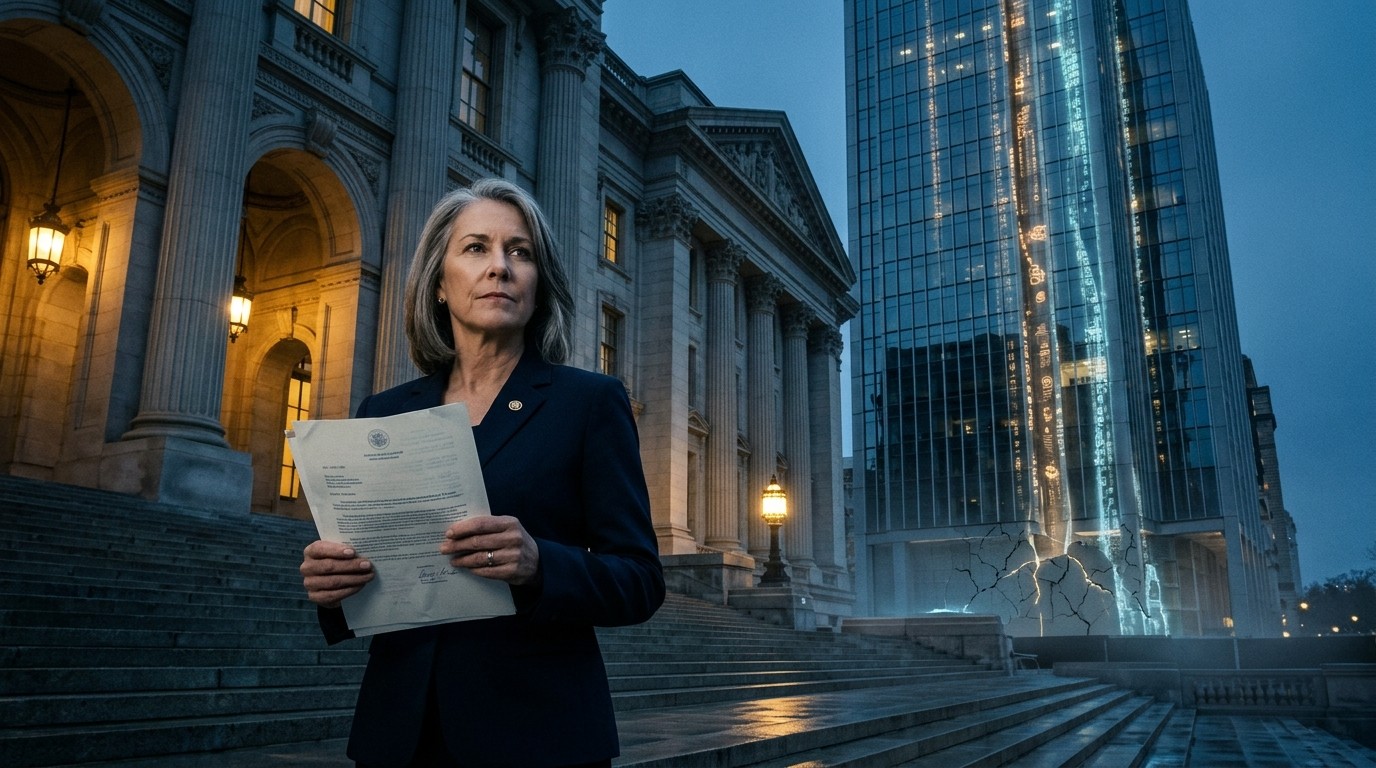
Just weeks after regulators handed down more than $1.2 billion in fines, a leading senator from Massachusetts is pressing the Justice Department to dig deeper. She wants a full criminal investigation into the bank and its top executives. In her view, the civil settlement represents little more than a cost of doing business rather than a true reckoning. The letter she sent sets a clear deadline: a response by mid-November on whether any criminal inquiry has already begun or will be launched.
This is not an ordinary compliance matter. The bank itself admitted it willfully violated core anti-money-laundering rules under the Bank Secrecy Act. That admission carries weight. Regulators found that the institution failed to maintain an effective program and did not properly report suspicious activity for an extended period. The numbers are hard to ignore. More than $5 billion in suspicious transactions went unreported in a timely way. Of that amount, over $1 billion touched areas of national security concern, including patterns linked to Chinese money-laundering networks and activity connected to the southwest border.
I find it telling that the bank reportedly leaned heavily on tips from law enforcement and other financial institutions instead of relying primarily on its own internal systems. At times, according to the findings, revenue considerations appeared to take priority over robust compliance. That kind of imbalance raises serious questions about culture and priorities at the highest levels.
What the Settlement Actually Revealed
The enforcement action ranks among the largest of its kind in recent history. One portion of the penalties came as a record fine from the Office of the Comptroller of the Currency. The overall package exceeded $1.2 billion. Yet no criminal charges accompanied the civil resolution. That absence sits at the center of the current controversy.
The bank had already been operating under a 2024 cease-and-desist order that required improvements in its anti-money-laundering controls. Regulators later concluded that progress on certain issues remained insufficient. In response to the latest penalties, the institution stated it had invested billions of dollars in compliance upgrades and believed it was well along in fixing the identified problems. Still, the senator argues that civil fines alone have become routine expenses for large financial firms rather than meaningful deterrents.
Civil fines have become the cost of doing business on Wall Street.
Federal law does allow for criminal penalties in cases of willful violations of the Bank Secrecy Act. That legal pathway is exactly what the senator is urging the Justice Department to explore. She has asked for a clear answer on whether the department has already examined the conduct and, if not, whether it intends to open an investigation.
Why the Scale of Unreported Activity Matters
When more than $5 billion in suspicious transactions escape timely reporting, the implications stretch far beyond one institution. The financial system depends on banks acting as the first line of defense against illicit finance. Failures at this scale can open doors for networks that move money tied to serious threats. The portion involving national-security priorities makes the shortcomings especially concerning.
In my experience watching these cases unfold, the most troubling pattern is when institutions discover problems primarily because outsiders point them out. A healthy compliance program should surface the majority of red flags on its own. Relying on external referrals suggests gaps in monitoring, data analysis, or the willingness to escalate issues internally. Those gaps do not appear overnight. They usually reflect deeper resource allocation decisions and cultural signals from leadership.
Perhaps the most interesting aspect is how regulators described the bank’s approach at certain points. Prioritizing revenues over compliance is a phrase that carries real weight in official findings. It points to a tension that many large organizations face, yet the consequences become public only after enforcement actions surface the details.
The Political Pressure and Timing
The letter arrives at a moment when public attention on financial accountability remains high. The senator, who serves as ranking member of the Senate banking committee, framed the civil penalties as inadequate. She wants the Justice Department to determine whether criminal charges against the bank or individual executives are warranted. The request includes a specific timeline for a response.
Neither the bank nor the Justice Department offered immediate public comment after the letter became known. That silence is typical in the early stages of such requests. Still, the public nature of the demand increases the pressure for a clear reply. Deadlines in these letters often serve as markers that keep the issue visible.
I have noticed that these moments tend to highlight a broader debate. Some observers believe civil penalties of this magnitude already deliver a strong message and force meaningful operational changes. Others insist that without the possibility of criminal consequences, the deterrent effect remains limited. The senator clearly belongs to the second group. She points to the willful nature of the violations as justification for exploring the criminal route.
How Compliance Shortcomings Develop Over Time
Large banks manage enormous volumes of transactions every day. Building systems that catch suspicious patterns without creating excessive false positives is genuinely difficult. Technology helps, yet human judgment and institutional culture still matter enormously. When systems lag or when staff feel pressure to clear transactions quickly, gaps can widen.
The earlier cease-and-desist order already signaled that regulators had identified deficiencies. The fact that further serious problems persisted suggests that remediation proved more challenging than expected. Investing billions in compliance is a significant step, yet results ultimately depend on how those resources are deployed and whether leadership consistently prioritizes the function.
- Failure to maintain an adequate anti-money-laundering program
- Delays in reporting more than $5 billion in suspicious activity
- Heavy reliance on external tips rather than internal detection
- Insufficient progress under a prior regulatory order
- Admitted willful violations of key statutes
Each of those points compounds the others. Together they paint a picture of systemic rather than isolated shortcomings. That is why the call for a criminal inquiry carries extra force. Civil settlements can require remediation plans and monetary payments. Criminal investigations open the door to different consequences, including potential individual accountability.
Broader Implications for the Financial Sector
Other institutions are watching closely. When one of the largest banks faces this level of scrutiny, compliance teams across the industry take note. Boards ask tougher questions about their own programs. Regulators may adjust their expectations for what constitutes adequate monitoring. The episode also feeds into ongoing conversations about whether current enforcement tools are calibrated correctly.
Some argue that the sheer size of the penalties already creates a powerful incentive to strengthen controls. Others counter that when fines remain a manageable percentage of overall revenue or profits, they function more like a business expense. The senator’s letter leans hard into the second perspective. She wants the Justice Department to consider the full range of available tools.
In practical terms, a criminal investigation would examine not only the institutional failures but also the knowledge and decisions of specific executives. That layer of personal risk changes the conversation inside corporate leadership suites. It can influence how aggressively compliance concerns are raised and how thoroughly they are addressed.
The Role of Willful Violations in Enforcement
The admission of willful violations is central. Willfulness carries a higher threshold than simple negligence. It suggests knowledge of the requirements and a conscious decision to fall short of them. That distinction matters under the relevant statutes, which provide both civil and criminal pathways for enforcement.
Regulators used that admission as part of the settlement foundation. The senator is now asking whether the same facts support a criminal review. The Justice Department will make its own independent assessment. Still, a high-profile request from a senior member of the banking committee adds visibility and urgency.
I have found that these cases often reveal how complex modern compliance really is. Transaction monitoring systems generate alerts. Analysts must review them. Escalation processes need to function without bottlenecks. Training has to stay current. Data quality can make or break detection capabilities. When any of those elements weakens, problems accumulate over time until they become visible through regulatory examinations or external complaints.
What Comes Next in the Process
The Justice Department has until mid-November to respond to the letter. That response could take several forms. It might confirm that a review is already underway. It might state that the facts have been examined and no further action is planned. Or it might indicate that the department will open a new inquiry. Any of those outcomes will shape the next chapter of the story.
Meanwhile the bank continues its remediation efforts. Public statements emphasize the scale of investment already made and the progress achieved. Whether those steps satisfy both regulators and political critics remains an open question. The prior cease-and-desist order provides a ready benchmark for measuring improvement.
For investors and market observers, the episode adds another layer of scrutiny to the institution’s operational risk profile. Large penalties and public political pressure can influence reputation and, in some cases, share performance over shorter periods. Longer term, the real impact will depend on how thoroughly the underlying issues are resolved.
Lessons Emerging From This Episode
Several practical takeaways stand out. First, prior regulatory orders deserve sustained attention. When progress lags, further enforcement often follows. Second, the quality of internal detection systems matters as much as the volume of resources devoted to them. Third, the distinction between civil and criminal exposure continues to shape how institutions assess risk.
I keep returning to the human element. Compliance is not only about technology and policies. It is about whether people inside the organization feel empowered to raise concerns and whether leadership consistently reinforces that those concerns will be taken seriously. When revenue pressure dominates, the balance can tip in the wrong direction.
The current demand for a criminal probe keeps that tension in public view. It forces a conversation about whether existing tools deliver the right mix of accountability and deterrence. Whatever the Justice Department decides, the underlying facts of the case will continue to influence how banks approach anti-money-laundering responsibilities.
Understanding the National Security Dimension
The portion of unreported activity tied to national-security priorities deserves special attention. Patterns associated with certain foreign money-laundering networks and border-related transactions raise stakes that go beyond ordinary financial crime. Banks play a critical role in identifying and reporting such activity so that authorities can respond.
When those reports arrive late or not at all, the protective function of the financial system weakens. That reality helps explain why the enforcement action was framed as one of the most significant in recent memory. It also helps explain the intensity of the political response that followed.
In my view, this dimension makes the call for further review more understandable. Civil penalties address institutional failures. A criminal inquiry would examine whether any individuals bore responsibility for decisions that allowed high-priority risks to go unaddressed for too long.
How Institutions Typically Respond to Major Enforcement
After large settlements, banks usually accelerate remediation programs, hire additional compliance staff, upgrade technology platforms, and enhance training. They often create new oversight structures and report progress to regulators on a regular schedule. The current case appears to follow that pattern, with the bank emphasizing the scale of its ongoing investments.
Yet the persistence of problems after an earlier order suggests that simply spending more money does not guarantee rapid results. Culture, accountability structures, and the integration of compliance into business decisions all influence outcomes. Those softer factors are harder to measure and harder to fix quickly.
Perhaps that is why the senator framed the civil penalties as insufficient. She sees them as treating symptoms rather than addressing root causes that may involve individual decision-making at senior levels. Whether a criminal investigation would ultimately produce charges remains unknown. The request itself, however, keeps the pressure elevated.
The Ongoing Debate Over Deterrence
Does a multi-billion-dollar civil settlement change behavior more effectively than the threat of criminal prosecution? That question sits at the heart of the current disagreement. Supporters of the civil approach point to the record size of the fine and the detailed remediation requirements that accompany it. Critics argue that without personal criminal risk, the incentive structure remains incomplete.
Both perspectives have merit. Large fines do force boards and executives to pay attention. They also fund government efforts and send public signals. At the same time, the possibility of individual indictment concentrates minds in a different way. The law provides both options for willful violations, so the debate is really about when each tool is most appropriate.
The letter asks the Justice Department to make that judgment in this specific case. The answer, when it comes, will add another data point to the larger conversation about financial regulation and accountability.
Looking Ahead
The next few weeks will clarify the immediate direction. A formal response from the Justice Department will either open a new chapter or close this particular request. Regardless of that outcome, the underlying compliance challenges remain. The bank must continue demonstrating that its systems and culture now meet regulatory expectations. Other institutions will continue refining their own programs in light of the lessons visible here.
For anyone who follows financial regulation, this episode underscores a recurring truth. Detecting and reporting suspicious activity is fundamental to the integrity of the banking system. When that function falters at scale, the consequences reach far beyond any single institution. The political demand for a criminal probe simply makes that reality more visible.
I will be watching how the story develops. These cases rarely end with a single settlement. They tend to produce longer arcs of remediation, oversight, and occasional further enforcement. The current push for criminal scrutiny adds an extra layer of uncertainty and potential consequence. Whether that layer ultimately materializes will become clearer soon enough.
In the meantime, the facts already on the table are substantial. Willful violations. Billions in unreported suspicious transactions. National-security dimensions. A prior order that did not fully resolve the issues. And now a high-profile demand that the Justice Department take a harder look. That combination ensures the matter will stay in the public conversation for some time to come.
The financial system works best when banks actively police the flow of illicit funds. When that responsibility slips, the entire structure feels the strain. The current episode is a reminder of both the difficulty of the task and the importance of getting it right. Stronger accountability mechanisms, whether civil or criminal, exist for a reason. How they are applied in this instance will say a great deal about the priorities of enforcement going forward.
Ultimately, the test will be whether the changes now underway produce lasting improvements in detection and reporting. Money continues to move through the system every day. The quality of the safeguards around that movement remains a matter of public interest and regulatory focus. The senator’s letter has simply sharpened that focus at a critical moment.