
I’ve been watching the cybersecurity space tighten for weeks, and last night’s reaction to Fortinet’s numbers felt like the moment the group finally exhaled. Shares across the sector took a hit, and Okta stock found itself caught in the crossfire. At around $222, the name is still up sharply from the spring lows, yet the pullback has traders asking the same question: does the $190 level still hold?
Why Okta Stock Is Suddenly Back On The Radar
The identity business has changed. Employees log in from kitchen tables and coffee shops. The old castle-and-moat network model is mostly gone. What remains is the login itself. That single moment of authentication has become the new perimeter, and Okta sits right in the middle of it.
In my view, the recent wave of deals only underlines how valuable that position has become. Larger security vendors spent the year buying their way into identity. One major player closed a $25 billion acquisition. Others wrote checks ranging from a few hundred million to more than a billion. Okta itself picked up a smaller specialist for just under $200 million. The message is clear: everyone wants a stronger seat at the identity table.
Then the agents arrived. One large healthcare customer reportedly went from fifty AI agents to fifteen hundred in a matter of weeks. Each agent needs an identity that can be tracked, governed, and shut off if something goes wrong. That kind of growth does not show up fully in the current numbers yet, but it is hard to ignore the direction of travel.
The Fundamentals Still Look Solid
The last reported quarter came in clean. Revenue reached $805 million, up 11 percent, a touch ahead of expectations. Adjusted earnings landed at $1.05 versus a consensus closer to $0.97. Remaining performance obligations grew 14 percent, a couple of points faster than the prior period. Free cash flow hit $227 million, translating to a healthy 28 percent margin.
Management nudged full-year guidance higher. Revenue is now expected between $3.22 billion and $3.23 billion. Non-GAAP earnings guidance sits at $3.90 to $3.94. On the AI front, the dedicated agents product is still too small to move the needle in reported figures, yet new products overall accounted for roughly 30 percent of bookings, with identity governance leading the way.
Workforce identity still makes up about 59 percent of annual contract value and is growing around 11 percent year over year. Customer identity contributes the remaining 41 percent and is expanding a bit faster at 13 percent. Those are not explosive growth rates, but they are steady in a market that rewards predictability.
The login is the perimeter now. Everything else is secondary.
At current levels the stock trades at a rich multiple—roughly 57 times the midpoint of next fiscal year’s non-GAAP earnings guidance, with revenue still expanding in the low double digits. On a free-cash-flow basis the enterprise value sits closer to 43 times the guided midpoint of $910 million to $930 million. That valuation leaves little room for disappointment, which is why the December earnings report on the first of the month carries extra weight.
The Chart Tells Its Own Story
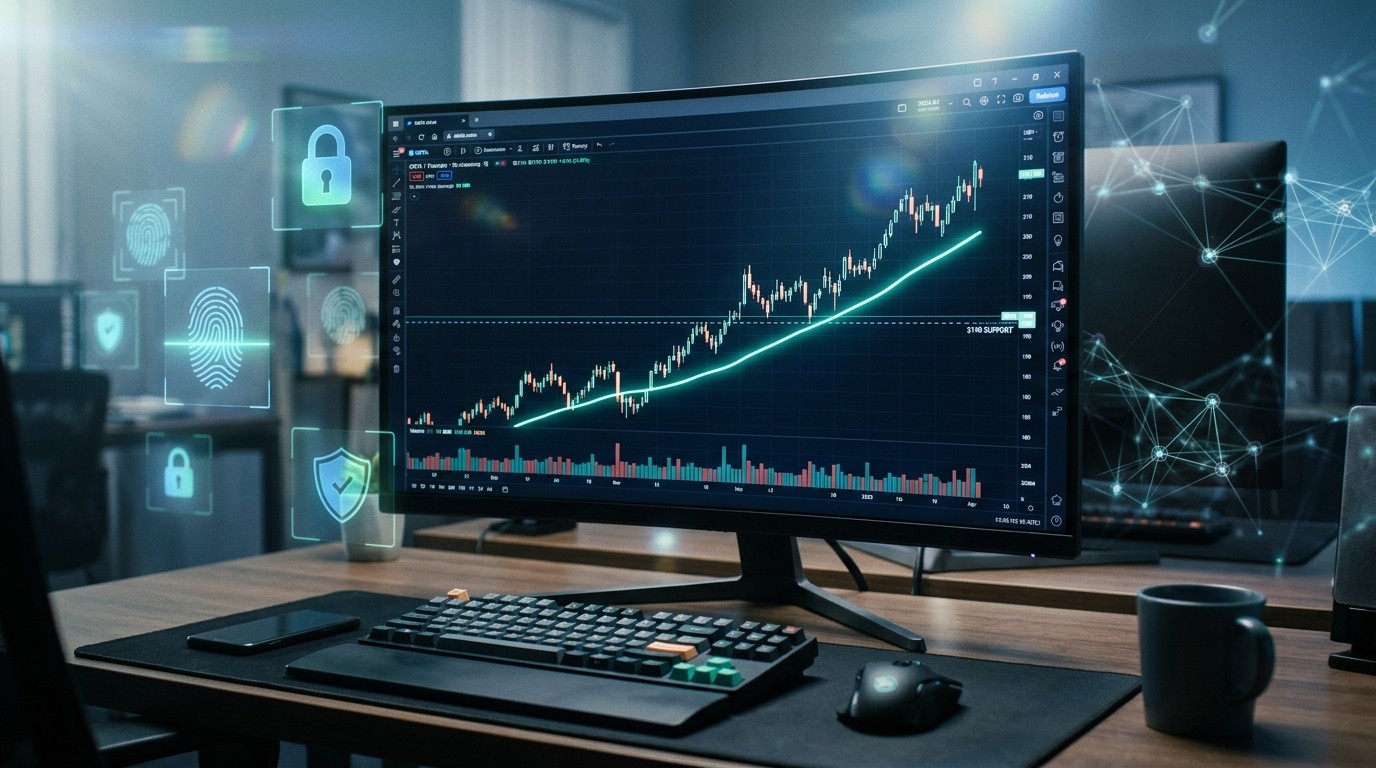
Okta spent the first half of the year stuck under $100. On May 2 the stock gapped higher on heavy volume, opening near $108. Another gap followed on June 1. Neither gap has been filled, the classic behavior of breakaway gaps. From those levels the shares have more than doubled.
The 50-day moving average is now rising through $190. That line has already been tested. On October 20 the stock undercut it briefly, only to reclaim the level the very next session. The October 16 and 20 lows sit just underneath at $185 and $184. Momentum, measured by the relative strength index, has recovered from the low 40s back to around 59. That reading leaves room for another push higher without starting from an overbought condition.
I’ve found that the simplest stops often work best. For short-term traders a daily close below $190 offers a clear invalidation. Longer-term investors might prefer to wait for a weekly close under that same level. Either way, a sustained break would call into question the entire uptrend that began with the May gap.
What A Break Above $235 Could Mean
On the upside, a decisive move through $235 would open the door to a retest of levels last seen five years ago near $300. That is a long way from here, of course, and nothing is guaranteed. Still, the structure of the chart leaves that possibility on the table if the current pullback resolves higher.
The broader cybersecurity group remains sensitive to individual earnings reactions. Soft guidance or even a modest beat that fails to impress has been enough to send names lower this week. Okta itself is up roughly 36 percent since its previous report, so the bar for December is elevated. Beats alone have not always been rewarded lately. Mixed reactions across the tech landscape this week only reinforce that point.
The Acquisition Conversation That Never Quite Dies
People have speculated about Okta as a potential takeout target for years. Recent chatter surfaced again last summer around the same time a major peer was circling another identity name. That particular deal closed at $25 billion. Okta’s rumor faded, yet the stock still climbed from roughly $100 to the current $222 range.
Who might still be looking? A few large platform companies remain without a full-scale identity franchise. Paying a premium for an enterprise value near $40 billion would not be trivial, but the strategic logic is not hard to see. I am not calling for a deal. I am simply noting that the conversation refuses to go away, and that fact itself tends to keep a floor under the shares on soft days.
How The Sector Selloff Unfolded
Fortinet’s post-market numbers failed to clear the high bar investors had set. The reaction was swift. Peer stocks dropped in sympathy. Several large names finished the session down about 6 percent. Okta was pulled lower with the group even though its own fundamentals had not changed overnight.
That kind of correlated move is common in specialized sectors. When one high-profile name disappoints, the entire complex gets marked down first and sorted out later. The sorting process is what we are watching now. Does buying interest appear near the rising 50-day average, or does the selling gather more force?
In my experience, these sympathy moves often create the cleanest risk-reward setups of the quarter. The stock that gets dragged lower without company-specific bad news can bounce hardest once the initial wave of selling exhausts itself. Of course the opposite is also true: if the group continues lower, even the strongest charts eventually follow.
Positioning Around The Key Level
Anyone considering a long position here needs a plan for both outcomes. The $190 zone is obvious support. It lines up with the rising 50-day average and sits just above the recent swing lows. A hold would keep the larger uptrend intact and potentially set up a move back toward the recent highs and beyond.
A clean break lower would shift the short-term bias. In that case the next logical areas of interest sit closer to the mid-180s and then the gap zones left behind earlier in the year. Those gaps still look substantial on the weekly chart and could eventually attract attention if the selling intensifies.
- Daily close below $190 signals short-term trend damage
- Weekly close below $190 questions the entire May-to-present advance
- A reclaim of $235 would reopen the path toward older highs near $300
- RSI near 59 leaves room for further upside without immediate overbought risk
Risk management remains the non-negotiable piece. The cheapest lesson is often the daily close under the key level. Sitting through a deeper drawdown after that signal arrives rarely improves the eventual outcome.
The Bigger Picture For Identity
Step back from the daily noise and the structural case for identity software still looks compelling. Hybrid work is not reversing. Cloud adoption continues. AI agents are multiplying inside enterprises at a pace few expected even a year ago. Every one of those agents requires an identity that can be governed.
Okta already counts more than 20,000 customers, including a large share of the Fortune 100. That installed base provides a natural distribution channel for new products. Whether the company remains independent or eventually becomes part of a larger platform, the underlying demand drivers appear durable.
Valuation is the open question. Growth in the low double digits does not typically support the multiples currently attached to the shares. The market is clearly pricing in an acceleration that has not yet fully appeared in the reported numbers. That gap between expectation and current reality is what makes the December print so important.
Comparing Relative Strength Inside The Group
Okta still carries a smaller weighting inside the major cybersecurity ETFs than some of its better-known peers. That lighter footprint can work both ways. On weak days the stock can lag. On strong days it sometimes needs a catalyst of its own to catch up. The recent sector-wide move has compressed those differences for the moment.
Relative strength versus the broader group will be worth monitoring in the weeks ahead. If Okta begins to hold up better than the names that led the selling, that divergence often precedes a period of outperformance. The opposite pattern would suggest the stock is simply moving with the tide and may continue to do so.
| Metric | Recent Reading | Implication |
| Revenue Growth | 11 percent | Steady but not explosive |
| Free Cash Flow Margin | 28 percent | Healthy conversion |
| RPO Growth | 14 percent | Slight acceleration |
| 50-day MA | Rising near $190 | Key technical support |
| RSI | Around 59 | Room to run higher |
What Could Go Wrong From Here
Several risks sit in plain sight. A broader risk-off move in growth stocks would pressure the entire group regardless of company-specific news. Another soft reaction to an individual peer’s earnings could keep the selling pressure alive. On the company side, any slowdown in remaining performance obligations or a miss on the December guidance would likely be punished given the current valuation.
Competition inside identity is also intensifying. Larger platform vendors are building or buying capabilities. Newer specialized players continue to emerge. Okta’s scale remains an advantage, yet the market is not standing still.
Perhaps the most interesting aspect is how little the stock has needed perfect execution to climb this far. The combination of structural demand, deal speculation, and a clean technical breakout earlier in the year has done most of the heavy lifting. That same combination can reverse if sentiment shifts.
A Practical Framework For The Weeks Ahead
Here is the approach I keep coming back to. Respect the $190 level. Treat a daily close beneath it as a signal that the short-term trend has changed. On the upside, watch for a sustained move through $235 as confirmation that buyers have regained control. Between those two lines the stock can chop without offering a clear edge.
Volume behavior near the support zone will matter. A low-volume drift lower followed by a high-volume bounce would look constructive. Heavy volume on a breakdown would carry a different message. The same logic applies on any attempt to reclaim the recent highs.
Earnings on December 1 will reset the conversation. Until then the chart and the sector tape are the main guides. The identity story itself has not changed. What has changed is the price investors are willing to pay for that story in the near term.
I’ve watched plenty of these sector-wide flushes resolve in both directions. The ones that hold the rising moving average and reclaim momentum often produce the cleanest subsequent advances. The ones that break and stay broken tend to spend more time repairing technical damage than most traders expect. Right now Okta sits at the decision point.
Putting The Pieces Together
Okta remains one of the purest publicly traded ways to own the identity layer of modern enterprise software. The company has scale, a broad customer base, improving cash generation, and exposure to the emerging AI-agent opportunity. Those attributes explain why the stock has more than doubled since the spring and why acquisition talk never fully disappears.
The current pullback is a sector event more than a company-specific one. That distinction matters. It also means the recovery, if it comes, may track the broader group as much as any individual catalyst. The $190 area now serves as the practical line that separates a healthy consolidation from a deeper correction.
Whether you are already long, waiting for a better entry, or simply tracking the name from the sidelines, the next few sessions around that level should clarify the near-term path. Markets rarely hand out perfect information. They do, however, mark the spots where risk and reward become clearer. This is one of those spots.
The identity market is still early in its shift toward agent-heavy environments. Okta is positioned to participate. The stock chart will decide how much of that participation investors get to keep in the coming months. For now the focus stays simple: watch $190, respect the signal it gives, and let the tape do the rest of the talking.
That approach has kept me on the right side of more trends than it has cost me. In a market that continues to reward patience around clearly defined levels, it still feels like the most practical way to navigate the current Okta setup.