
Have you noticed how some industrial metals suddenly start dominating headlines when the world least expects it? Right now copper is doing exactly that. Prices have climbed toward levels that felt almost impossible only a couple of years ago, and the physical market is sending signals that are hard to ignore. What began as steady demand growth has turned into a genuine scramble for available metal, especially in the world’s largest consuming country.
Why Copper Suddenly Feels Scarce Everywhere
The combination of forces pushing the market is unusual. Years of relatively low investment in new mines collided with a fresh wave of consumption tied to power infrastructure and data centers. At the same time, strategic stockpiling in certain regions has tightened the free-floating supply even further. The result is visible in one of the most closely watched physical market gauges: the premium Chinese buyers must pay above the London benchmark just to get their hands on imported copper.
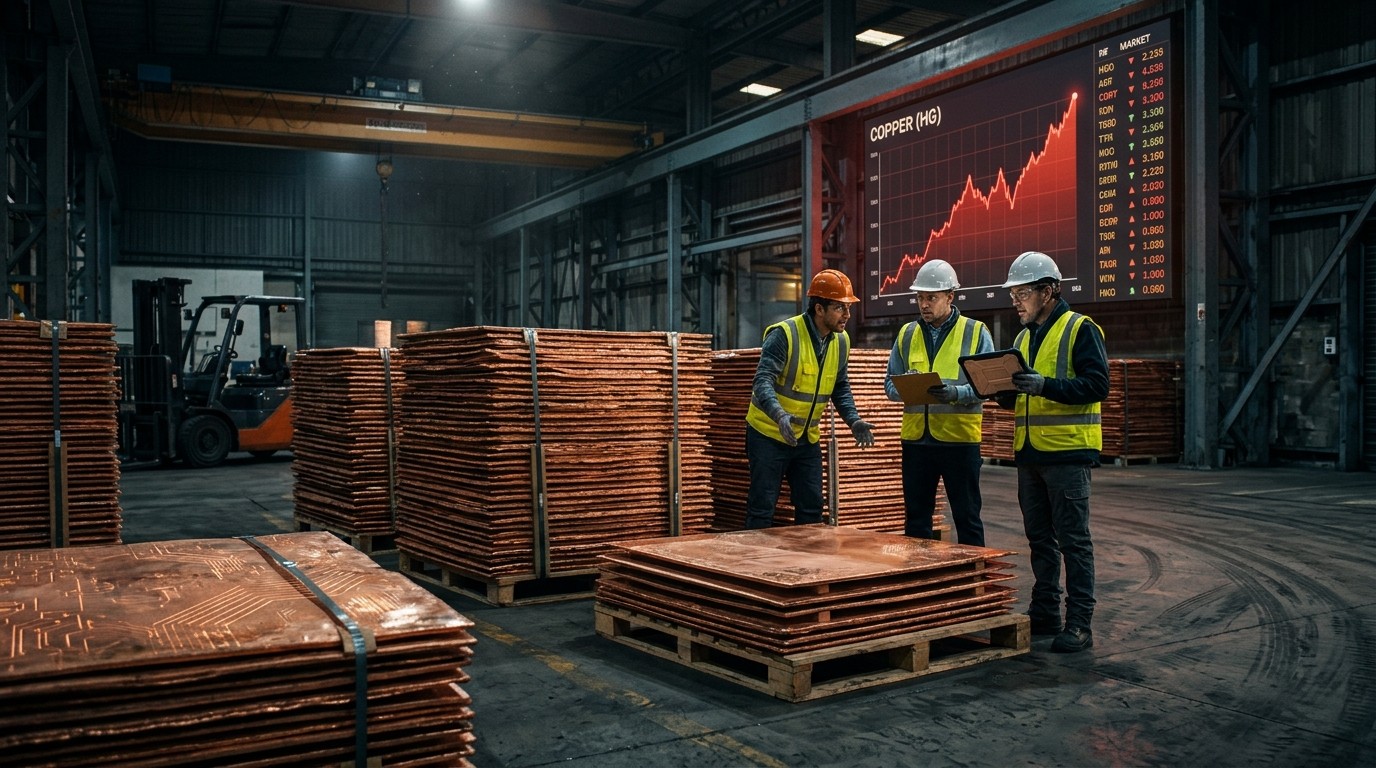
That premium recently climbed above two hundred dollars a ton, a level not seen in the available data history. When importers are willing to pay that much extra simply to secure cargoes, it usually means warehouses and ports are running unusually tight. Analysts monitoring the Chinese market have described the situation in blunt terms. The metal is effectively sold out in many locations, and the elevated premium looks likely to stay high for as long as the scarcity continues.
The Quiet Years of Underinvestment Catch Up
Mining projects take a long time to develop. From the first serious exploration to the first commercial production, ten to fifteen years is not unusual. During the previous decade many companies preferred returning cash to shareholders rather than committing large amounts of capital to new greenfield mines. The logic made sense at the time. Prices were softer, costs were rising, and environmental permitting had grown more complex in several key jurisdictions.
That decision is now colliding with stronger demand. Electrification of transport, expansion of renewable power grids, and the rapid build-out of artificial intelligence infrastructure all require significant quantities of copper. A single large data center can contain miles of copper cabling and substantial amounts of the metal in transformers and cooling systems. When dozens of such facilities are planned or under construction at the same time, the cumulative impact becomes material.
I have followed commodity cycles for years and the pattern feels familiar yet different. Previous tight markets often eased once higher prices stimulated new supply. This time the lag between price signals and actual new production looks longer than usual. Existing mines are aging, ore grades in many regions continue to decline, and the pipeline of truly large new projects remains limited.
China’s Role as the Critical Swing Consumer
China still accounts for more than half of global refined copper consumption. When Chinese buyers become aggressive, the rest of the market feels it quickly. The Yangshan premium serves as a real-time thermometer of that demand intensity. It reflects what importers are prepared to pay above the exchange price to obtain physical material delivered into Chinese ports.
Recent readings have been exceptional. The premium moving decisively above the two-hundred-dollar mark suggests that available nearby material is scarce. Traders and warehouse operators report that inventories in key locations have tightened noticeably. Some participants describe the situation as the metal being effectively sold out across multiple regions at once.
The industrial metal is sold out everywhere and the premium will remain elevated due to supply scarcity.
That kind of language from market specialists is rare. It points to a physical market that is not merely tight but genuinely stretched. When premiums stay elevated for an extended period, fabricators and manufacturers begin to feel the cost pressure. Some may try to pass it on; others may delay projects or look for substitution where technically possible. Substitution, however, is limited in most electrical applications.
Strategic Stockpiling Adds Another Layer of Pressure
Beyond ordinary industrial demand, certain countries have increased their efforts to secure strategic inventories of critical materials. Copper sits high on many of those lists because of its role in energy systems and defense-related applications. When large buyers move to build or expand stockpiles, they remove metal from the open market for extended periods.
This activity has become more visible in recent months. Anticipation of possible trade measures has encouraged some participants to accelerate purchases. The net effect is a further reduction in freely available material at a time when industrial demand is already firm. Markets do not always adjust smoothly to such shifts. Price discovery can become more volatile and physical premiums can diverge sharply from exchange prices.
In my view this stockpiling element is one of the more under-appreciated drivers of the current tightness. Industrial demand alone would have supported prices. Adding strategic buying on top has amplified the squeeze.
What the AI Build-Out Really Means for Copper
Artificial intelligence infrastructure is power hungry. Training large models and running inference at scale requires enormous amounts of electricity. That electricity has to be generated, transmitted, and distributed, and copper sits at the heart of each of those stages. Transformers, busbars, power cables, and grounding systems all consume significant quantities of the metal.
Some market observers have begun to treat copper as a key enabling material for the AI cycle, similar to the way rare earths or high-purity silicon are viewed. The comparison is not perfect, but the direction of travel is clear. Every incremental gigawatt of data-center capacity carries a copper footprint that cannot be ignored.
At the same time, the broader energy transition continues. Electric vehicles, charging networks, and renewable generation all add to the baseline demand. When these structural trends overlap with a period of constrained mine supply, the market balance becomes fragile. Small disruptions in production or logistics can then produce outsized price reactions.
Price Action and the Risk of Overheating
Copper prices have approached the fifteen-thousand-dollar-per-ton area in London at times, a territory that few analysts expected so soon. Such rapid advances naturally invite questions about sustainability. Commodity markets have a long history of overshooting on both the upside and the downside.
Some strategists caution that a correction in the broader AI investment theme could temporarily weigh on sentiment toward related materials. If equity markets reassess the pace of data-center spending, copper could experience a period of consolidation even while the underlying physical tightness remains. Volatility along the way is almost guaranteed.
Still, the medium-term outlook many professionals hold remains constructive. A gain of around ten percent over the next twelve months is viewed as plausible by several commodity desks, provided the supply side does not surprise to the upside. That kind of forecast already builds in the expectation of occasional sharp pullbacks.
How Physical Premiums Differ from Exchange Prices
Exchange prices capture the futures market’s collective view of value. Physical premiums capture the immediate cost of obtaining metal for actual use. When those two diverge significantly, it usually signals stress in the logistics and inventory system.
The recent jump in the Chinese import premium is a classic example. Buyers are not simply expressing a bullish long-term view. They are competing for cargoes that can arrive in the near term. In such conditions, warehouses empty, waiting times lengthen, and the cost of securing prompt delivery rises quickly.
This dynamic can persist longer than many expect. Once inventories fall below critical thresholds, rebuilding them requires either higher prices or a genuine increase in available supply. Neither tends to appear overnight.
Broader Implications for Industrial Costs
Higher copper prices eventually feed through into the cost structure of many industries. Electrical equipment manufacturers, construction firms, and automotive suppliers all feel the impact with different lags. Some can hedge part of their exposure. Others operate on thinner margins and have less flexibility.
In practice the transmission is rarely uniform. Companies with strong pricing power may pass most of the increase on to customers. Those facing intense competition may absorb a larger share, at least temporarily. Over time the higher cost of copper becomes embedded in the capital expenditure budgets of utilities and technology firms planning multi-year infrastructure programs.
Perhaps the most interesting aspect is how little public discussion this cost pressure has received so far. Attention remains focused on the headline price moves and the AI narrative. The quieter reality of rising input costs for the physical economy receives less airtime.
Looking Ahead: What Could Ease the Tightness
Several developments could eventually loosen the market. A meaningful slowdown in Chinese construction or manufacturing activity would reduce near-term demand. Faster-than-expected ramp-up of new mine projects would increase supply. Technological improvements that reduce copper intensity in certain applications could also help at the margin.
None of these factors appears imminent. Most large mining projects currently under development will not contribute significant volumes until later in the decade. Demand-side softness would require a broader economic deceleration that is not yet evident in the data. Efficiency gains tend to arrive gradually rather than in sudden leaps.
In the meantime the market is left navigating a period of elevated physical premiums and heightened price sensitivity to any fresh disruption. That environment rewards careful inventory management and disciplined purchasing strategies. It also creates opportunities for those positioned to supply metal into the tightest locations.
A Market That Rewards Patience and Realism
Commodity cycles rarely move in straight lines. The current copper tightness has been years in the making. It will not resolve in a few weeks or even a few months. Traders who treat every sharp price swing as the start of a new permanent regime usually end up disappointed. Those who focus on the underlying balance between available supply and structural demand tend to navigate the volatility more successfully.
The Yangshan premium sitting at record levels is more than a statistical curiosity. It is a clear message from the physical market that available metal is harder to obtain than the futures curve alone might suggest. When specialists start using phrases like “sold out everywhere,” it is worth paying attention.
For now the combination of underinvestment, rising electrification needs, strategic stockpiling, and concentrated Chinese demand has produced one of the tighter copper markets in recent memory. How long the squeeze lasts will depend on the pace of new supply and the resilience of demand. Both sides of that equation remain uncertain, which is precisely why the price discovery process has become so lively.
Investors and industrial buyers alike will be watching the premium closely in the coming months. If it remains elevated while exchange inventories stay low, the case for higher average prices over the medium term grows stronger. If the premium collapses quickly, it would signal that the scarcity was more temporary than it currently appears. At the moment the evidence still points toward continued tightness rather than rapid relief.
The story of copper in 2025 and beyond is ultimately a story about timing. The world needs more of the metal for the infrastructure of the future, yet the industry has not invested enough in the past to meet that need smoothly. Bridging that gap will take time, capital, and a willingness to accept higher prices as the signal that encourages the next wave of supply. Until that supply arrives, the market is likely to remain restless.
That restlessness is already visible in the numbers. Record or near-record prices, historically high physical premiums, and candid comments from market specialists about widespread scarcity all point in the same direction. Copper has moved from a quiet industrial metal to a strategic material whose availability can no longer be taken for granted. How companies and countries respond to that reality will shape costs and investment decisions for years to come.