
Have you ever left a job and felt that little 401k balance was more trouble than it was worth? I remember watching friends cash out a few hundred dollars just to avoid the paperwork, only to regret it years later when they realized how much growth they had given away. Recent findings show that a new automatic system is finally changing that pattern for the smallest accounts, and the drop in cash-outs is striking.
Why Small 401k Balances Disappear So Easily After Job Changes
Most of us switch employers more than once. In fact, a large share of workers have changed jobs three or more times, and younger generations often lose track of earlier retirement savings entirely. When a balance sits under one thousand dollars, many plans simply send a check. Between one thousand and seven thousand dollars, the money frequently lands in an individual retirement account if the former employee does nothing. Taking the cash feels simple in the moment. Yet that choice carries taxes, a possible ten-percent early withdrawal penalty for anyone under fifty-nine and a half, and the permanent loss of compounding.
I have seen how quickly those small sums vanish from people’s minds. A few hundred dollars does not feel life-changing on a Friday afternoon, so the check gets spent. The long-term cost, however, is real. That money never gets the chance to grow for decades. Automatic portability aims to interrupt this cycle by moving the balance into a temporary safe harbor IRA and then trying to match it with the worker’s next employer plan.
How the Automatic Portability Process Actually Works
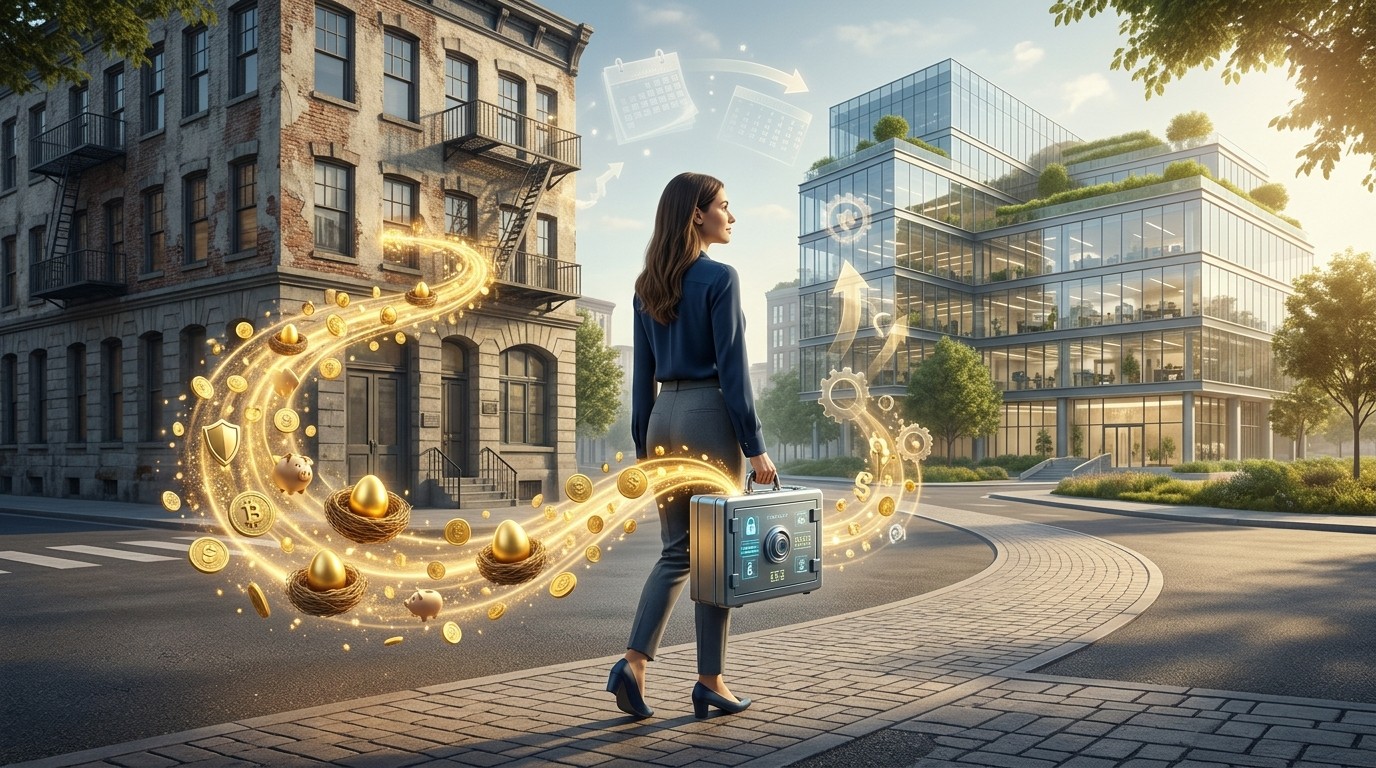
When someone leaves a participating employer, the small balance is generally rolled into a conservative interim account. The network then looks for a match with a new employer plan that also belongs to the same system. If a match appears, the money moves again, this time into the new workplace plan. The goal is simple: keep the savings working without requiring the employee to fill out forms or remember old account numbers.
In practice the first step already delivers results. Among workers whose balances sat under one thousand dollars, the share who cashed out within roughly ten months fell sharply once their former employers joined the network. The drop was smaller but still noticeable for balances between one thousand and seven thousand dollars. Those numbers matter because the typical participant in these transfers is young, has a modest income, and has only a short tenure at the prior job. Their median balance is often just a couple of hundred dollars. Protecting even that amount can set a better habit early in a career.
Yet the second step remains incomplete. Only a small fraction of the accounts that entered the interim IRAs have so far reached a new employer plan. The rest continue to sit and wait. Participation by plan sponsors is still limited, so the matching engine does not yet cover enough workplaces. Workers can always complete a rollover themselves, of course. The entire point of the network, however, is to remove that friction.
The Real Cost of Cashing Out Even a Small Balance
Taxes arrive first. The distribution counts as ordinary income. Then comes the early-withdrawal penalty if the account holder is younger than the usual retirement age. After those hits, the remaining dollars lose decades of potential growth. I have run simple illustrations for people who cashed out a few hundred dollars in their late twenties. By their mid-sixties the difference, assuming ordinary market returns, is often measured in thousands rather than hundreds. That gap is hard to close later.
There is also the quiet psychological effect. Once someone treats retirement money as spending money, the habit can reappear at the next job change. Automatic systems that keep the balance invested help break that pattern before it becomes permanent.
Keeping even modest sums invested through every job transition can compound into meaningful wealth over a full career.
Why So Many Accounts Still Sit in Interim IRAs
The network has already moved tens of thousands of completed transfers and tens of millions of dollars into new employer plans. At the same time, well over a million eligible participants remain unmatched. The number of waiting accounts has continued to climb. The bottleneck is clear: not enough receiving plans have adopted the service. Until more employers join, the automatic hand-off cannot finish for most people.
While the money waits, fees become an issue. Many of these interim accounts sit in conservative cash or short-term investments. Account-level charges can slowly erode a balance of only a few hundred dollars. Earnings may not keep pace. The longer an account stays unmatched, the greater the risk of gradual shrinkage. That is an imperfect solution, yet it is still better than an immediate cash-out for most participants.
Special Complications for Roth Savings
Traditional pre-tax balances move into traditional IRAs without much trouble. Roth balances move into Roth IRAs. The difficulty appears at the next step. Current rules do not allow a Roth IRA to roll into a new employer’s 401k, even if that plan accepts Roth contributions. Technology on the network side is already capable of handling the transfer, but legislation has not yet caught up. Until the rules change, Roth money faces an extra barrier.
This matters more each year as Roth features become common in workplace plans. Younger workers in particular often choose Roth contributions. Leaving those dollars stranded in an IRA undercuts the convenience the automatic system is designed to deliver.
Who Benefits Most from Automatic Portability
The data paint a clear picture of the typical participant. Many are in their early thirties, earn modest wages, and stayed only a short time at the previous employer. Their balances are small by design. These are exactly the people who historically cashed out at the highest rates. Protecting their first few hundred dollars of retirement savings can influence behavior for the rest of their working lives.
Older workers with larger balances already have more options and usually more awareness. The automatic system is less critical for them. The real win appears among early-career savers who might otherwise treat the money as disposable.
- Younger workers with short job tenures see the biggest reduction in cash-out rates
- Balances under one thousand dollars experience the sharpest improvement
- Participants who stay in the interim account still avoid immediate taxes and penalties
- Future matches depend heavily on wider plan-sponsor adoption
Practical Steps Workers Can Take Right Now
Even if your current or former employer participates, you remain free to move the money yourself. Locating old accounts, requesting a direct rollover into a new workplace plan or a consolidating IRA, and confirming the transfer can still be the fastest route. Keeping good records of every former plan helps. Many people discover forgotten balances only years later, after fees or market moves have already taken a toll.
If you receive notice that a small balance is heading into a safe harbor IRA, treat it as a temporary holding pattern rather than a final destination. Check whether the new employer’s plan accepts incoming rollovers and whether it belongs to the same network. A short conversation with the benefits team can clarify the next move.
I have found that simply tracking every old account in one secure place prevents the “out of sight, out of mind” problem that leads so many balances to disappear. A simple spreadsheet or a secure notes app is often enough.
Looking Ahead: Wider Adoption and Possible Rule Changes
The network continues to add plans, yet coverage remains far from universal. Broader participation by employers would unlock the second half of the process for the large pool of waiting accounts. At the same time, advocates are pushing for legislative updates that would allow Roth dollars to move as freely as traditional balances. Both developments would make the system far more effective.
Until those changes arrive, the existing framework already delivers a measurable public good. Cash-out rates for the smallest balances have fallen dramatically among participating plans. That alone keeps more money invested and working for the people who need it most. The incomplete matching stage is a genuine limitation, but it is a solvable one.
In my view the most encouraging part of the story is the behavioral shift. When the path of least resistance stops being a cash check and becomes continued investment, people keep more of their future wealth. The system is not perfect. Fees in interim accounts can nibble at tiny balances, Roth money faces extra hurdles, and matching still depends on more employers joining. Still, the early evidence shows that automatic portability can change outcomes for the workers who historically lost the most.
Job changes will remain a normal part of modern careers. The question is whether the retirement savings attached to those jobs can travel as easily as the workers themselves. The data so far suggest we are moving in the right direction, even if the journey is only partially complete. Paying attention to every small balance, asking the right questions when you change employers, and treating those dollars as the start of something larger rather than spare cash can make a lasting difference. The automatic tools now available simply make that discipline easier to maintain.
Over the coming years the success of this approach will depend on two practical factors: how many additional plan sponsors decide to participate and whether rule updates eventually open the door for Roth balances. Workers themselves retain the final say. Staying informed, consolidating when it makes sense, and resisting the urge to cash out remain the most reliable strategies. Automatic systems can support those choices, but they cannot replace personal attention entirely.
The drop in cash-out rates already proves the concept works at the first stage. Expanding the second stage so that more money reaches new employer plans is the logical next goal. Until that happens, the interim accounts serve as a holding pattern that is imperfect yet clearly preferable to an immediate taxable distribution for most people. Keeping an eye on fees, monitoring account statements, and initiating a manual rollover when a better destination appears will protect the progress that has already been made.
Perhaps the quietest benefit is cultural. When successive generations of workers experience automatic continuity instead of repeated small losses, the habit of treating retirement money as permanent capital becomes stronger. That shift, more than any single transfer, may prove the lasting contribution of these networks. For anyone who has ever watched a modest balance disappear after a job change, the new numbers offer a concrete reason for optimism.
The path forward is straightforward even if the infrastructure is still growing. Employers can expand participation. Policymakers can address the Roth limitation. Individuals can stay engaged with every account they own. Together those steps turn a promising early result into a durable improvement in how retirement savings survive the ordinary turbulence of modern careers. The evidence already shows that fewer people are cashing out. The remaining task is to make sure the money that stays invested eventually finds its permanent home in a new workplace plan.
That outcome is within reach. The technology exists. The early results are encouraging. Wider adoption and a few targeted rule adjustments would close most of the remaining gaps. Until then, every worker who keeps a small balance invested instead of cashing it out is already winning a quiet but meaningful victory for their future self.