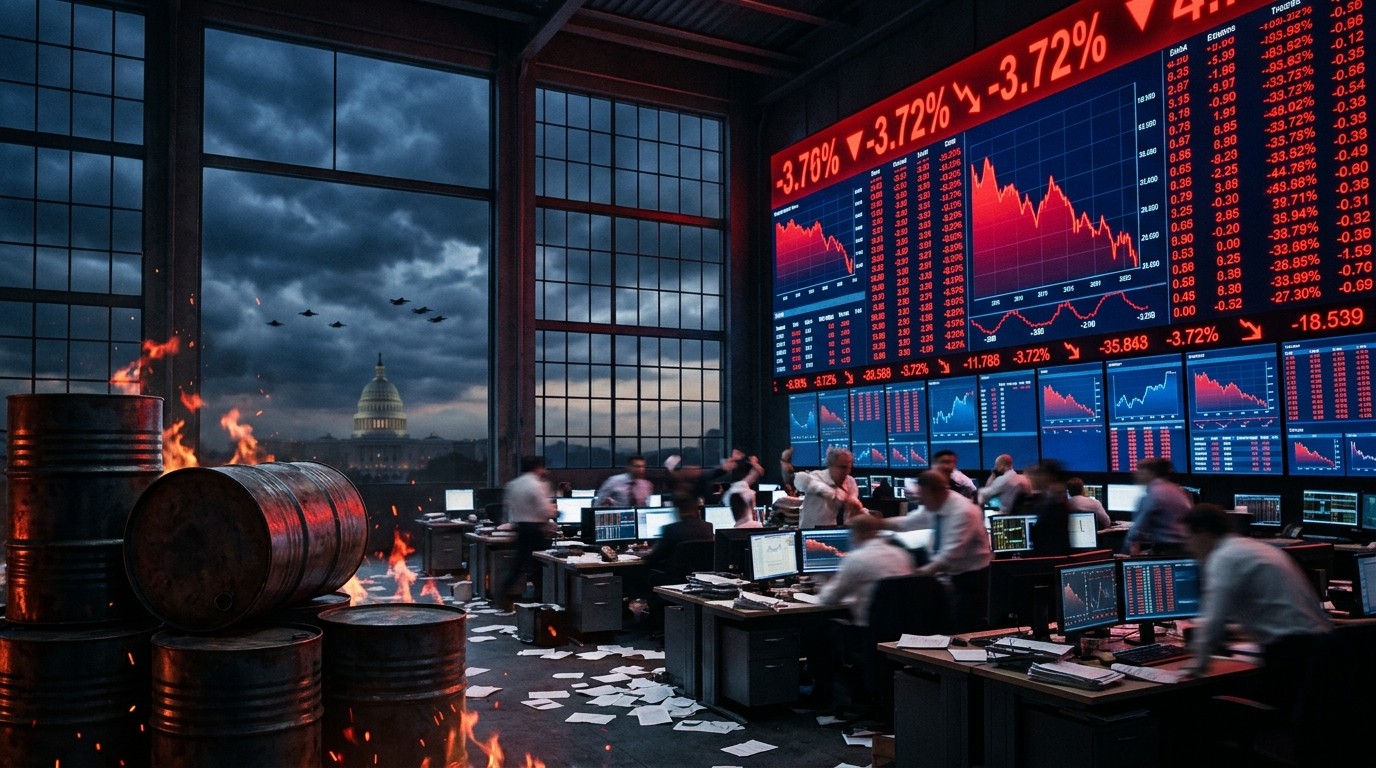

Have you ever watched the market climb steadily only to wonder what single sequence of events could erase almost an entire year of progress in a matter of weeks? That question has been on my mind lately as election season intensifies and geopolitical headlines keep shifting. One detailed scenario analysis recently laid out a path that could send the S&P 500 tumbling more than 10 percent by year-end, wiping out the roughly 11 percent advance posted so far this year and leaving the index near 6,800. It is not the base case, yet the logic behind it feels uncomfortably plausible when you line up the pieces.
Understanding The Most Bearish Post-Midterm Path
The core of this darker outlook rests on two simultaneous developments. First, a Democratic sweep of both chambers of Congress that triggers prolonged disputes over the results. Second, an escalation of military action involving Iran before the new Congress takes its seats in January. Analysts described this combination as kinetic escalation, a term that captures the sudden jump from diplomatic tension to active confrontation. In their view, the market would not treat the resulting pullback as a routine opportunity. Instead they labeled it a dip not to be bought, warning of an oil price surge, widening credit spreads, and a broader economic slowdown that could set a difficult tone for early 2027.
I find this framing useful because it forces investors to separate ordinary election noise from genuine regime-shifting risks. Most midterm periods produce some volatility, yet the addition of an energy shock changes the entire character of the sell-off. When crude oil climbs and stays elevated for weeks, corporate margins compress, consumer spending cools, and risk assets reprice quickly. That is the mechanism that turns a temporary dip into a more sustained correction.
How Election Outcomes Shape Market Expectations
Election results rarely move markets in isolation. What matters more is the clarity of the outcome and the policy implications that follow. In the scenario where one party secures both chambers and the result faces immediate legal challenges, uncertainty multiplies. Investors begin to price in legislative gridlock or aggressive policy shifts depending on which side prevails. Credit markets often react first, with spreads widening as participants demand higher compensation for political risk.
According to recent market commentary, a disputed Democratic sweep without further geopolitical complications still leaves the S&P 500 finishing the year only modestly higher than recent levels. The initial reaction might be negative, yet analysts view that pullback as a buying opportunity because it signals a potential opening for bipartisan approaches on certain foreign-policy files. The absence of military escalation becomes the key differentiator. Markets appear more willing to look through political friction when energy prices remain contained.
Contrast that with the full bearish combination. Once kinetic action enters the picture, the calculus flips. Oil becomes the transmission channel that turns political uncertainty into an economic event. I have watched similar episodes in past cycles, and the speed at which sentiment can shift is often underestimated. Traders who initially treat the election as background noise suddenly find themselves recalibrating entire portfolios within days.
The Critical Role Of Oil Prices In This Scenario
Energy markets sit at the heart of the downside case. West Texas Intermediate has already been trading near the $100 mark, leaving limited cushion if supply disruptions materialize. A prolonged period above $120 per barrel, or a spike toward the previous all-time high near $147, would represent a genuine shock. At those levels, transportation costs rise, manufacturing input prices climb, and household budgets tighten. Corporate earnings forecasts begin to roll over, and equity valuations compress in response.
The analysis is careful to note that temporary spikes are manageable. The real damage comes when elevated prices persist for a month or longer. That duration gives businesses time to pass costs along or cut spending, and it gives consumers time to adjust behavior. Credit conditions often tighten in parallel as lenders reassess exposure to energy-sensitive sectors. The combination of higher oil, wider spreads, and slowing growth creates a feedback loop that is difficult to interrupt once it gathers momentum.
In my experience, markets can tolerate political drama far more easily than they can tolerate sustained energy inflation. The latter hits every corner of the economy at once. That is why the researchers singled out the oil threshold as the exception to their otherwise constructive stance on buying election-related weakness.
Comparing Bullish, Base, And Bearish Year-End Targets
To put the numbers in perspective, the same research team sketched three distinct paths. The most optimistic assumes Republican control of both chambers, an undisputed result, and a diplomatic breakthrough that brings oil prices down sharply. Under those conditions the S&P 500 could reach 8,400 by year-end, representing more than 11 percent upside from recent closes. That outcome is described as unlikely, yet it illustrates the upside potential if both political and geopolitical clouds clear simultaneously.
The middle-ground scenario envisions a divided Congress, a clean election result, and no military escalation. The year-end target in that case sits at 7,750, a modest gain of less than 3 percent. Analysts characterize this as a near-term status quo that gradually evolves toward bipartisan solutions on key foreign-policy issues. Importantly, the firm left its baseline target unchanged at that same 7,750 level, reflecting confidence that underlying economic strength and earnings growth can still carry the market higher.
The darkest path, as noted earlier, points toward 6,800. That figure erases this year’s gains and then some. What stands out is the asymmetry. The distance from the base case to the bullish outcome is meaningful, yet the distance to the bearish outcome is larger still once oil and credit markets react. Investors who size positions solely around the central case may find themselves under-hedged if the left-tail scenario begins to unfold.
Macro Pressures Already Visible In The Backdrop
Even without a full-blown crisis, several macro factors are already tightening the environment. The gap between two-year and ten-year Treasury yields has narrowed, a classic signal that growth expectations are moderating. Market participants widely expect the Federal Reserve to raise rates at its December meeting, adding another layer of pressure on equity valuations. At the same time, the largest cloud-computing and data-center operators face mounting financing needs to support the next phase of artificial-intelligence infrastructure.
Hyperscalers are projected to require capital for roughly $1.3 trillion in 2027 capital expenditures. That figure is large enough to strain credit markets four years into a bull market that began in late 2022. When large issuers flood the market with new debt or equity, existing holders can feel the dilution and the higher cost of capital. The timing matters. An election-driven risk-off episode coinciding with heavy issuance calendars could amplify the move lower.
I keep returning to the idea that the AI build-out has become a double-edged sword. On one hand it supports earnings growth and productivity narratives that have powered much of the recent advance. On the other hand the sheer scale of required investment introduces new sensitivity to financing conditions. Any sustained rise in interest rates or risk premiums makes that capital more expensive and potentially delays projects.
Public Sentiment Around Data Centers And AI Infrastructure
Interestingly, the physical footprint of the AI boom has become a political issue in its own right. Survey data shows that a large majority of voters oppose having AI data centers located near their homes. Opposition runs especially high among Democratic-leaning respondents, yet the broader electorate also expresses clear reservations. Only a small minority of all voters support nearby facilities. This local resistance can translate into permitting delays, higher costs, and political friction that ultimately affects the companies driving market leadership.
When stocks are already trading on elevated expectations for AI-related growth, any doubt about the speed or cost of the build-out can pressure multiples. The researchers noted that stocks are likely to come under pressure if doubt is cast on election outcomes, precisely because the policy and regulatory environment around these projects remains unsettled. That observation feels especially relevant given how concentrated recent gains have been in a handful of technology and communication names.
Why Most Election Weakness Still Looks Buyable
Despite the vivid description of the left-tail scenario, the overall recommendation remains constructive. Continued economic strength should support corporate earnings, and any midterm-driven downside volatility is viewed as an opportunity to add to core AI-centric exposure. The expectation is that new all-time highs remain possible in late 2026 or early 2027 once the immediate political noise fades.
The exception is explicit. Should kinetic escalation drive oil prices above the critical thresholds for a sustained period, the buy-the-dip stance is withdrawn. In that case an economic slowdown, credit widening, and a longer, deeper market downturn become the base expectation. The distinction is important. Investors are being asked to treat most forms of election uncertainty as temporary, while treating a genuine energy shock as potentially structural.
The exception to buy the dip is our view that should kinetic escalation with Iran drive oil above critical levels for a prolonged period, an economic slowdown, credit widening and a longer and deeper market turndown would result.
That single sentence captures the entire risk-management framework. Everything else is noise that can be bought. The oil-and-geopolitics combination is the signal that changes the playbook.
Portfolio Positioning In A High-Uncertainty Window
Preferred exposures remain centered on the sectors most closely tied to artificial intelligence. Overweight recommendations in information technology, communication services, and consumer discretionary reflect the belief that structural growth trends will ultimately outweigh short-term political volatility. The logic is straightforward. Companies that can deliver measurable productivity gains or platform advantages should continue to attract capital once the immediate fog lifts.
At the same time, the analysis implicitly argues for maintaining some dry powder or hedges against the left-tail outcome. Concentrated portfolios that have ridden the AI wave higher are especially exposed if an oil shock arrives. Diversification into areas less sensitive to energy prices or more defensive in character can provide ballast without requiring a full retreat from growth themes.
I have found that the most resilient approach in these windows is to size positions so that a 10 percent drawdown remains uncomfortable but not catastrophic. That discipline leaves room to add if the more constructive scenarios play out, while limiting damage if the darker path materializes. No one can predict with certainty which outcome will dominate, yet the preparation for both is within every investor’s control.
Historical Context For Midterm Market Behavior
Looking back across previous midterm cycles, markets have often experienced elevated volatility in the months surrounding the vote, only to recover once the policy outlook clarified. The difference this time is the simultaneous presence of elevated oil prices, a late-cycle bull market, and an enormous capital-expenditure cycle in technology. Those overlapping factors raise the stakes. A routine political wobble could be amplified by the existing macro pressures in ways that earlier midterms did not experience.
Perhaps the most interesting aspect is how quickly sentiment can pivot from one narrative to another. In the space of a few trading sessions, the market can move from pricing a soft-landing continuation to pricing a stagflationary scare. The speed of that transition is why scenario planning matters more than single-point forecasts. By mapping the pathways and the associated triggers, investors gain a clearer sense of when to lean into weakness and when to step aside.
Practical Steps For Navigating The Coming Weeks
First, monitor oil prices and credit spreads with greater intensity than usual. Those two indicators will likely provide the earliest warning that the left-tail scenario is gaining traction. Second, reassess the concentration of AI-related holdings. The same names that have driven performance can amplify losses if risk appetite evaporates. Third, keep liquidity available. Opportunities tend to appear quickly when forced selling hits, and cash or near-cash reserves create optionality.
- Watch crude oil for sustained moves above key psychological and technical levels
- Track corporate bond spreads for signs of risk aversion spreading beyond equities
- Review portfolio beta and sector concentration relative to the broader market
- Maintain a short list of high-conviction names to add on meaningful weakness
- Avoid overreacting to every poll or procedural headline that lacks economic consequence
These steps sound simple, yet they are frequently neglected when headlines grow loud. The investors who fare best are usually those who have already decided their response thresholds in advance rather than improvising under pressure.
The Longer-Term Outlook Beyond The Immediate Noise
Even in the bearish scenario, the analysis does not abandon the structural case for technology and AI-related growth. The capital-expenditure cycle may slow or become more expensive under higher oil and tighter credit, yet the underlying demand for computing power and software solutions is unlikely to disappear. What changes is the timing and the valuation at which those opportunities become attractive again.
If the more constructive paths dominate, the path of least resistance remains higher, supported by earnings growth and eventual policy clarity. The base-case target of 7,750 already embeds a degree of caution, leaving room for upside surprises if oil remains contained and election disputes resolve without lasting damage. In either event, the next several months are likely to feature more noise than signal. Distinguishing between the two will separate reactive trading from deliberate investing.
I keep coming back to the idea that markets discount the future, not the present. Today’s prices already embed a range of election and geopolitical outcomes. The real question is whether the eventual reality diverges enough from that embedded range to force a meaningful revaluation. The scenario that takes the S&P 500 down more than 10 percent represents exactly that kind of divergence. It is not the most probable path, yet it is coherent enough to deserve a place in any serious risk discussion.
Balancing Optimism With Realistic Contingency Planning
There is a natural human tendency to dismiss left-tail risks when markets have been resilient for years. That tendency is understandable. After all, the bull market that began in late 2022 has already absorbed multiple shocks and continued higher. Yet resilience is not the same as invulnerability. The combination of political uncertainty and energy-market vulnerability creates a genuine test.
The research is careful not to present the 6,800 outcome as a forecast. It is framed as a risk that warrants attention. That distinction matters. Investors who treat every scenario analysis as a prediction often end up over-hedging or under-participating. Those who treat it as a contingency map can prepare without abandoning their core thesis. In practice that means holding a core allocation to structural growth themes while maintaining the flexibility to reduce risk if oil and credit markets begin to confirm the darker narrative.
Perhaps the most useful takeaway is the clarity of the decision rule. Most forms of election-related weakness can be bought. The oil-shock version cannot. Simple rules like that are rare in markets, and when they appear they deserve respect. They reduce the need for constant second-guessing and allow investors to focus on execution rather than endless speculation about every new headline.
Final Thoughts On Preparing For Multiple Outcomes
The weeks surrounding a midterm election always feel more dramatic than they ultimately prove to be. This cycle may follow that pattern, or it may not. The difference will likely hinge on whether geopolitical tensions remain contained and whether energy prices stay within ranges that the economy can absorb. Everything else is secondary.
For those managing capital through this period, the priority is not to predict the exact path but to ensure that portfolios can survive the least favorable one while still participating in the more probable constructive outcomes. That balance is never perfect, yet it is achievable with deliberate position sizing, attention to leading indicators, and a willingness to update views when the data change.
The scenario that could take the S&P 500 down more than 10 percent is a reminder that markets remain vulnerable to sudden shifts in the geopolitical and energy landscape. It is also a reminder that most other forms of political noise have historically been temporary. Holding both truths at once is the practical challenge of the moment. Investors who manage that dual awareness stand the best chance of navigating whatever sequence of events ultimately unfolds.
In the end, the market will tell us which path is real. Until then, preparation beats prediction, and clarity about risk thresholds beats constant speculation. Those principles have served disciplined investors well across many previous cycles, and there is little reason to abandon them now.