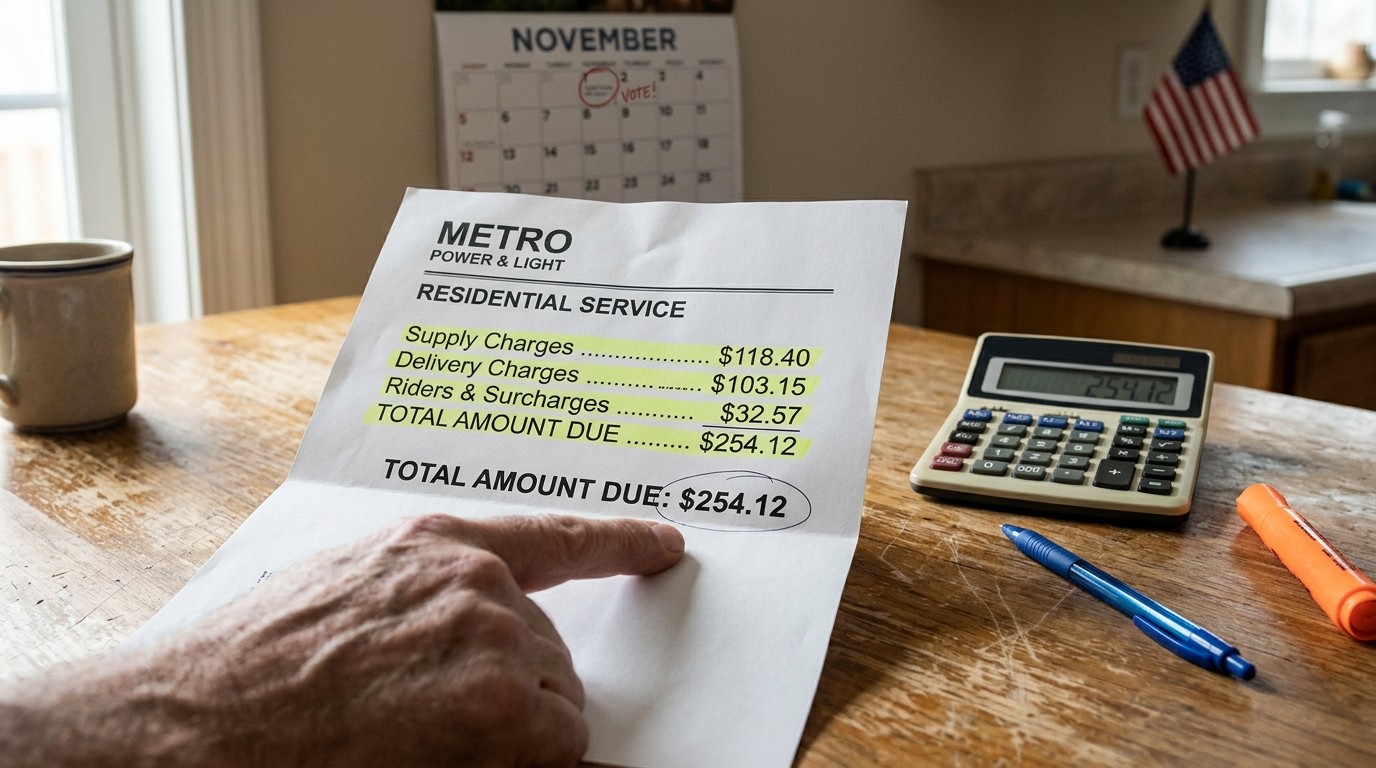

Have you opened your latest electric bill and felt that familiar jolt of disbelief? That number staring back at you – sometimes flirting with $250 or more – has turned from a quiet monthly annoyance into one of the loudest issues of this midterm season. For the first time in a long while, the cost of keeping the lights on sits right at the center of political conversations across the country.
The Quiet Climb That Suddenly Got Loud
Electricity prices have been marching upward for years, but the pace picked up after 2020. The electricity piece of the consumer price index has climbed roughly 43 percent since the start of that year, while overall prices rose closer to 30 percent. The average cost of a kilowatt-hour jumped from about 13.4 cents to nearly 19.6 cents. That is a 46 percent increase in the price of the power itself.
Interestingly, the rise did not belong to one party or one administration. Between early 2021 and early 2025 the average price per kilowatt-hour rose around 32 percent. Then it added another 9.5 percent in the following stretch – the very period when many voters expected energy costs to ease. Bipartisan consistency, if nothing else.
I’ve watched these numbers for a while, and the pattern feels familiar. Small monthly bumps rarely trigger outrage. Then one bill arrives that is noticeably heavier, and suddenly everyone starts talking. That is exactly where we stand now.
Three Pieces That Make Up Every Bill
Most residential electric bills break into three broad categories. Supply charges cover the actual generation of power. Delivery charges pay for the poles, wires, transformers and the people who maintain them. Then come the other charges – taxes, public benefit programs, low-income assistance, clean-energy mandates and, in some regions, wildfire-related costs.
The mix of those three pieces changes dramatically depending on where you live. In one New York City sample for a modest apartment using 242 kilowatt-hours, the pure electricity portion was only about 30 percent of the total. The rest – nearly 70 percent – went to delivery, taxes and system benefit charges. Cross the river into New Jersey and the picture often flips. Generation can account for 70 percent or more of the bill while the utility’s own delivery charges shrink in relative importance.
Nationally the generation share has slipped from around 62 percent of the average price in 2015 to roughly 56 percent a decade later. Distribution and transmission have claimed larger slices. The grid itself, and the returns utilities earn for expanding it, is taking a bigger bite of every dollar customers pay.
Riders: The Charges That Skip the Spotlight
If you have ever tried to read a full utility bill and given up halfway, the riders are probably the reason. These are specialized, state-approved mechanisms that let utilities recover specific costs without waiting for a full rate case. Fuel adjustments, storm recovery, energy-efficiency programs, low-income assistance, tree-trimming reliability work, smart-meter investments, economic-development charges – the list grows.
One Ohio residential bill totaling nearly $253 offers a clear illustration. Generation made up about 48 percent and the utility explicitly noted it earns no profit on that portion. The formal base rates that politicians usually argue about accounted for only 22 percent. The remaining ten line items – the riders – added up to more than the base rates themselves. Those extra charges simply appear. Most customers never see a public hearing about them.
In parts of the Northeast the story looks similar with different labels. Supply, transmission and local delivery form the core, then public-benefit charges pile on top. Some of those public-benefit fees can reach 6 or 7 percent of the total bill. Customers of municipal utilities often avoid several of these policy-driven add-ons entirely.
The Capacity Charge That Exploded
In the nation’s largest grid region the capacity market has become the single most dramatic driver. Capacity payments compensate power plants for being available when needed. When older plants retire and new demand – especially from data centers – surges, those capacity prices can skyrocket.
One recent auction cycle saw capacity prices jump from under $30 per megawatt-day to nearly $270, an increase of roughly 833 percent, before hitting a hard price cap the following year. That elevated level has largely stayed in place. On individual customer bills the effect showed up as 25 percent year-over-year jumps in the supply portion, followed by further step-ups the next month. Delivery charges, the part the utility itself earns on, actually declined in several of those same periods.
Statistical links are strong. One utility’s average annual bills tracked capacity prices with a correlation around 73 percent. Add natural-gas prices into a broader model and the explanatory power climbs near 88 percent over a multi-year span. In other words, in certain states the bill is largely a function of two numbers that no single governor controls directly.
Data centers have played an outsized role. Independent market monitoring attributed nearly half of recent multi-year capacity costs – tens of billions of dollars – to the rapid growth of large computing facilities. Projections suggest those same facilities will continue adding substantial amounts to customer bills for several more years, even with the price cap in place.
The Rate-Base Engine That Never Sleeps
While capacity markets create sudden spikes, utility capital spending creates a steadier upward pressure. Regulated utilities earn a return on their rate base – the net value of poles, wires, substations and other assets they have built. The more they invest, the larger the rate base becomes, and the more revenue they are allowed to collect from customers.
That structure is not a conspiracy. It is simply how the regulatory model works. Utilities are valued by investors largely on the growth of that rate base. Recent analysis of national data found that prices at investor-owned utilities rose about 34 percent since 2020, compared with roughly 19 percent at publicly owned systems. The difference shows up in real-world examples: one retiree in Massachusetts paying more than twice the rate of a neighbor served by a municipal utility across a small lake.
Spending plans remain aggressive. Utilities continue filing large rate-increase requests, and capital budgets over the next five years are projected in the trillions of dollars across the investor-owned sector. Base-case forecasts still show average residential bills climbing from around $1,900 a year toward $2,150 by the end of the decade. Under higher capital-spending scenarios the average could approach $2,600, with annual growth rates near 8 percent for several years.
Much of the investment is genuinely needed. The grid is aging. Extreme weather keeps driving expensive storm recovery. And someone has to connect the new load from data centers and electrification. The open question is simply who pays for the next gigawatt of capacity and transmission.
Does It Really Hurt That Much?
Here the story gets more nuanced. Residential electricity still represents only about 2.7 percent of disposable income on average, and some projections expect that share to edge slightly lower over the next few years if income growth continues. There is surprisingly little correlation between the states with the fastest bill increases and those with the highest overall burden.
A district with a 55 percent three-year jump can still show one of the lowest burdens relative to income. Meanwhile states with slower price growth sometimes carry heavier household loads. Perception appears driven more by the year-over-year change than by the absolute share of the budget. People notice when the bill is higher than last year’s bill. They notice less when their paycheck has also grown.
Seasonal swings amplify the feeling. A household that paid around $100 in a mild winter month can easily see $450 or more during a hot summer. The increases also arrive in small increments that stay almost invisible until one particular bill arrives and forces the double-take.
For lower-income households the math is far less abstract. The average monthly bill can require the equivalent of more than twelve hours of work at the state minimum wage – nearly a third of a standard work week in some places. In higher-cost states the figure climbs past twenty hours. That is a real squeeze, not just a political talking point.
What the Numbers Suggest Going Forward
Base-case outlooks currently point to bill inflation of nearly 6 percent in the near term, then a gradual easing toward 2 percent later in the decade. That path assumes capacity prices remain capped, capital spending stays closer to moderate scenarios, and data-center driven costs do not accelerate further. Any one of those assumptions slipping would push the moderation further into the future.
Political pressure is already visible. Rating agencies have flagged the sector outlook as more challenging, citing the risk that regulators and elected officials will push harder to limit both bills and utility returns. Some utilities with heavy exposure to the tightest capacity markets have seen analysts turn more cautious on growth prospects for exactly these affordability reasons.
The conversation itself has shifted. The question is no longer mainly whether large new computing facilities should be built. It has become who should pay for the generation and transmission those facilities require. One practical suggestion that keeps resurfacing is requiring major new loads to arrange more of their own power supply behind the meter rather than relying entirely on the shared grid.
Whether that idea gains traction or not, the underlying tension will not disappear after election day. The grid still needs investment. Demand from data centers and electrification continues to grow. Capacity markets remain tight in key regions. And households will keep opening envelopes that feel heavier than they did a few years ago.
Putting the Pieces Together
When you line up the three main cost buckets, the growing role of riders, the capacity-market spikes, and the steady rate-base expansion, the $250 bill stops looking like a mystery. Different regions feel different pressures. In some places the wholesale market dominates. In others the utility’s own capital plan and policy riders do most of the work. National averages hide those local realities.
I’ve come to believe the most useful way to look at the issue is not through a purely partisan lens. The drivers are structural: aging infrastructure, new sources of demand, regulatory incentives that reward capital spending, and market designs that can produce sharp price swings when supply and demand get tight. Politicians can influence the edges – how costs are allocated, how much policy is loaded onto bills, how aggressively returns are allowed – but the underlying pressures remain.
For households the practical steps stay familiar. Understanding the line items on your own bill helps. Comparing rates across nearby utilities or municipal systems, where possible, can reveal surprising differences. Timing high-use activities away from peak periods sometimes trims costs. Longer-term efficiency upgrades still matter. None of those steps solve the system-wide questions, yet they give individual families a bit more control while the larger debates continue.
The midterms may decide which set of officials inherit the next round of rate cases and capacity auctions. They will not erase the need for investment or the arrival of new large loads. The bill that arrives in the mailbox will keep reflecting those realities, with or without a few extra riders attached.
What feels different this cycle is the visibility. Electricity used to sit in the background of household budgets and political platforms. Now it sits near the front. That attention may eventually produce cleaner cost allocation, faster interconnection of needed generation, or clearer rules about who funds the next wave of grid expansion. Or it may simply produce more temporary freezes and credit programs that push the hard choices a few years further out. Either way, the underlying math is not going away.
The next time a $250 total appears, it will still be the product of generation costs, delivery investment, policy riders, and capacity market outcomes. Knowing which piece is moving the needle in your specific ZIP code remains the most practical starting point. The national averages and the campaign slogans will keep swirling. Your particular bill will keep telling its own more local story.
And that local story, repeated across millions of households, is what turned a monthly envelope into one of the defining economic issues of this election season. The numbers are real. The pressure is uneven. The path forward depends on whether policymakers treat the drivers as structural or temporary. For now, families continue opening the same piece of mail and asking the same question: why does this keep climbing?