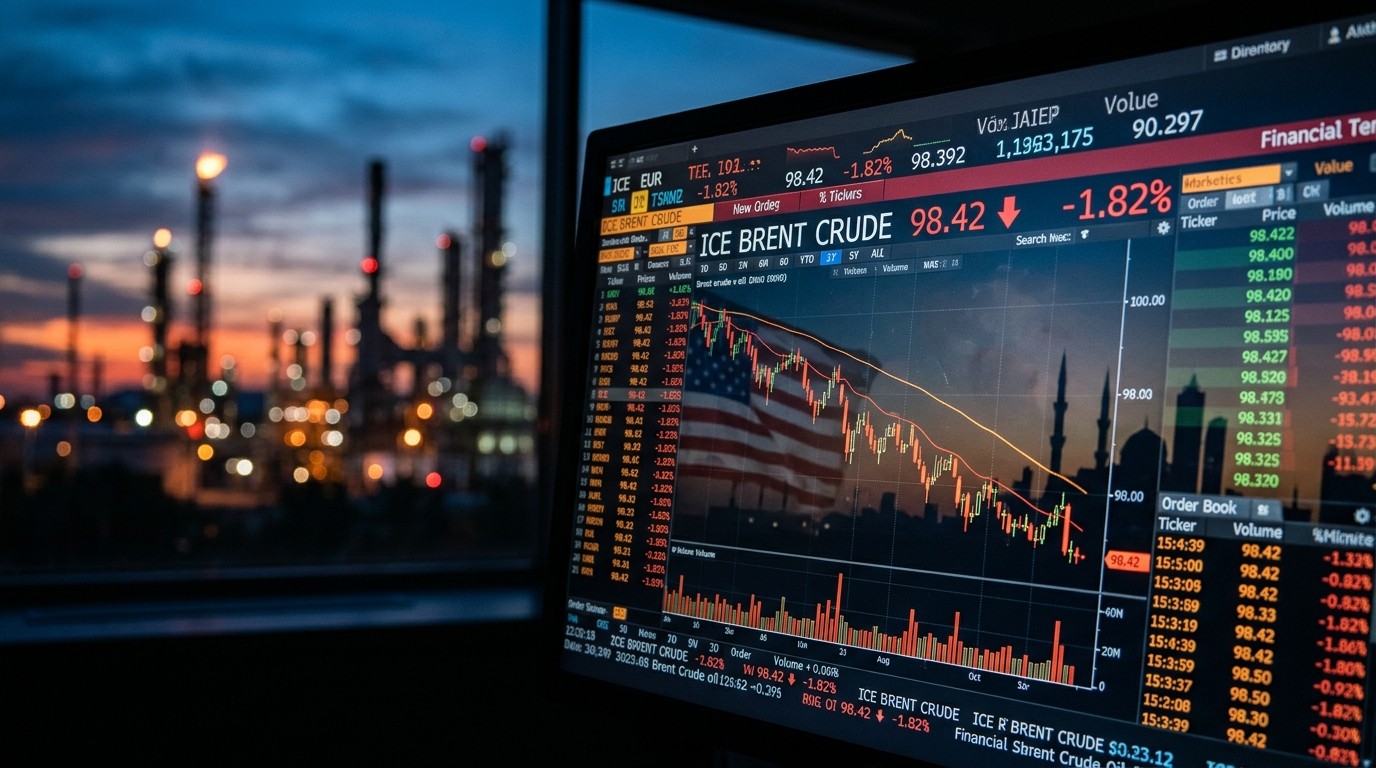

I was checking the overnight numbers this morning when something unusual jumped out. Brent crude had slipped under the psychologically important $100 level, and it wasn’t a slow drift. The move came fast, right after comments that tied recent election results directly to the ongoing conflict involving Iran. In my experience watching energy markets, that kind of political statement can shift sentiment quicker than any inventory report.
Oil Prices React Sharply To Political Fallout
The international benchmark finished the session more than four percent lower, settling near $99. Prices for the American grade followed almost in lockstep. What made the drop stand out was the context. Markets had spent weeks pricing in the possibility of further escalation. Now the tone has changed, and traders are recalculating the odds of prolonged supply disruptions.
Vice President JD Vance made the connection explicit. He stated that the conflict was the central reason for the party’s midterm setbacks. The president, according to the same remarks, had already acknowledged the same point the night before. That kind of open admission from the highest levels rarely leaves commodity markets untouched.
Why The Election Results Matter For Energy
Democrats took control of both chambers. That shift gives them meaningful leverage over foreign policy decisions in the months ahead. Higher fuel costs had become a daily talking point for voters. Gasoline and diesel prices stayed elevated for months because of disrupted shipping routes and reduced exports from the region. When households feel the pain at the pump every week, political consequences usually follow.
I’ve found that energy prices often act as a quiet referendum on policy. People may not follow every diplomatic detail, yet they notice when filling the tank costs noticeably more. The midterms appear to have confirmed that pattern once again. The new congressional balance increases pressure to pursue a quicker resolution rather than sustained military engagement.
The reason we lost is the war. The president himself said so last night.
Those words landed at a moment when oil futures were already looking vulnerable. Traders had piled into long positions during October on fears of wider disruption. Once senior figures on both sides began signaling openness to talks, the risk premium started to unwind. The result was a sharp two-day sell-off that erased a large part of the previous month’s gains.
How Markets Had Positioned For Escalation
Throughout October the market built a clear narrative. Every indication of possible further strikes pushed prices higher. By the end of the month Brent had climbed more than ten percent from its recent lows. Inventory draws and tighter tanker availability added fuel to the rally. Many participants treated the post-election period as a potential flashpoint.
That positioning left the market exposed once the political wind changed. When officials began discussing diplomatic paths more openly, the crowded long trade had to adjust. Selling accelerated as stop-loss orders triggered and momentum funds reduced exposure. The speed of the move under $100 surprised even some seasoned traders I spoke with.
Perhaps the most interesting aspect is how quickly the narrative flipped. Eight months of supply uncertainty had trained the market to react bullishly to any hint of tension. A single clear statement linking electoral defeat to the conflict was enough to reverse that reflex, at least for now.
The Role Of Diplomatic Signals
Both American and Iranian officials have indicated willingness to explore a settlement. That language alone does not guarantee progress, yet it reduces the probability of immediate large-scale escalation. For oil markets the distinction matters. Sustained conflict keeps a risk premium embedded in prices. Talks, even tentative ones, allow that premium to shrink.
Supply disruptions have already lasted longer than many expected. Shipping through key waterways remains constrained. Some producers have held back volumes out of caution. If negotiations gain traction, those constraints could ease. The market is beginning to price that possibility, which helps explain the recent softness.
- Reduced risk of sudden supply shocks
- Lower probability of additional sanctions or blockades
- Potential return of previously withheld barrels
- Improved tanker availability over time
None of these outcomes is certain. Diplomacy can stall. Yet the direction of travel has shifted enough to force a reappraisal of near-term balances.
Domestic Political Pressure And Fuel Costs
Gasoline and diesel prices became a persistent political liability. Families noticed the difference every time they filled up. Trucking companies passed higher costs along the supply chain. That cumulative effect showed up in polling and, ultimately, at the ballot box. The new congressional majority now has a clear incentive to push for measures that ease energy prices.
In my view this creates a feedback loop. Political pressure encourages diplomatic outreach. Signs of outreach cool the oil market. Lower prices then reduce the urgency for aggressive action. Whether that loop continues depends on how both sides respond in the coming weeks.
Traders are watching for any concrete steps. Statements alone can move prices for a day or two. Actual progress toward talks would have a more lasting effect. Conversely, any breakdown in communication could quickly restore the risk premium that has just begun to fade.
Technical Levels And Trader Psychology
The $100 mark on Brent has long served as a psychological pivot. Breaking below it on high volume often triggers additional selling from systematic strategies. Many funds use that level as a reference for risk management. Once price closed under it, further downside became more likely in the short term.
Support now sits in the mid-to-high $90s. A sustained hold above that zone would suggest the market is simply removing excess risk premium rather than pricing in a major demand or supply shock. A deeper break could open the door to a more substantial correction. Volume and open interest will provide the next clues.
I’ve noticed that energy markets often overshoot in both directions when geopolitics dominate the narrative. The October rally looked extended. The current pullback may prove equally sharp before finding equilibrium. Patience tends to reward those who avoid chasing either extreme.
Broader Implications For Global Energy Balances
Eight months of disruption have already altered trade flows. Some Asian buyers diversified sources. European refiners adjusted crude slates. Strategic stock releases in various countries helped bridge temporary gaps. If the conflict moves toward de-escalation, those adjustments may reverse, adding barrels back into the market at a time when demand growth is moderate.
Inventory data will become more important again. For months the market focused primarily on geopolitical headlines. As the political risk premium shrinks, traditional supply and demand metrics regain influence. Weekly draws or builds, refinery utilization rates, and OPEC+ compliance will matter more than they have recently.
| Factor | Recent Influence | Potential Shift |
| Geopolitical Risk | High | Moderating |
| Inventory Levels | Secondary | Primary again |
| Demand Outlook | Steady | Still key |
| OPEC+ Policy | Supportive | Watch closely |
The table captures the transition many analysts expect. Markets rarely stay in pure geopolitical mode forever. Eventually fundamentals reassert themselves. The current price action may mark the beginning of that shift.
What Traders Should Watch Next
Several developments will determine whether the decline continues or stabilizes. First, any concrete scheduling of talks would reinforce the softer tone. Second, comments from energy officials about restoring normal shipping patterns would help. Third, the pace of inventory builds or draws in major hubs will provide independent confirmation of physical market conditions.
Currency moves and equity market direction also play a role. A stronger dollar can pressure commodities, while risk-on equity sentiment sometimes supports oil through the growth channel. Right now the dominant driver remains the evolving political story.
- Monitor official statements for signs of negotiation progress
- Track physical differentials and freight rates for early clues
- Watch positioning data for evidence of further long liquidation
- Assess weekly inventory reports with renewed attention
- Stay alert for any sudden change in rhetoric from either side
These checkpoints should keep participants oriented as the situation evolves. Markets dislike uncertainty, yet they adapt quickly once a clearer path emerges.
A Personal Take On The Current Setup
Looking at the full picture, the sell-off feels more like a healthy correction of an overstretched risk premium than the start of a prolonged bear market. Global demand has not collapsed. Major producers continue to manage supply carefully. The main change is the reduced probability of a sudden, large-scale disruption.
That said, energy markets rarely move in straight lines. Any setback in diplomatic efforts could reverse recent gains in sentiment within hours. The smart approach, in my experience, is to respect the new political reality while remaining prepared for volatility. Positioning lightly and focusing on clear technical levels has served many traders well during similar transitions.
The midterms delivered a clear message about the cost of prolonged conflict. Markets are translating that message into lower prices for now. How long the relief lasts will depend on whether words turn into actual progress at the negotiating table. For the moment, Brent below $100 stands as the most visible sign that the political and energy landscapes are shifting together.
The coming weeks will test whether this price adjustment marks a lasting change in market psychology or simply a pause before the next geopolitical headline. Either way, the link between electoral outcomes and oil prices has rarely felt more direct. Investors who understand that connection will be better positioned to navigate whatever comes next.
Fuel costs influence more than household budgets. They shape political fortunes, trade flows, and the daily decisions of refiners and shippers across the globe. When those costs become a central campaign issue, the market eventually responds. This week’s sharp decline shows just how quickly that response can arrive once the political winds change direction.
As the new congressional balance takes shape, the pressure to resolve the underlying conflict is likely to grow rather than diminish. That reality is already visible in the futures curve. Whether it leads to genuine de-escalation remains an open question, yet the market is no longer pricing the most aggressive scenarios with the same conviction it showed only days ago.
For those who follow energy closely, the lesson is familiar. Geopolitics can dominate price action for months, but it rarely does so indefinitely. Eventually politics and fundamentals meet. The drop below $100 may be the first clear signal that the meeting has begun.