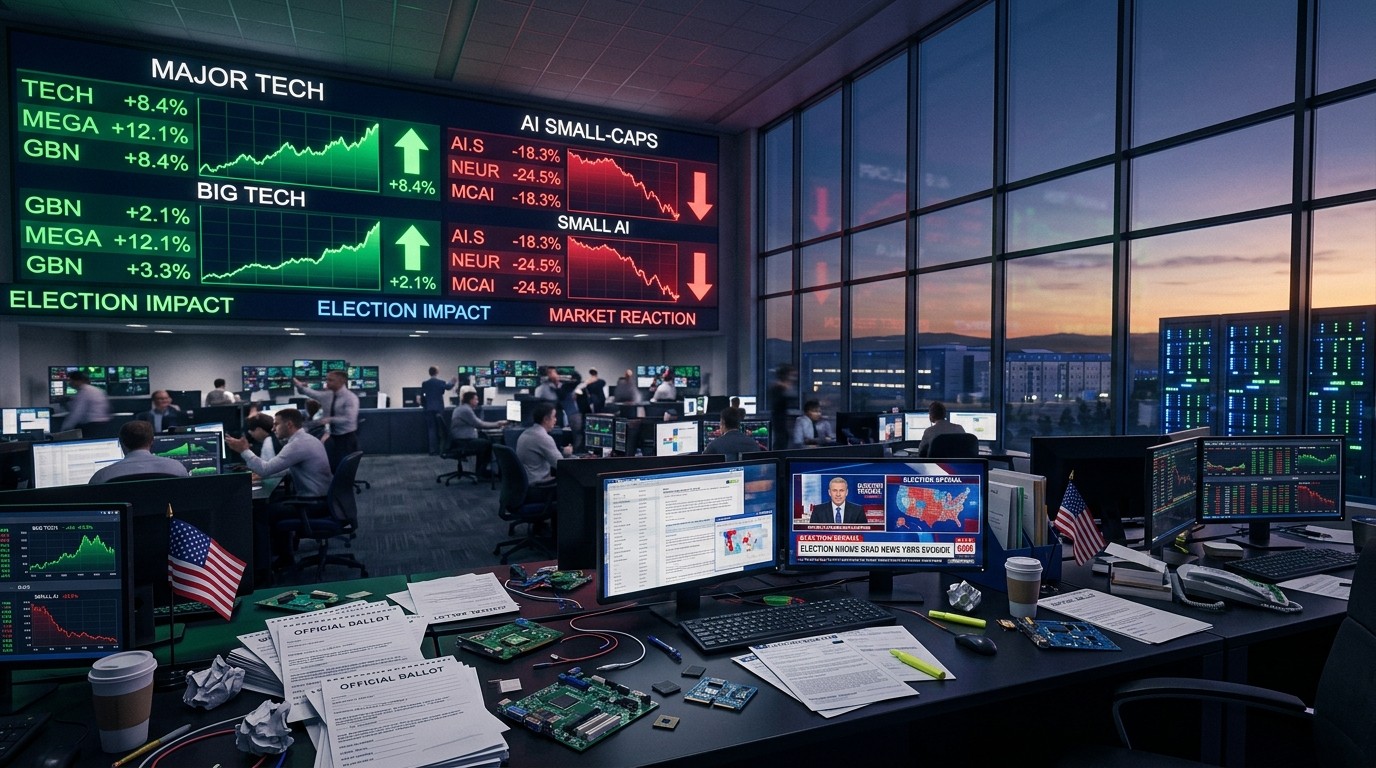

I was watching the market open on Wednesday and something felt off right away. The major indexes were climbing after the midterm results came in, yet a clear divide was forming inside the AI space. Some names were ripping higher while others were getting hit hard. It made me stop and ask myself who really stands to benefit from this new political landscape.
Understanding The Sudden Split In AI Stocks
The overall market mood was positive. Investors seemed relieved by the election outcome in several key races. But dig a little deeper and you notice the AI trade is no longer moving as one big group. The companies already sitting on massive computing capacity saw strong gains. The newer, more aggressive builders of data centers took a beating. That contrast tells a bigger story about how capital might flow from here.
In my view this reaction makes sense once you look at the policy signals. Certain states that have become magnets for data center construction elected leaders more open to tighter rules on new projects. Local ballot measures also passed in various places that could slow future builds. None of this ends the need for more computing power, of course. Demand for AI capacity remains intense. The question is simply who gets to supply it and under what conditions.
Why Established Cloud Giants Look Stronger Now
The big cloud providers already own large footprints and enjoy steady customer demand for the capacity they have. When financing for brand-new projects becomes harder, these incumbents can lean on what they already built. Their cash flows have been under pressure from heavy spending, so any slowdown in the pace of new construction could actually help free up money. Investors noticed that right away.
Shares of the largest names in cloud computing moved higher in a noticeable way. One climbed about seven percent. Another added more than six percent. A third advanced nearly four percent. These moves stood out against the broader market because they reflected a shift in expectations around spending discipline. The market appears to believe that external pressure will force these companies to be more careful with capital, and that discipline is being treated as a positive.
The demand for AI compute is not disappearing, but future spending may moderate and allow cash flows to rebound.
I have followed these companies for years and this pattern feels familiar. When the cost of capital rises or political hurdles appear, the players with the strongest balance sheets and existing assets tend to pull ahead. The newer entrants often struggle to secure the same level of funding. That dynamic seems to be playing out again.
The Pressure On Newer Computing Providers
On the other side of the trade sit the smaller, more speculative computing providers. These firms have grown quickly by leasing or building capacity aimed at AI workloads. Many carry higher debt loads and depend on continued access to capital markets. When the political environment turns less friendly toward rapid expansion, their path becomes steeper.
One of the better-known names in this group dropped almost ten percent. Another fell eleven percent. A third declined around six and a half percent. These moves added to already significant pullbacks from earlier highs this year. The market is clearly questioning how easily these companies will raise the money needed for their next wave of projects.
Perhaps the most interesting aspect is how quickly investors reassessed risk. Only days earlier some of these stocks were still trading on pure growth expectations. Overnight the focus shifted to balance sheet strength and political exposure. That kind of rapid change in narrative is common in markets, yet it still catches many people off guard.
Infrastructure Suppliers Feel The Ripple Effects
It is not only the computing providers that moved. Companies supplying electrical equipment and power generation equipment also saw sharp declines. One major electrical equipment maker dropped nine percent and erased a previous post-earnings gain. Another large player in gas turbines and power solutions fell about ten percent even after reporting solid results and a healthy backlog.
These suppliers had been pricing in strong ongoing demand from the data center boom. Any hint that the pace of new construction might slow creates immediate pressure on their shares. Existing backlogs should still convert into revenue because underlying electricity needs continue to grow. Still, the near-term valuation reset has been real.
In my experience, markets often overreact to policy shifts in both directions. The same names that get punished when risk is highlighted can rebound once investors realize that demand itself has not vanished. The buildout will likely continue, just under different constraints and timelines.
Semiconductor Names Under Pressure Too
Chipmakers and related suppliers also felt the weight of the new uncertainty. Several semiconductor stocks declined between three and eight percent. Even the largest and most valuable chip designer gave back about one percent. A materials supplier that reported strong numbers earlier in the day traded slightly lower.
Memory pricing has been a particular concern for some consumer electronics companies. Higher costs for DRAM have squeezed margins and forced price increases on finished products. If the data center buildout slows even modestly, some of that pricing pressure could ease. One major device maker jumped six percent on that possibility, which felt like a classic relief move.
I keep coming back to the idea that the AI story remains intact at its core. The need for more computing power is driven by real customer demand, not just political enthusiasm. What changes is the ease of financing and the speed of new capacity additions. That distinction matters a great deal for stock selection going forward.
What Financing Challenges Could Look Like
Think about how difficult it became to finance certain energy infrastructure projects under previous administrations. Similar headwinds could now appear for data centers in key states. Banks and private lenders grow more cautious when the regulatory path looks uncertain. The companies that already have cash or strong credit ratings will still find money. The ones that rely on continuous capital raises may struggle.
This does not mean the data center story is over. Far from it. Existing projects and signed contracts should move forward. The marginal new facility, however, faces a higher bar. That shift favors the larger players who can self-fund more of their growth and who already control significant capacity that customers need right now.
- Strong existing footprints reduce the need for rapid new builds
- Healthier balance sheets provide flexibility when capital markets tighten
- Customer relationships already in place support utilization rates
- Potential for improved free cash flow if spending slows
These advantages are hard to ignore. The market is pricing them in quickly, which is why the divergence between groups has been so sharp.
How Investors Are Reassessing Risk
Every election cycle brings its own set of winners and losers in the equity market. This time the AI complex is front and center. Analysts covering energy infrastructure names noted that near-term winners and losers will become clearer as investors reassess policy exposure. At the same time they pointed out that underlying demand growth should still support existing projects.
That balanced view feels right to me. Markets love to swing from extreme optimism to extreme caution in short periods. The data center buildout has been one of the most powerful investment themes of the past two years. Any political friction was bound to create volatility. The key is separating temporary financing noise from the longer-term structural need for more computing power.
I have found that the best approach in these moments is to focus on balance sheet quality and current cash generation rather than pure growth narratives. The companies that can weather a period of tighter capital access will still be around when the next wave of demand arrives. The ones that cannot may face dilution or slower expansion.
The Role Of Power And Grid Constraints
Data centers do not run on hope. They need reliable electricity in large quantities. The same political forces that may slow new construction could also affect power plant approvals and transmission projects. That adds another layer of complexity. Companies that already secured long-term power agreements or that own generation assets sit in a stronger position.
Gas turbine manufacturers had been benefiting from the surge in electricity demand tied to AI. Their order books grew as utilities and private developers raced to add capacity. Any slowdown in data center announcements could eventually show up in new orders, even if current backlogs remain solid. That risk is now being discounted in share prices.
Still, the physics of the situation have not changed. Training large models and running inference at scale requires enormous amounts of energy. The industry will find ways to meet that need. The path simply may involve more creativity around location, efficiency, and financing structures.
Looking At Cash Flow And Spending Discipline
One of the quieter but important themes on Wednesday was the idea of spending discipline. The largest cloud companies have poured tens of billions into new capacity. That spending has weighed on free cash flow metrics that many investors watch closely. If the political environment forces a more measured approach, those cash flow numbers could improve sooner than previously expected.
Investors appear to welcome that possibility. Higher share prices for the big incumbents suggest the market is willing to trade some growth for better capital returns. That trade-off is not always popular in a pure growth sector, yet it often proves healthy over longer periods.
For the smaller players the story is different. Their valuation multiples have depended on the assumption of rapid capacity expansion funded by debt and equity raises. When that assumption faces questions, multiples compress quickly. We saw that compression in real time on Wednesday.
Possible Paths Forward For The Buildout
The data center story will not disappear. Customer demand for AI services continues to grow across industries. What changes is the geography and the financing model. Projects may concentrate more heavily in states that remain supportive. Developers may lean more on joint ventures or pre-leased facilities that reduce risk for lenders.
Some capacity could shift toward existing industrial sites or areas with surplus power. Efficiency gains in chips and cooling systems may also stretch current facilities further than previously assumed. All of these adjustments take time, which is why near-term stock moves can look dramatic.
- Focus on companies with strong existing capacity and customer contracts
- Watch balance sheet strength and access to capital markets
- Monitor policy developments in key data center states
- Track power availability and grid upgrade progress
- Reassess pure growth names that depend on continuous external funding
These steps form a practical framework for navigating the current environment. Markets will keep adjusting as more details emerge about specific projects and financing outcomes.
Why The Market May Be Overreacting In Both Directions
Short-term swings are normal after major political events. Investors often price in the most extreme outcomes first and then moderate their views as reality sets in. The AI buildout has real economic drivers behind it. Those drivers do not vanish because of a few election results. At the same time the political risk is genuine and deserves attention.
The companies that already dominate cloud computing have room to benefit from any slowdown in competitive capacity additions. Their utilization rates could stay high and their capital intensity might ease. The newer providers face a tougher road but are not necessarily finished. Some will adapt, secure alternative funding, or find niche opportunities.
I tend to view these moments as opportunities to refine rather than abandon a thesis. The AI infrastructure theme remains one of the most important multi-year stories in the market. The list of winners simply needs updating based on the new constraints.
Balancing Growth Expectations With Reality
Growth stocks always carry the risk of disappointment when external conditions shift. The past few years delivered an almost uninterrupted narrative of accelerating data center construction. Any interruption, even a modest one, creates volatility. That volatility is painful for those who bought at the highs, yet it also creates clearer entry points for patient capital.
The larger cloud providers now look more defensive within the AI complex. Their size and diversification offer a buffer. The pure-play computing providers and some of their suppliers look more cyclical and more sensitive to financing conditions. Understanding that difference is essential for portfolio construction right now.
Memory pricing trends will also matter. If the intensity of data center demand eases even slightly, some of the extreme cost pressure on other industries could moderate. That secondary effect already showed up in one major consumer electronics name that bounced higher on the idea of potential relief.
Longer Term Implications For The Sector
Over a multi-year horizon the need for more computing power is unlikely to reverse. Artificial intelligence applications continue to expand into new industries and use cases. The constraint has always been capital, power, and skilled labor more than pure technological possibility. Political factors simply add another variable to the equation.
Companies that navigate the current environment carefully will emerge stronger. Those that overextend themselves on the assumption of easy capital may face difficult choices. Investors who stay focused on fundamentals rather than daily price swings will be better positioned to take advantage of the eventual clearing of the fog.
The market delivered a clear message on Wednesday. Not every AI-related stock is the same. Balance sheet strength, existing capacity, and political exposure now matter more than they did a few months ago. That message is worth taking seriously.
Practical Takeaways For Portfolio Decisions
When I step back from the daily noise a few points stand out. First, the broad market rally after the midterms masked important divergences inside the AI complex. Second, the incumbents with scale appear better positioned for a period of tighter capital access. Third, the more speculative names face real challenges that could take time to resolve.
Existing backlogs in power equipment and electrical infrastructure should still convert into sales. Customer demand for cloud computing and AI services has not disappeared. The pace of new capacity additions may slow, and that change will affect different companies in different ways.
Perhaps the most useful mindset is one of selective optimism. The AI theme remains powerful. The way capital is allocated inside that theme is evolving. Staying flexible and focusing on quality will matter more than ever in the months ahead.
Markets rarely get the full picture right on the first day after a major event. The initial reaction on Wednesday highlighted real risks and real opportunities. Sorting through them carefully is the task now facing investors who want to stay involved in one of the most important technology shifts of our time.
The data center buildout will continue in some form. It may simply look different than the rapid, debt-fueled expansion many had assumed. That adjustment process is already underway in share prices, and it is likely to continue as more details about policy and financing become clear.
In the end the companies that can deliver capacity efficiently, fund it responsibly, and navigate the new political realities will be the ones that reward patient shareholders. The rest of the complex will face a tougher road. Watching that separation play out should keep markets interesting for some time to come.