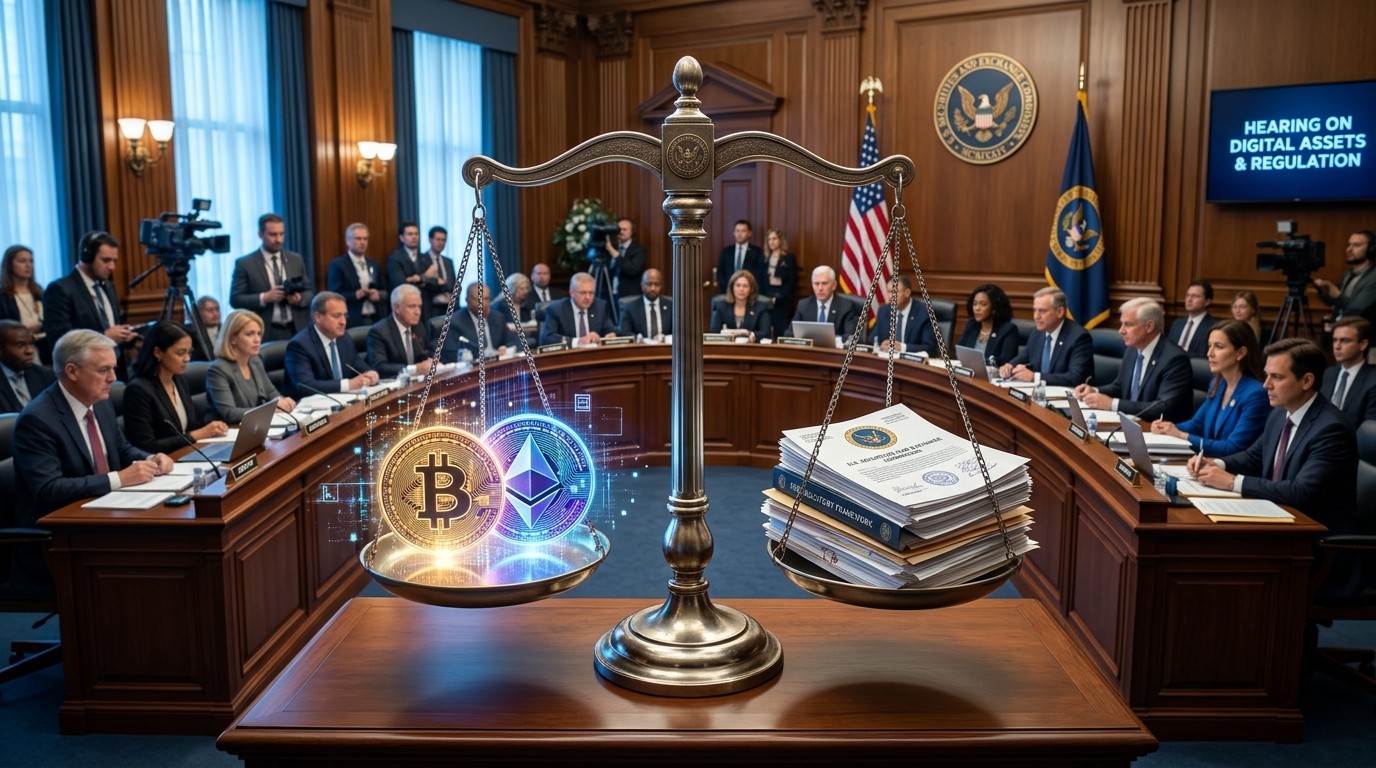

I’ve been watching the crypto space long enough to know that regulation rarely moves in a straight line. Just when it seems the conversation has settled, something new surfaces and the whole debate restarts. Right now, talks around a potential crypto market structure bill are putting the Securities and Exchange Commission’s role back at the center of attention, and the timing feels deliberate.
After months of stalled progress on earlier legislative efforts, House Democrats are reportedly exploring ideas for the next Congress. The focus appears to be a broader proposal that would expand certain investor protections and adjust how regulatory authority is divided. In my view, this shift matters more than many people realize because it could reshape the balance between agencies and change what retail participants can expect from platforms that hold their assets.
Why SEC Oversight Is Returning To The Spotlight
The current discussions build on earlier Democratic proposals that never made it through the process. One key element involves giving the Securities and Exchange Commission a larger supervisory role while limiting the reach of the Commodity Futures Trading Commission in certain digital asset markets. That idea alone is enough to spark strong reactions on both sides of the industry.
Previous frameworks leaned toward treating many spot digital commodity markets under the CFTC. The newer conversations seem to reverse some of that emphasis. I’ve found that these kinds of adjustments often reflect deeper disagreements about whether digital assets behave more like securities or commodities in everyday trading.
Ethics rules also form part of the conversation. Lawmakers are looking at restrictions that would apply to certain federal officials and their families regarding crypto-related financial interests. The goal, at least on paper, is to reduce potential conflicts. Whether those rules survive the full legislative process remains an open question, but their reappearance signals that the issue has not gone away.
Building On Earlier Investor Protection Ideas
Much of the new discussion draws from a package of investor and consumer protections that was offered as an amendment during earlier consideration of market structure legislation. That package never received a full floor vote, yet its core ideas continue to circulate among staffers and industry contacts.
The proposals covered a range of practical concerns that everyday users often raise. Platforms would need to process cash withdrawals or digital asset transfers within a strict timeframe, usually 24 hours, unless a documented fraud concern existed. Continuous human customer support, either by phone or live chat, would become a requirement, with limits on wait times.
Another important piece involved the treatment of customer assets. Those assets would have to sit in bankruptcy-remote accounts. Lending, staking, or any form of reuse would require clear affirmative consent that customers could later revoke. Monthly publication of cryptographically verifiable reserves, backed by an independent accountant’s attestation, also featured in the earlier text.
In my experience, these kinds of operational rules matter more to retail participants than high-level debates about which agency has primary jurisdiction. When something goes wrong, people want clear timelines, accessible support, and confidence that their holdings are not mixed with the company’s own balance sheet.
How The Regulatory Balance Could Shift
The Republican-backed approach that advanced earlier favored a clearer division of labor. The CFTC would oversee covered spot digital commodity markets, while the SEC retained authority over securities and investment contracts. Registration pathways for exchanges, brokers, and dealers formed a central part of that framework.
The Democratic discussions now underway appear to tilt more authority toward the SEC. A more limited remit for the CFTC is part of the reported thinking. That change would not simply move paper jurisdiction; it would influence the style of supervision, the types of disclosures required, and the enforcement posture that platforms face.
I’ve noticed that industry participants often prefer the CFTC’s approach for certain markets because they view it as more principles-based. Others argue that the SEC’s experience with retail investor protection makes it better suited for platforms that serve everyday customers. Both perspectives have merit, which is why the debate keeps returning.
Ethics Rules And Potential Conflicts Of Interest
One of the more politically charged elements involves ethics provisions. Earlier negotiations already included requirements for certain covered officials to divest substantial crypto-related interests or place them in a blind trust. Those rules would apply to federally elected officials, federal judges, and their spouses in some versions of the text.
Democrats have continued to push for stronger restrictions. The latest conversations suggest that ethics language would return to the drafting process. Separate proposals have targeted specific activities such as presidential token ownership, public endorsements, and personal trading by high-level officials and their immediate families.
These provisions sit at the intersection of policy and politics. Supporters see them as necessary safeguards against the appearance of self-dealing. Critics sometimes view them as overly broad or difficult to administer. Either way, their reintroduction keeps the issue alive and forces negotiators to address it rather than set it aside.
What The Earlier Investor Package Actually Contained
Looking more closely at the nine-page amendment text that circulated previously reveals a set of concrete operational standards. Covered businesses would include exchanges, brokers, dealers, and custodians under either agency’s jurisdiction that provide digital asset services to retail customers.
Key requirements included:
- Honoring cash withdrawals or digital asset transfers within 24 hours except in documented fraud cases
- Providing continuous human telephone or live-chat support with connection waits capped at five minutes
- Segregating customer assets in bankruptcy-remote accounts
- Obtaining affirmative, revocable consent before any lending, staking, or reuse of customer assets
- Publishing cryptographically verifiable reserves at least monthly with an independent accountant’s attestation
- Notifying customers within 48 hours of discovering a security breach that compromises assets or personal information
Additional elements addressed front-running concerns, fiduciary duties, best-execution standards, and insurance or protection comparable to existing securities investor safeguards. Funding for both the SEC and CFTC also appeared in the package.
These details matter because they move the conversation from abstract jurisdictional debates to the daily experience of people using trading platforms. A 24-hour withdrawal rule, for example, sounds simple until a platform faces liquidity pressure or technical issues. Monthly proof-of-reserves reporting sounds straightforward until questions arise about the quality of the attestation or the scope of assets covered.
Why Earlier Efforts Fell Short
The path to a comprehensive market structure bill has been difficult. A procedural vote in the Senate earlier in the process failed to reach the threshold needed to begin formal consideration. The margin was narrow, and one senator changed position for procedural reasons that left open the possibility of reconsideration later.
That outcome did not kill the underlying House-passed legislation, but it did pause momentum. Afterward, some former regulators suggested that the agencies could continue developing digital asset frameworks under their existing authorities even without new legislation. That path remains available, yet many participants prefer clear statutory language over case-by-case agency action.
The House Rules Committee previously declined to make the investor protection amendment eligible for floor consideration. The vote focused on procedure rather than the substance of a standalone bill. Still, the ideas themselves continue to influence staff discussions, which is why they are resurfacing now.
What A Messaging Bill Could Achieve
Some Republican voices have described the current Democratic effort as a messaging bill. That label carries a certain weight in legislative circles. It suggests the proposal may be designed more to highlight differences and stake out positions than to pass in its current form.
Even so, messaging exercises can shape future negotiations. They force the other side to respond, clarify priorities, and sometimes incorporate selected ideas into later compromise texts. I’ve seen this pattern play out in other areas of financial regulation. What begins as a messaging vehicle sometimes seeds the next round of serious talks.
The allocation of regulatory authority remains the core tension. One side prefers a stronger SEC role and tighter consumer-facing rules. The other side favors clearer CFTC oversight of commodity-style markets and a lighter overall framework. Bridging that gap has proven difficult, which is why the issue keeps returning in slightly different packaging.
Practical Implications For Platforms And Users
If a bill incorporating stronger investor protections eventually advanced, platforms would face new operational requirements. Continuous customer support, strict withdrawal timelines, and regular reserve reporting would require systems and staffing that not every firm currently maintains. Smaller operators might find compliance more burdensome than larger, established players.
For retail users, the upside would include clearer rights and more predictable processes. Knowing that assets sit in segregated accounts and that withdrawals should clear within a set window can reduce anxiety during periods of market stress. Monthly proof-of-reserves reports, if implemented carefully, could also improve transparency.
Of course, rules on paper only help if they are enforced consistently. Agencies would need resources and clear statutory direction. The earlier package included funding provisions for both the SEC and CFTC, recognizing that expanded responsibilities require expanded capacity.
The Broader Context Of Digital Asset Regulation
This latest round of discussions sits inside a larger story about how the United States approaches digital assets. Other jurisdictions have moved forward with licensing regimes, stablecoin frameworks, and clearer definitions. The United States has progressed in some areas through agency action and targeted legislation, yet a comprehensive market structure law has remained elusive.
Perhaps the most interesting aspect is how persistent the core questions remain. Is a given token a security or a commodity? Which agency should write the primary rules for spot trading platforms? What minimum standards should apply to the custody of customer assets? These questions have been debated for years, and the answers still shape every new legislative draft.
I’ve found that progress often comes in increments rather than dramatic breakthroughs. Negotiators incorporate selected ideas from previous drafts, adjust language to address specific concerns, and test new procedural pathways. The current Democratic discussions fit that pattern. They take earlier rejected language, expand it into a fuller market structure concept, and prepare it for a different congressional calendar.
Looking Ahead To The Next Congress
Nothing is settled yet. Staff-level conversations do not equal committee markups or floor votes. Still, the fact that these talks are happening indicates that market structure remains a live issue rather than a closed chapter.
The next Congress will bring its own political dynamics. Leadership priorities, committee assignments, and the overall legislative calendar will all influence what can realistically advance. A proposal that expands SEC authority and tightens ethics rules will face different reception depending on the composition of both chambers.
In the meantime, platforms continue operating under the existing mix of agency guidance, enforcement actions, and state-level requirements. That patchwork creates compliance complexity and leaves some questions unresolved. Clearer federal legislation would reduce uncertainty, yet the content of that legislation matters as much as its mere existence.
Retail participants, for their part, continue to trade, hold, and transfer digital assets while watching the regulatory conversation from the sidelines. Their practical concerns—access to funds, safety of custody, quality of customer service—tend to align more closely with the operational rules than with abstract jurisdictional fights. That reality may explain why investor protection language keeps reappearing even after procedural setbacks.
Balancing Innovation And Protection
Any serious market structure effort must navigate a familiar tension. Too little oversight can leave customers exposed during periods of stress or misconduct. Too much or poorly designed oversight can raise costs, slow product development, and push activity offshore. Finding the middle ground has proven harder than writing either extreme position.
The Democratic discussions appear to emphasize the protection side of that balance. Expanded SEC supervision, stricter ethics rules, and detailed operational standards all point in that direction. Supporters argue these measures are overdue. Critics worry they could chill legitimate activity or create overlapping requirements that are difficult to navigate.
In my view, the most useful legislation would combine clear jurisdictional lines with practical, enforceable standards that address real risks without freezing the market. Monthly reserve reporting, segregation of customer assets, and reasonable withdrawal timelines strike me as sensible baseline expectations. The harder questions involve how far fiduciary duties should extend and how aggressively agencies should police the boundary between securities and commodities.
What Industry Voices Are Watching
Market participants are paying close attention to several signals. First, the relative weight given to the SEC versus the CFTC will shape compliance strategies for years. Second, the treatment of customer assets and withdrawal rights will affect platform design and operational readiness. Third, ethics provisions could influence who participates in the sector and under what constraints.
Beyond those headline issues, quieter details often matter more in practice. Definitions of covered entities, the scope of retail customer protections, the precise content of proof-of-reserves attestations, and the interaction with existing state regimes all influence day-to-day operations. Legislation that leaves those details vague can create as many questions as it answers.
I’ve observed that the most constructive conversations focus less on abstract philosophy and more on specific operational outcomes. What happens when a customer requests a withdrawal during a period of high volume? How quickly must a platform notify users of a security incident? What level of independent verification accompanies a public reserves report? Answering those questions clearly helps everyone plan.
The Road Still Ahead
For now, the discussions remain exploratory. Multiple industry sources have described conversations between Democratic staffers and market participants about expanding earlier investor protection language into a fuller market structure proposal. Those talks do not guarantee introduction of a bill, let alone passage. They do indicate that the underlying issues retain political attention.
Previous legislative efforts incorporated dozens of substantive changes requested during negotiations. That history shows that compromise is possible when both sides engage. Whether the next round of talks produces a similar willingness to adjust remains to be seen. The reappearance of ethics language and a stronger SEC role suggests the starting points may still sit some distance apart.
In the absence of new legislation, agencies continue to use the tools they already possess. Enforcement actions, interpretive guidance, and registration pathways under existing statutes still shape behavior. Some former regulators have argued that this path can deliver meaningful frameworks even without a comprehensive statute. Others maintain that only clear congressional direction can resolve long-standing jurisdictional uncertainties.
The coming months will reveal whether the current conversations evolve into formal proposals or remain at the level of staff exploration. Either way, the core questions about oversight, investor protection, and potential conflicts of interest are unlikely to disappear. They form part of the unfinished business of digital asset regulation in the United States.
For anyone following this space, the practical takeaway is straightforward. Market structure remains unsettled. The balance between agencies is still contested. Investor-facing operational rules continue to surface as a priority for some lawmakers. And ethics considerations involving public officials keep returning to the table. Those four themes will likely shape the next chapter of the legislative effort, whenever that chapter is written.
I’ve learned to treat early reports of staff discussions with a mix of interest and caution. They often preview the issues that will dominate later debates, yet they can also fade if political attention shifts. In this case, the combination of expanded SEC oversight ideas, revived investor protection language, and ethics provisions feels substantive enough to watch closely. The details that eventually emerge, if any, will tell us more about the direction of U.S. crypto policy than any single headline.
Until then, platforms will keep operating, users will keep trading, and the regulatory conversation will keep evolving in the background. The real test will come when formal legislative text appears and both sides must decide how far they are willing to move. That moment has not arrived yet. When it does, the earlier debates summarized here will provide useful context for understanding the choices on the table.