
Remember that feeling two years ago when everything seemed to hinge on the price of eggs and the fill-up at the pump? A lot of people bet their votes on the idea that one leader could fix the squeeze at the kitchen table. Fast forward to this week and those same voters just turned the tables in a way few predicted. The 2026 midterms delivered a blue wave that left many watching in disbelief as long-held ground shifted under the weight of everyday money worries and a distant conflict that hit home hard.
How Economic Frustration Flipped the Political Script
It started with a simple question that once worked wonders on the campaign trail. Are you better off than you were four years ago? Back then the answer felt clear enough for many. Inflation was the villain, and the message landed. This time the same kitchen-table issues came back with a vengeance. Voters looked around and decided the status quo no longer served them.
Nearly nine out of ten people in a major voter survey called the cost of living a crucial or major factor when they cast ballots for Congress. The economy ranked as the top issue, beating out concerns about democracy and immigration. Three-quarters of those surveyed rated the economy as poor or not so good. Only a tiny fraction called it excellent. Fewer than one in five said their family finances looked better than two years earlier. That kind of numbers tells a story of quiet anger that finally found an outlet at the polls.
I’ve watched these cycles long enough to know that pocketbook pain rarely stays quiet for long. When prices keep climbing while paychecks lag, people notice. They talk about it at dinner. They notice it every time they swipe a card at the grocery store. And eventually they vote on it. This time the dissatisfaction focused squarely on policies that many felt made things worse rather than better.
The Breaking Point at the Pump and Beyond
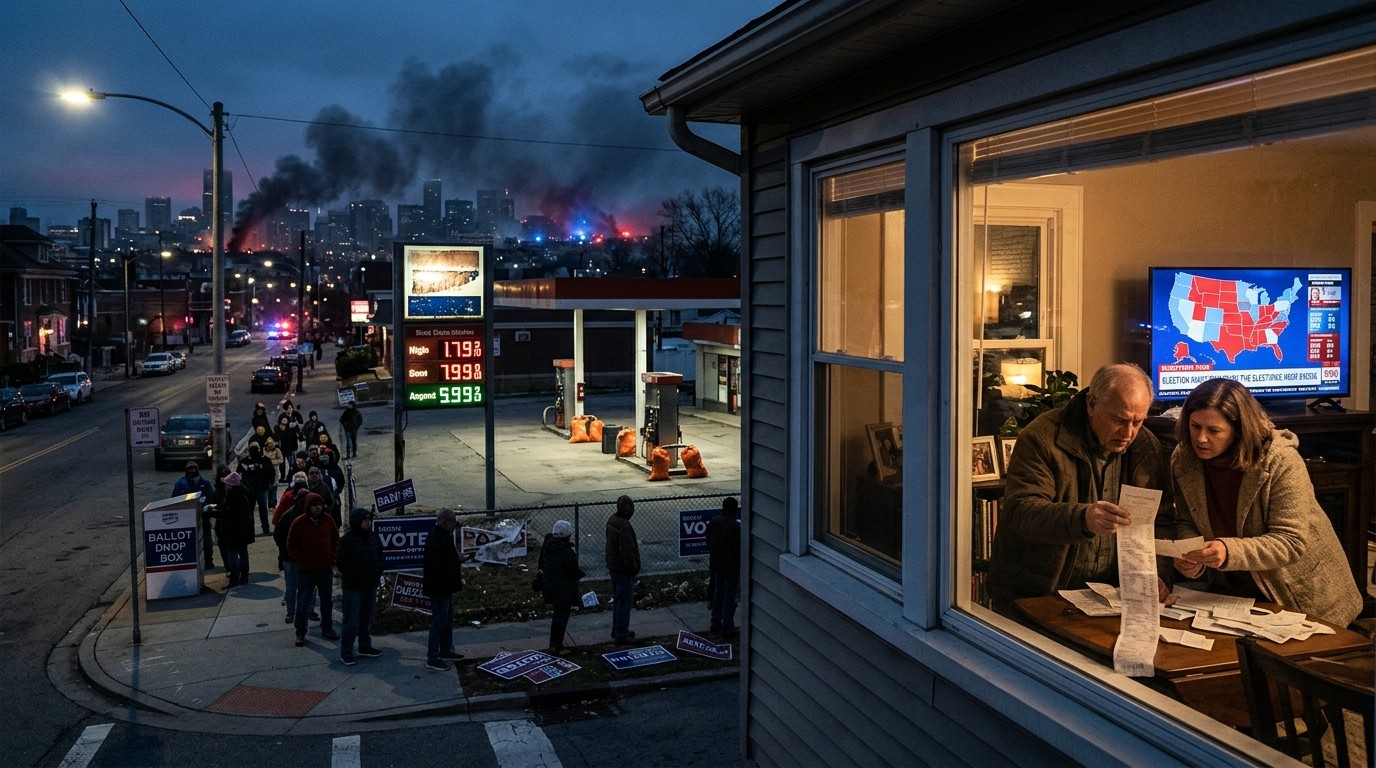
Gas prices painted the clearest picture. On election day drivers paid about $4.15 a gallon on average, the highest for any midterm or presidential voting day since at least 2000. That number jumped roughly 37 percent over the past year as conflict in the Middle East disrupted global oil flows. The financial hit added up fast. One analysis put the extra cost to the average household near $1,230 just from higher energy prices since the conflict began. Borrowing costs and other related expenses pushed the total burden past $900 more for many families.
Diesel prices climbed into territory that transportation leaders called almost unreal. Those higher costs worked their way into the prices of goods moved by trucks and trains. The broad measure of consumer prices reaccelerated during the conflict. Wage gains failed to keep pace, leaving less real purchasing power in people’s hands. More than three out of five survey respondents believed certain policies led to higher prices overall. Almost nine out of ten expressed concern about utilities, food, and oil costs.
Most Americans are struggling with the high inflation and have been for quite some time, and they’re just angry.
Consumer sentiment surveys painted an even darker mood. One long-running measure of how people feel about the economy dropped to its worst levels in seven decades. Another confidence gauge hit 14-year lows in the weeks before the vote. When people feel the squeeze that deeply, the desire for change grows. A professor who studies behavioral economics put it plainly. Inflation pushed voters to a breaking point. Angry consumers become voters who push against the current leadership.
War Abroad and Pressure at Home
The conflict with Iran that began in late February sat in the background of every conversation about prices. Nearly three out of four voters called the war a crucial or major factor in their congressional choice. Some acknowledged the reasons for military action yet still felt the pain at the pump. Higher fuel costs became the tangible reminder every time someone filled a tank. The message from the road was unmistakable. Going into an election with prices never seen higher on voting day creates frustration that no amount of messaging can fully erase.
That frustration spilled into other areas of daily life. Rising energy costs and the broader economic drag left many households calculating every purchase. The same voters who once believed a particular approach would ease the burden now looked for alternatives. In my view the connection between distant conflict and local grocery bills became impossible to ignore. When the numbers hit the dinner table conversation, the political impact follows.
Policies That Missed the Mark for Many
Before the conflict even started, warnings about certain economic approaches had already circulated among economists and policymakers. Broad and steep tariffs were presented as a path to stronger domestic manufacturing. Markets reacted with volatility and talk of possible recession risks. Research suggested that many consumer prices would have moved lower without those measures. In the voter survey, 64 percent said the tariff approach hurt the economy in their area. Only 14 percent saw a benefit.
Immigration enforcement steps in major cities also drew mixed reactions. Large-scale actions led to protests and, in some cases, tragic outcomes. Studies pointed to reduced foot traffic and billions in lost consumer spending in affected areas. About three out of five voters disapproved of how certain agencies handled their work and felt the administration had gone too far. Interestingly, many still viewed one party as stronger on the immigration issue overall. The tension between those views showed up in the results.
Not every measure drew criticism. Average tax refunds grew by 11 percent after one major legislative package. New accounts designed to help parents build savings for children received some positive notice. Yet on election day affordability remained the dominant concern. The difference from two years earlier was clear. Voters now saw the opposing party as better equipped to handle the economy. Seven out of ten respondents felt the economic system generally favored the wealthy. That sense of uneven ground added another layer to the desire for change.
What the Numbers Revealed About Voter Mood
The scale of the shift surprised many observers. Battleground congressional seats flipped. Governorships long considered secure changed hands. Control of both chambers of Congress moved in a single night. The trifecta of power that once seemed solid ended abruptly. Behind the headlines sat the quiet data from those voter conversations. Cost of living dominated. Economic ratings stayed low. Personal financial standing rarely improved. Policy satisfaction lagged.
- Nearly nine in ten ranked cost of living as crucial or major
- Three-quarters called the economy poor or not so good
- Fewer than one in five reported better family finances than two years prior
- About two-thirds said certain policies worsened economic conditions
- Nearly three-quarters called the conflict a major voting factor
Those figures do not appear in isolation. They reflect months of rising diesel costs feeding into broader price indexes. They reflect household budgets stretched by energy bills that refused to ease. They reflect a consumer mood that hit historic lows even as some official indicators told a different story. The gap between how the economy felt and how it was measured became the real story of the night.
Looking Ahead to the Next Cycle
Two years remain until the next major national vote. The party that gained ground now faces the task of turning voter frustration into tangible relief. The party that lost ground faces the harder job of rebuilding trust on the issue that once carried it to victory. Affordability will not vanish as a concern. Gas prices, grocery totals, and the sense of who benefits from the system will continue to shape conversations at dinner tables across the country.
One economist who has advised figures on both sides noted that the sources of American upset are clear. Policymakers who listen stand a better chance of connecting with voters next time. Those who dismiss the numbers risk repeating the same surprise. In my experience the electorate rarely forgets the feeling of stretched budgets. They remember who they believe made the stretch longer and who they hope can ease it.
The 2026 midterms offered a reminder that economic anxiety travels quickly from the household ledger to the ballot box. A conflict that raised energy costs became a domestic political force. Policies intended to strengthen the country at home met resistance when prices rose instead of falling. The result was a wave that changed the balance of power in a single night. Whether that wave continues or recedes will depend on what happens next at the kitchen table and at the pump.
Perhaps the most interesting aspect is how quickly the narrative shifted. The same set of issues that once seemed settled reopened with force. Voters who felt heard two years ago now feel the need to speak louder. The coming months will test whether leaders on both sides can translate that message into policies that ease the daily pressure. Until then the numbers from this week will continue to echo in every discussion about the road ahead.
The Human Side of the Economic Story
Behind every percentage point sits a real household trying to make ends meet. Parents calculating school supplies against rising utility bills. Workers watching fuel costs eat into overtime pay. Retirees measuring fixed incomes against grocery totals that keep climbing. These stories rarely make the front page, yet they decide elections. The survey data captured that quiet calculation. When nearly nine out of ten people name cost of living as a major factor, the collective voice becomes impossible to overlook.
I find it striking how consistent the pattern remains across cycles. Economic pressure builds slowly, then releases all at once at the ballot box. The conflict abroad accelerated the timeline this year. Higher energy prices acted as a constant reminder. Each fill-up became a small referendum on the state of things. By the time voting day arrived, the cumulative weight proved decisive in race after race.
The shift in who voters trust on the economy also deserves attention. Two years ago one side held the advantage. This week the other side claimed it. That reversal did not happen in isolation. It grew from months of price data, sentiment surveys, and personal experience. When three-quarters of people rate the economy poorly, the trust gap widens. Closing that gap will require more than messaging. It will require results that show up in household budgets.
Tariffs, Trade, and Everyday Prices
The tariff debate offers a useful window into the larger tension. Supporters argued that higher import costs would revive domestic production and strengthen long-term growth. Critics pointed to the near-term hit on consumer prices and the risk of retaliation. Market reactions in the early months reflected that uncertainty. Research later suggested that many prices would have declined without the measures. Voter responses tracked closer to the critical view. Nearly two-thirds saw harm rather than help in their local areas.
That perception matters. Even if longer-term benefits eventually appear, the immediate pain registers first. Families do not vote on theoretical future gains when current prices feel high. The same logic applied to other policy areas. Steps that reduced certain costs for some created visible friction for others. The net effect on election day favored the side that promised a different approach to the squeeze.
Energy markets added another layer of complexity. The conflict disrupted crude flows and pushed prices higher across the board. Diesel costs in particular fed into the producer price index and then into consumer goods. Transportation executives described the levels as almost science fiction. Those costs did not stay isolated in the fuel sector. They appeared in the final prices of everyday items. Voters connected the dots without needing detailed economic briefings.
Sentiment Versus Fundamentals
One of the more fascinating elements remains the gap between official economic measures and how people feel. Some indicators continued to show strength even as sentiment gauges hit multi-decade lows. The term once used to describe that disconnect still applies. People experience the economy through their own ledgers, not through aggregate data. When those personal ledgers look worse, confidence falls and voting behavior shifts.
The University of Michigan survey and the Conference Board measure both captured that darker mood. Historic lows in one case and 14-year lows in the other painted a picture of deep unease. Those numbers arrived against a backdrop of reaccelerating consumer prices and wage gains that failed to keep up. The combination proved potent. Behavioral research has long shown that sustained inflation creates political pressure. This cycle confirmed the pattern once again.
Perhaps the lesson for future campaigns is simple. Acknowledge the lived experience before presenting the broader data. Voters who feel the pinch rarely respond to charts showing average improvement. They respond to policies that ease the specific pressures they face each week. The party that figures out that translation stands a better chance of holding or gaining ground next time.
Power Shifts and Future Tests
Control of both the House and Senate now rests with the party that rode the wave of discontent. That control brings opportunity and risk in equal measure. The opportunity lies in demonstrating that a different approach can ease cost-of-living pressures. The risk lies in failing to deliver visible results before the next national vote. History shows that newly empowered majorities often face higher expectations than they anticipate.
The previous majority faces its own test. Rebuilding credibility on the economy after a decisive rejection will require careful recalibration. Some policies that drew criticism may need adjustment. Others that received quieter support may deserve more attention. The balance will prove difficult. Voters have shown they will punish perceived failure on kitchen-table issues regardless of other accomplishments.
Looking across the map, the breadth of the change stands out. Battlegrounds flipped. States long considered reliable shifted. Local races that rarely make national news reflected the same economic undercurrent. The consistency across regions suggests the issue cut deeper than any single candidate or message. It became a shared experience that transcended usual divides.
What Comes Next for Households and Policy
For ordinary families the immediate future still holds uncertainty. Energy markets remain sensitive to developments abroad. Consumer prices have not yet settled into a comfortable range. Wage growth continues to lag in many sectors. The political shift may eventually influence those trends, yet the lag between policy change and household relief can stretch longer than election cycles allow.
Policymakers now hold a clearer map of voter priorities. Cost of living sits at the top. Economic ratings remain low. Trust in who can improve the situation has shifted. The coming months will reveal whether that map guides actual decisions or becomes another set of talking points. In my view the former approach stands a better chance of lasting success. The latter risks another surprise two years from now.
The 2026 midterms will be remembered as the moment economic frustration and conflict costs combined to rewrite the balance of power. The same issues that once lifted one side brought it down when conditions failed to improve. Voters spoke clearly through their choices. The question now is whether the message lands with enough force to shape the next chapter. Households watching their budgets will keep score in the only way that ultimately matters.
Two years is both a long time and a short one in politics. Prices can ease or climb. Conflicts can cool or intensify. Public mood can shift again. What remains constant is the power of the kitchen-table calculation. When enough people decide the current path no longer works, they vote for change. This week they did exactly that. The rest of the story will unfold in the months and years ahead as new leaders try to answer the same question that defined the last campaign. Are you better off? The answer will decide the next wave.