

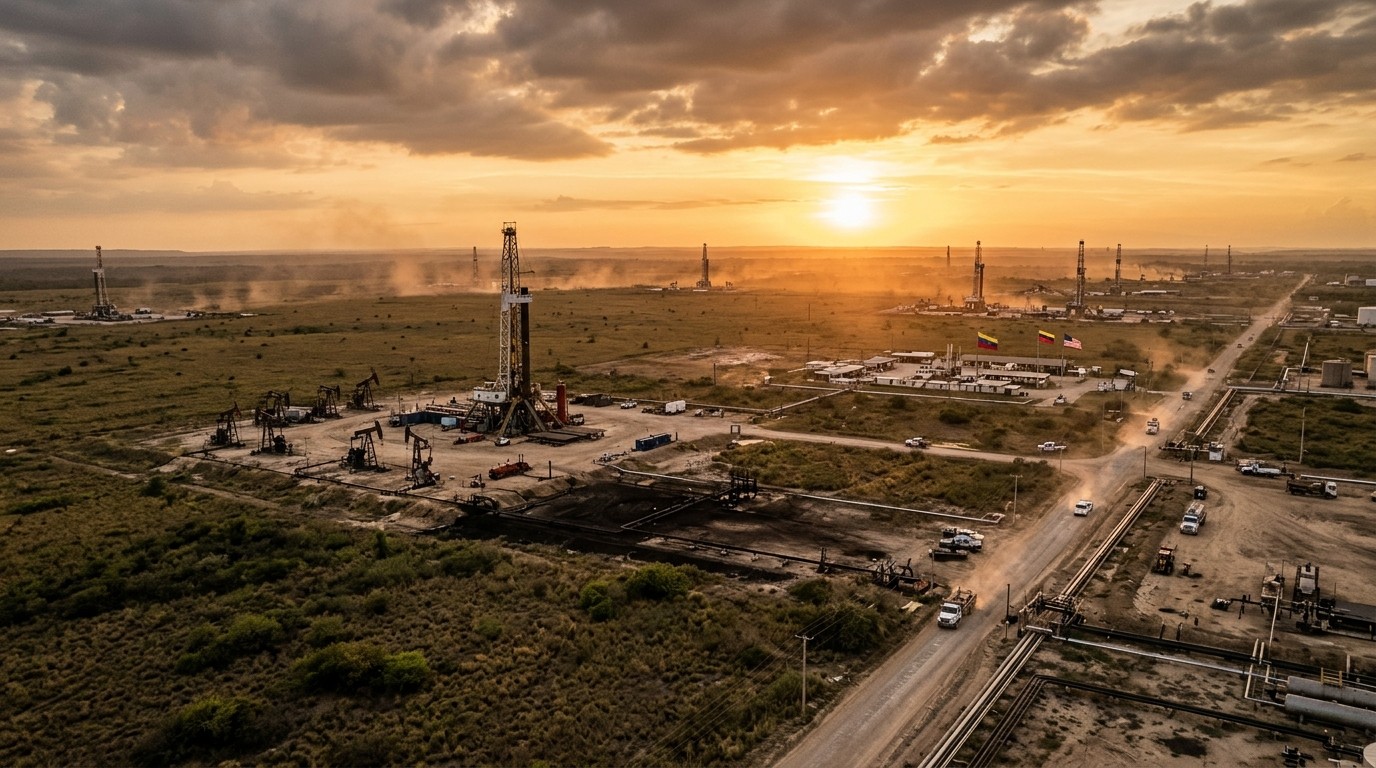

What if the biggest energy announcement of the decade turns out to be more complicated than the headlines suggest? I keep coming back to that question whenever the latest updates on Venezuela’s massive oil concessions surface. The scale sounds almost unreal: long-term rights over tens of billions of barrels, talk of a hundred-billion-dollar build-out, and a company that was barely on anyone’s radar just a short while ago. Yet every time I dig a little deeper, the practical obstacles start looking larger than the promotional language.
Unpacking The Scale Of The New Oil Concessions
The core of the story centers on a private firm that received extensive 100-year rights across seventeen oilfields holding roughly sixty-five billion barrels of proven reserves. Official statements have framed the arrangement as historic. In my view, the sheer volume of resources alone justifies the attention. Venezuela’s heavy oil belt has long been recognized as one of the largest untapped concentrations of hydrocarbons on the planet. Bringing even a fraction of that potential online would alter global supply dynamics for years.
Still, controlling rights and actually extracting oil at commercial scale are two very different things. The company has reported a rapid rise in output, moving from about eighteen thousand barrels per day to more than two hundred twenty thousand in roughly two years. That kind of growth is impressive on paper. It relied heavily on reinvesting cash flow from existing production rather than large external capital raises. The leadership insists this self-funding approach remains the preferred path forward.
I find that strategy both pragmatic and risky. On one hand, avoiding dilution or heavy debt keeps control tightly held. On the other, developing fields of this magnitude usually demands continuous access to specialized equipment, skilled crews, and substantial working capital. Heavy oil is particularly demanding. It requires steam injection, upgraded pipelines, and upgrading facilities before the crude can reach most markets. Those needs do not disappear simply because the rights run for a century.
Production Ambitions Versus On-The-Ground Reality
Current plans call for ramping activity sharply. The company expects its active rig count inside the country to climb toward forty-one units this month, part of a broader target of sixty. Nine rigs are already drilling new wells, with additional units either being refurbished or transported from abroad. Management has emphasized that every piece of equipment is being paid for by oil already produced. That circular financing model worked during the initial expansion phase. Whether it scales cleanly to a million-barrels-per-day target remains an open question.
Industry observers have pointed out that competing for rigs in the current global market is intense. Skilled drilling crews are not sitting idle waiting for new contracts. Logistics inside Venezuela still face constraints related to infrastructure age, security considerations, and the simple physical challenges of operating in the Orinoco region. I have spoken with people familiar with similar heavy-oil projects elsewhere, and the consistent message is that early gains often prove easier than sustained multi-year growth.
We are paying for every one of these rigs with the oil we produce. It is the same reinvestment strategy we used to successfully grow production tenfold in two years.
That statement captures the company’s confidence. Yet independent energy analysts have noted that the hundred-billion-dollar figure represents a long-term funding requirement rather than capital already lined up. No detailed financing structure has been publicly disclosed. In my experience following large resource projects, the gap between announced ambition and committed capital is where many timelines stretch.
How Other Companies Are Positioning Themselves
Interestingly, the broader Venezuelan oil sector is not waiting for any single player. Several established international operators have already moved to expand or re-enter. One major American producer has committed more than seven billion dollars over five years with the goal of lifting its local output above six hundred thousand barrels per day by the early 2030s. Another large independent has signed an agreement to operate a block estimated to contain around thirty billion barrels of resource in place. European and Middle Eastern firms have also secured positions in both oil and gas assets.
This multi-player environment creates both opportunity and competition. Shared infrastructure, joint technical solutions, and a gradually improving regulatory framework could benefit everyone. At the same time, the race for equipment, personnel, and contractor capacity will intensify. The private firm at the center of the large concession package will need to navigate that landscape carefully if it intends to keep its own expansion on schedule.
Perhaps the most interesting aspect is how quickly the commercial landscape shifted after the change in political oversight. New legal and commercial frameworks appear to have lowered barriers that previously kept many companies on the sidelines. That openness has drawn capital and expertise back into the country. Whether the momentum continues will depend heavily on consistent rule application and the ability of operators to generate acceptable returns in a complex operating environment.
Financing The Long Road Ahead
The company has been clear that its current business plan does not contemplate raising outside funding or offering new equity stakes. Management prefers to keep reinvesting monthly cash flow into additional wells and facilities. That approach has delivered measurable results so far. Extending it across decades of development, however, introduces different pressures. Heavy oil projects typically show high upfront capital intensity followed by long periods of relatively stable but moderate cash generation.
I have watched similar self-funded growth stories in other resource jurisdictions. They can succeed when commodity prices cooperate and operational execution stays disciplined. They become fragile when prices soften or when unexpected technical problems appear. Venezuela’s extra-heavy crude requires continuous thermal recovery methods. Those methods consume energy and demand reliable water and steam systems. Any disruption in those support systems quickly affects production volumes and therefore the cash available for further investment.
- Securing specialized drilling and completion equipment in a tight global market
- Attracting and retaining experienced technical personnel willing to work in the region
- Building or rehabilitating the midstream infrastructure needed to move and process the crude
- Maintaining sufficient liquidity during periods of lower oil prices
- Coordinating with other operators who may share facilities or export routes
Each of those items carries cost and timeline risk. Addressing them simultaneously while aiming for a multi-fold production increase is a demanding management task. The leadership team has demonstrated it can deliver rapid early growth. The next phase will test whether the same model can support sustained, large-scale development.
Technical Challenges Of The Heavy Oil Belt
Anyone who has spent time around the Orinoco region understands that the resource is both abundant and stubborn. The oil is extremely viscous at reservoir temperature. It will not flow to the wellbore without help. Steam-assisted gravity drainage and other thermal techniques are the standard solutions. Those techniques work, but they require large volumes of water, significant energy input, and carefully designed well patterns. Surface facilities must also handle the diluted bitumen that results.
In my view, the technical side is manageable with the right expertise and capital. Several international operators already possess decades of experience with similar reservoirs in other countries. The question is less about whether the oil can be produced and more about how quickly the necessary systems can be deployed at the scale implied by the targets. Building steam generation capacity, water treatment plants, and blending facilities takes years even under favorable conditions.
Transportation presents another layer of complexity. Much of the existing pipeline network was designed for lighter grades or has suffered from years of under-maintenance. Expanding export capacity, whether through pipeline upgrades or alternative routes, will require coordination among multiple parties and additional investment. These are not glamorous topics, yet they often determine whether ambitious production goals remain realistic.
The Broader Market Context
Global oil markets are watching developments in Venezuela with interest for good reason. Additional supply from a large new source can influence price expectations, refining margins, and geopolitical calculations. Heavy sour crude has its own demand profile. Certain complex refineries are specifically configured to process it and can achieve attractive margins when the differential to lighter grades is wide. An increase in Venezuelan heavy oil could therefore affect relative pricing across the crude slate.
At the same time, the world continues to debate long-term demand trajectories. Some forecasts see peak oil demand arriving within the next decade. Others expect sustained consumption growth in emerging markets for much longer. Against that backdrop, large new projects still need to clear internal rate-of-return hurdles that account for both price volatility and potential future policy shifts. Investors and operators are increasingly sensitive to those longer-term considerations.
I tend to view the current Venezuelan opening as a classic resource-development story rather than a simple political narrative. Geology, engineering, capital allocation, and execution capability will ultimately decide outcomes. Political stability and clear commercial rules form the necessary foundation, but they do not guarantee commercial success on their own.
What Success Would Actually Look Like
If the company manages to push production past one million barrels per day while funding the expansion largely from internal cash flow, it would represent a remarkable achievement. Reaching that level would require consistent well results, reliable steam systems, adequate takeaway capacity, and a supportive fiscal framework over many years. Intermediate milestones matter just as much. Steady growth in the three-hundred-thousand to five-hundred-thousand barrel range would already signal that the operational model is working at larger scale.
Other operators achieving their own growth targets would reinforce the overall recovery of the national industry. Shared learning, possible infrastructure partnerships, and a larger service sector presence inside the country would all contribute to a more resilient operating environment. In that scenario, the early skepticism currently surrounding the largest single concession package would gradually fade.
Conversely, if equipment delivery slips, if production plateaus, or if financing constraints force a slower pace, the narrative will shift. Markets have short memories for ambitious announcements that fail to convert into barrels. Credibility in the energy sector is built one successful development campaign at a time.
Balancing Ambition With Practical Constraints
Looking across the full picture, I see a classic tension between transformative potential and execution risk. The resource base is enormous. The early production growth has been real. The political and regulatory environment has become more welcoming to investment. Those are genuine positives. Against them stand the well-known difficulties of heavy-oil development, the competitive market for oilfield services, and the capital intensity of sustained expansion.
The company’s decision to avoid external equity for now keeps its options open and its ownership structure simple. That choice also places the entire burden of funding on operational performance. In a high-price environment the model can work beautifully. In a lower-price environment it becomes more stressful. Oil markets have a habit of testing precisely those assumptions.
For observers and potential partners, the next twelve to eighteen months should provide clearer evidence. Rig count trends, actual production numbers, and any signs of infrastructure progress will matter more than further announcements. The industry has seen enough grand visions. What counts now is measurable delivery.
I remain cautiously interested rather than fully convinced. The geological prize is undeniable. Turning that prize into reliable, long-term production at the scale being discussed will require disciplined execution across multiple fronts simultaneously. Few companies manage that combination successfully. Those that do tend to rewrite the supply map for years afterward. Whether this particular effort joins that small group is still an open question, and one worth watching closely.
The coming year will likely separate promotional language from operational reality. Production curves, capital discipline, and the ability to attract and retain the necessary technical talent will tell the real story. Until those elements line up more clearly, healthy skepticism remains the most rational posture. Large oil projects have a long history of surprising both optimists and pessimists. This one appears no different.
Looking Further Down The Timeline
Even under optimistic assumptions, full development of sixty-five billion barrels would stretch across multiple decades. Recovery factors for extra-heavy oil are typically lower than for conventional light oil. Significant portions of the resource may remain in the ground for economic or technical reasons. That reality does not diminish the importance of the current concessions, but it does place the hundred-billion-dollar investment figure into longer-term context.
Technology will continue to evolve. Improvements in thermal recovery, solvent-assisted methods, and digital monitoring could raise recovery factors and lower unit costs over time. Companies that maintain flexibility in their development plans will be better positioned to incorporate those advances. Rigid timelines that assume today’s technology remains static often prove too optimistic.
Environmental and social considerations will also shape the path forward. Water use, emissions intensity, and community relations all influence project viability in the modern era. Operators that address those dimensions proactively tend to encounter fewer delays and stronger stakeholder support. Those that treat them as secondary issues often face costly interruptions later.
From an investor perspective, the combination of resource size, early operational momentum, and evolving regulatory clarity creates a distinctive opportunity set. It also carries distinctive risks. Portfolio managers evaluating exposure to Venezuelan barrels will weigh those factors carefully against alternatives in more established jurisdictions. Diversification across operators and project stages may prove prudent while the recovery story continues to unfold.
Final Thoughts On A High-Stakes Opportunity
The conversation around this particular oil package will continue to evolve with every new production update and every new rig that arrives on location. I expect the debate between skeptics and supporters to remain lively for some time. That tension is healthy. Large resource projects benefit from rigorous external scrutiny. Soft assumptions get stress-tested. Timelines get adjusted. Capital gets allocated more carefully.
For now, the most constructive approach is to track the concrete indicators: wells drilled, steam capacity installed, barrels actually lifted and sold, and the pace of infrastructure rehabilitation. Those numbers will gradually replace both the most optimistic projections and the most pessimistic forecasts with something closer to measurable reality. In the energy business, that is usually the only language that ultimately matters.
Whether this becomes a genuine turning point for Venezuelan production or another chapter of unfulfilled potential remains to be determined by execution rather than announcement. The resources are there. The early results are encouraging. The harder work of scaling responsibly still lies ahead. That, more than any single headline, is the story worth following in the months and years to come.



