
Have you noticed how quickly the ground can shift under even the strongest performers? Not long ago South Korean defense companies looked almost unstoppable. Orders for tanks, self-propelled howitzers and missile systems poured in from Europe and beyond. Share prices climbed to heights that left many long-term investors grinning. Then the numbers started sliding, and the slide has been steep. I keep coming back to one simple question: are these firms built for the kind of war that is actually being fought right now?
The Rise And Sudden Pause Of Korean Defense Exports
For roughly two years the story felt straightforward. Russia’s full-scale invasion of Ukraine forced governments across Europe to rebuild stockpiles they had allowed to shrink for decades. South Korean manufacturers offered something rare in the defense world: proven hardware at competitive prices with relatively short delivery timelines. Buyers who might once have waited years for Western systems found they could receive K2 tanks or K9 howitzers much sooner. That combination proved powerful.
The results showed up clearly in market valuations. The combined market value of the four largest listed Korean defense names once approached levels that seemed almost hard to believe given their earlier size. Then the mood changed. By the end of October that same group of companies had lost a substantial portion of its peak valuation. The drop has left many observers wondering whether the boom was simply a temporary spike or the start of a longer structural shift.
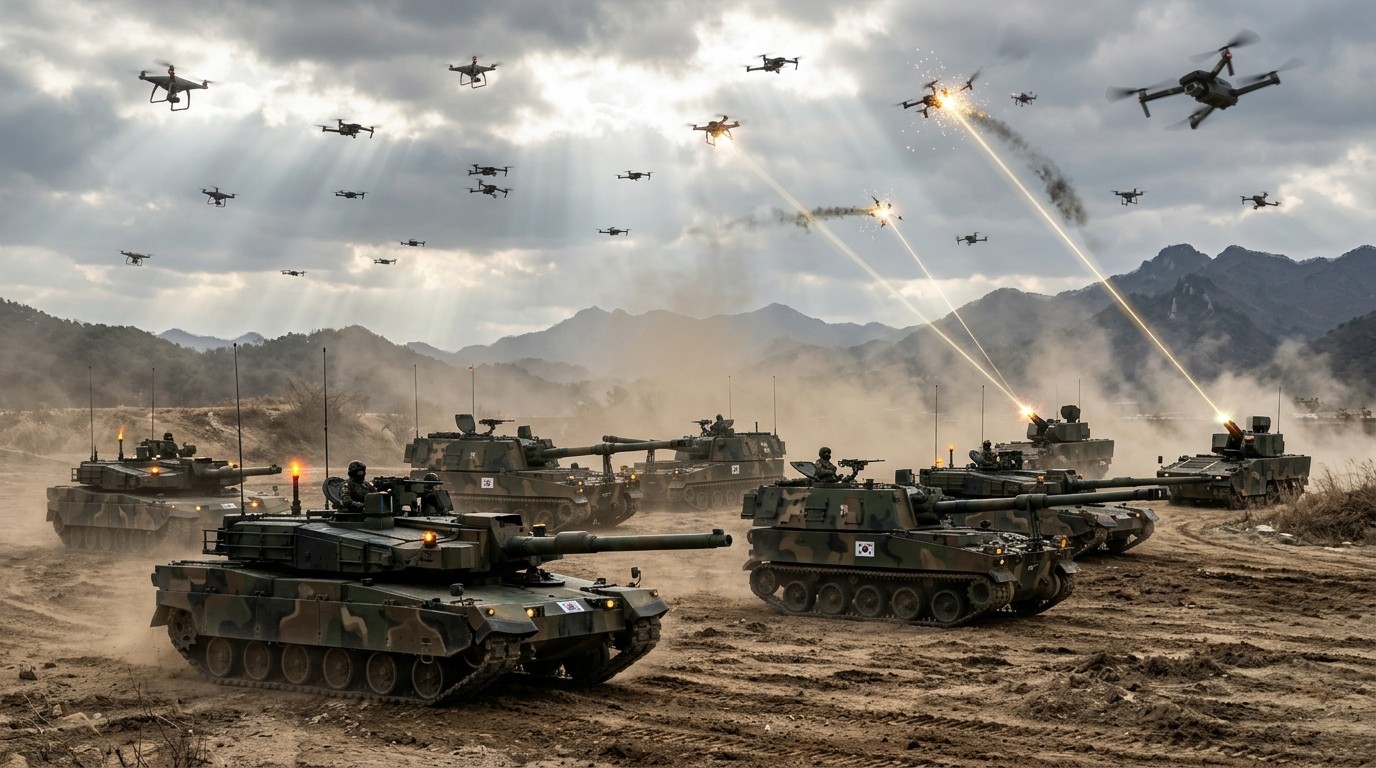
Part of the answer sits on the modern battlefield itself. Inexpensive drones have repeatedly shown they can disable or destroy platforms that cost many times more. The same lesson has appeared in the Middle East, where massed drone and missile attacks have forced expensive interceptors into short supply. Suddenly the traditional heavy systems that Korean firms export so well look more vulnerable than they did even three years ago.
Why Investors Grew Cautious So Quickly
Market sentiment rarely turns on a single factor. In this case several pressures arrived together. Earnings reports came in softer than the market had hoped. Delivery schedules slipped. Currency moves worked against exporters when the won strengthened. At the same time capital rotated toward semiconductor and technology names that offered more immediate growth stories. High valuations that had been justified by aggressive growth expectations began to look stretched once those expectations faced real-world delays.
One major aerospace and defense group reported a sharp drop in operating profit for the third quarter, pointing to adjusted delivery timelines and one-time costs. Another firm that builds both trains and armored vehicles saw its operating profit decline and its share price fall even harder. A third company focused more heavily on aircraft managed to post better sales and profit numbers, which helped limit the damage to its stock. The uneven results only added to the sense of uncertainty.
Governments have also moved more slowly than many expected when converting political commitments into signed contracts and funded budgets. Promises made in the heat of the moment after 2022 have taken longer to turn into purchase orders. That lag has left some balance sheets carrying higher inventories and some investors questioning the near-term earnings trajectory.
Drones Versus Traditional Platforms On Today’s Battlefield
The war in Ukraine has made one reality impossible to ignore. Relatively cheap unmanned systems can threaten expensive tanks, artillery pieces and even air-defense batteries. At the same time, large-scale drone and missile attacks have forced countries to expend costly interceptors at a rate few had planned for. The economics of modern conflict have shifted in ways that favor volume, speed and electronic sophistication over pure mass of steel.
Analysts have been blunt about the implications. One senior market strategist noted that modern warfare increasingly relies less on the traditional systems Korean companies have specialized in. Another observer pointed out that China currently dominates much of the commercial and military drone supply chain, creating pricing pressure that makes it hard for European, American or other Asian producers to compete on pure cost.
Procurement priorities are clearly evolving toward drones, counter-drone systems and layered air defense. Conventional platforms remain important, yet they no longer sit alone at the center of every shopping list.
Still, the picture is not entirely one-sided. Tanks and artillery continue to matter when forces need to seize and hold ground. Drones can harass and destroy, but they cannot occupy territory in the same way armored units can. That distinction keeps demand alive for the systems Korean factories already produce in volume.
Recent Contracts That Still Point To Demand
Despite the share-price pain, concrete orders have continued to arrive. One major deal involved a substantial order for K9 howitzers destined for Spain. Another covered advanced rocket systems for Norway valued in the high hundreds of millions of dollars. A naval surface-to-air missile system secured its first export customer in Southeast Asia. These contracts demonstrate that conventional deterrence requirements have not disappeared.
European and Middle Eastern partners continue to expand cooperation with Korean firms, particularly in the air-defense domain. Additional howitzer orders suggest that supply constraints and the simple need to rebuild depleted inventories still support demand for proven platforms. In my view this mix of new-generation threats and enduring conventional needs creates a more complex but not necessarily negative outlook.
The long-term growth rate for the sector is still described by some market participants as remaining in the mid-to-high teens when measured over a multi-year horizon. That kind of trajectory, if realized, would still look attractive relative to many other industrial sectors.
How Korean Firms Are Responding To The Drone Challenge
The companies themselves are not standing still. Investment in unmanned systems and counter-drone technologies has increased. Research programs focused on loitering munitions, small tactical drones and electronic warfare packages have moved higher on internal priority lists. Progress remains gradual because overseas buyers typically demand proven combat performance before placing large orders. Building that track record takes time.
Some observers expect more tangible commercial results in the unmanned domain to appear within the next couple of years. Until then the bulk of revenue will continue to come from the heavier systems that already have established export pipelines. The challenge is to keep those pipelines open while simultaneously building credibility in the newer categories that are growing fastest.
One strategist put the balance rather neatly: greater emphasis on artificial intelligence and drone technology is inevitable as major powers absorb the lessons of recent conflicts, yet drones alone cannot capture and hold terrain. In any mobile battlefield the need for infantry, armor and supporting artillery remains fundamental. That reality gives Korean manufacturers a bridge while they develop the next generation of capabilities.
Currency, Earnings And The Weight Of Expectations
Beyond the technological questions, more ordinary financial factors have weighed on the stocks. A stronger domestic currency reduces the won value of contracts denominated in dollars or euros. Delivery delays push revenue recognition into later periods. One-time costs related to capacity expansion or supply-chain adjustments can distort quarterly comparisons. None of these issues are permanent, yet together they have created a stretch of disappointing numbers that has tested investor patience.
High expectations had been priced in during the peak of the rally. When actual results failed to match the most optimistic forecasts, the correction was swift. Fund flows that had earlier favored defense names rotated toward sectors perceived as offering cleaner near-term growth. The combination left defense shares looking relatively neglected even as the underlying geopolitical drivers remained largely intact.
I find it useful to separate the cyclical and the structural. Currency moves and temporary delivery hiccups belong to the cyclical column. The longer-term requirement for nations to modernize and expand their forces belongs to the structural one. Right now the cyclical headwinds are more visible, but the structural tailwinds have not vanished.
Comparing Performance Across The Major Players
Not every company has experienced the same degree of pressure. The firm with the broadest exposure to aerospace programs managed to deliver year-over-year growth in both sales and operating profit during the most recent quarter, which helped cushion its share price. By contrast, the specialist in land systems and the company with a large artillery and rocket portfolio faced steeper profit declines and correspondingly larger share-price drops.
This dispersion offers a reminder that “defense” is not a single monolithic sector. Different product mixes, different customer concentrations and different stages of capacity investment all influence how individual names respond to the same macro environment. Investors who treat the group as a uniform block risk missing important distinctions.
| Company Focus | Recent Profit Trend | Share Reaction | Key Strength |
| Aerospace systems | Improved | Limited decline | Diversified programs |
| Land systems & vehicles | Soft | Steep drop | Tank & vehicle exports |
| Artillery & rockets | Mixed | Significant decline | Howitzer & MLRS orders |
| Missile systems | Steady | Moderate pressure | Naval & air defense |
The table above is necessarily simplified, yet it captures the sense that outcomes have varied more than a casual glance at sector headlines might suggest.
Longer-Term Demand Drivers That Still Matter
Several structural forces continue to support the case for Korean defense exporters. European armies are still far from the force levels and readiness standards their political leaders have publicly targeted. Middle Eastern customers remain focused on layered air and missile defense after recent attacks. Indo-Pacific tensions keep regional defense budgets elevated. In each of these theaters Korean systems have already demonstrated an ability to win competitive evaluations on price, performance and schedule.
Additional orders for established platforms such as the K9 continue to surface, suggesting that the need to fill existing capability gaps has not been erased by newer technologies. At the same time, partnerships in Europe and the Middle East around air-defense solutions indicate that Korean firms are finding ways to participate in the higher-priority segments of current procurement plans.
Perhaps the most interesting aspect is the dual-track approach many of these companies are now pursuing. They continue to sell the systems they already manufacture efficiently while investing in the unmanned and counter-unmanned technologies that will define future contracts. That transition will not be instantaneous, but the direction of travel is clear.
What A Realistic Path Forward Looks Like
In the near term the sector is likely to remain sensitive to quarterly earnings, currency swings and the precise timing of large contract announcements. Any further delays in converting political commitments into funded orders will keep pressure on valuations. Conversely, a string of solid deliveries and new contract wins could help stabilize sentiment relatively quickly.
Over a longer horizon the combination of persistent geopolitical tension and the still-unfinished modernization of many allied forces creates a supportive backdrop. The question is less whether demand exists and more whether Korean companies can adapt their product portfolios fast enough to capture a meaningful share of the fastest-growing segments.
I have found that markets often over-react in both directions. The earlier euphoria around defense names priced in almost perfect execution. The current skepticism may be pricing in more disruption than is actually likely. Somewhere between those two extremes sits a more balanced view: conventional platforms will continue to generate substantial revenue while unmanned systems gradually become a larger part of the mix.
Balancing Innovation With Proven Strengths
Korean industry has repeatedly shown an ability to move quickly from design to production. That same agility is now being applied to drone and counter-drone programs. The difference this time is that the competitive landscape is more crowded and the technology cycles are shorter. Success will require not only engineering talent but also the ability to demonstrate operational effectiveness under realistic conditions.
Meanwhile the existing product lines still enjoy advantages that are hard to replicate quickly. Production capacity for heavy systems has been expanded. Supply chains are relatively mature. Customer relationships in key export markets have been cultivated over years. Those assets will not disappear overnight even as the character of warfare continues to evolve.
- Maintain and expand production of tanks, howitzers and rocket systems that still meet clear operational needs
- Accelerate development of indigenous unmanned aerial systems and counter-drone packages
- Deepen partnerships with European and Middle Eastern customers on integrated air-defense solutions
- Build combat-proven track records that overseas buyers demand before placing large unmanned-system orders
- Manage currency and delivery risks more tightly to reduce earnings volatility
These priorities are not mutually exclusive. The firms that execute well on both the legacy and the emerging sides of the portfolio are likely to emerge in stronger competitive positions.
Investor Considerations In A Changing Landscape
Anyone looking at the sector today faces a classic tension between short-term noise and longer-term fundamentals. Share prices have already corrected substantially from their peaks. Earnings visibility remains imperfect. Technological disruption is real. At the same time the underlying drivers of elevated defense spending across multiple regions show little sign of fading.
Some market participants continue to describe the long-term growth outlook as still attractive relative to broader industrial averages. Others prefer to wait for clearer evidence that the transition into unmanned systems is generating meaningful revenue. Both perspectives contain elements of truth. The path forward will probably reward patience more than it rewards attempts to time every quarterly fluctuation.
Currency trends, the pace of European budget execution and the success of new product introductions will all influence how quickly confidence returns. In the meantime the sector offers a live case study in how established industrial champions adapt when the nature of their core market begins to shift beneath them.
Looking Beyond The Immediate Volatility
The sharp decline in Korean defense valuations has focused attention on genuine challenges. Drones and electronic warfare have changed the cost-exchange ratios that once favored heavy armor and expensive interceptors. Delivery schedules and currency moves have complicated the near-term earnings picture. Yet the same geopolitical forces that created the original boom have not disappeared. Nations still need the ability to deter aggression and, if necessary, to fight and win on the ground.
Korean companies enter this next phase with established production capacity, competitive cost structures and a growing list of export references. Their ability to add credible unmanned and counter-unmanned capabilities will determine how large a role they play in the defense market of the 2030s. Early signs of investment and partnership activity suggest they understand the requirement. Turning those efforts into sustained commercial success will be the real test.
For now the market is weighing the risks more heavily than the opportunities. That imbalance may not last forever. History shows that periods of technological transition in defense often create temporary uncertainty before a new equilibrium emerges. The firms that navigate the transition most effectively will likely look very different in a decade, yet they will still be built on the manufacturing and engineering strengths that first carried them into the global spotlight.
The battlefield keeps evolving. The companies that supply it must evolve as well. South Korea’s defense sector is in the middle of that process, and the outcome will matter well beyond its own borders.
In the end the story is less about a sudden end to demand and more about a necessary broadening of capabilities. Tanks and howitzers still have roles to play. So do the smaller, smarter systems that now share the sky with them. The winners will be the organizations that can deliver both with equal conviction.