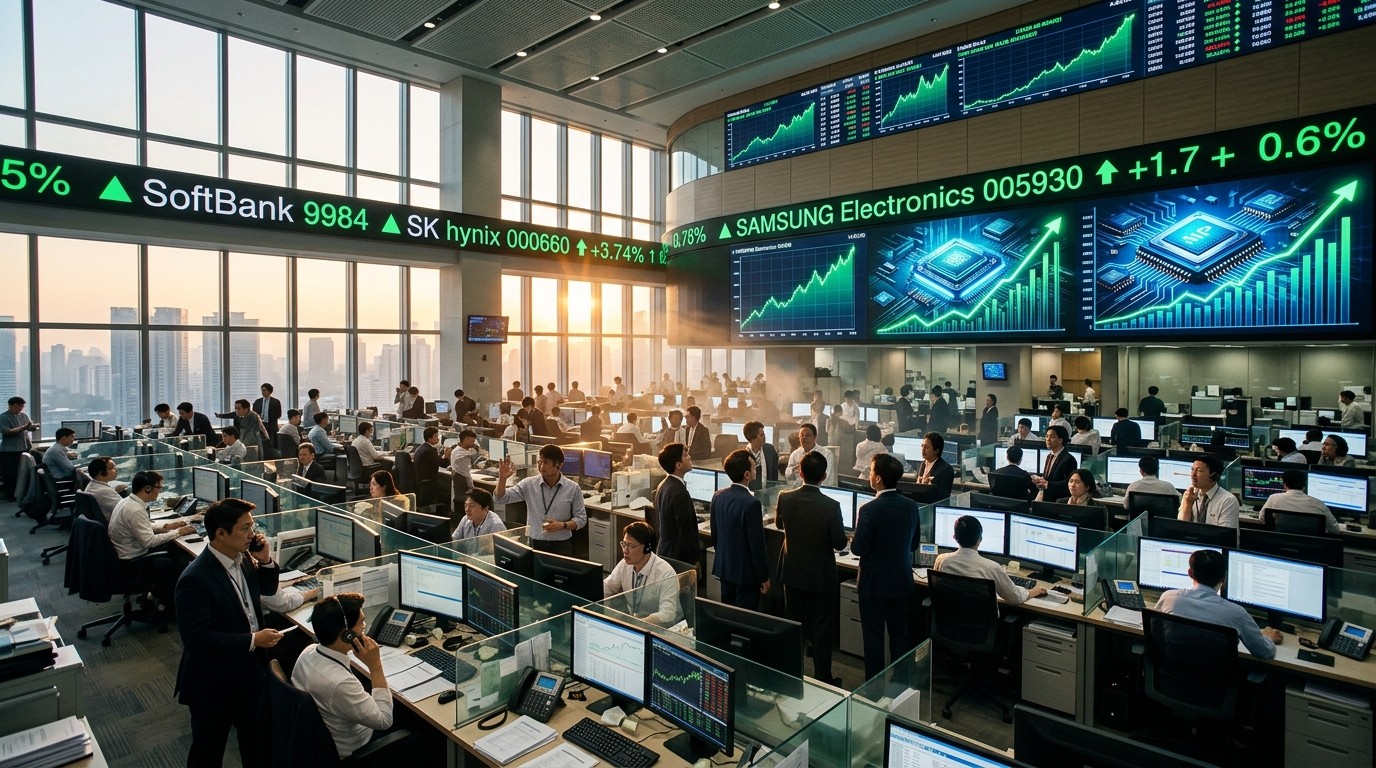

Have you ever watched a market that looked completely broken one week suddenly roar back to life the next? That is exactly what happened across Asian technology shares this week. After a painful stretch of selling that left many investors checking their portfolios with a sense of dread, a wave of buying returned and it did not come quietly. SoftBank Group, SK Hynix and Samsung Electronics stood at the center of the move, posting gains that turned heads from Tokyo to Seoul and beyond.
What Sparked The Sudden Turnaround In Asian Tech
The bounce did not appear out of thin air. Overnight trading on Wall Street set the stage. The tech-heavy Nasdaq Composite climbed more than two and a half percent while the broader S&P 500 notched its strongest session in months. That kind of strength rarely stays contained within one time zone. By the time Asian markets opened, the mood had already shifted from caution to opportunity.
Lower oil prices also helped. When energy costs ease, investors often feel freer to put capital back into growth-oriented names. Semiconductor and technology infrastructure companies benefited most because many of them sit at the heart of the artificial intelligence build-out. Last week’s sharp decline had been driven by fresh worries that political changes in the United States might tighten rules around data-center construction. Those concerns did not vanish overnight, yet the market decided the selling had gone far enough for the moment.
SoftBank’s Sharp Climb And What It Signals
SoftBank Group shares jumped roughly twelve percent in a single session. That kind of move is hard to ignore. The company has long been viewed as a high-conviction bet on technology innovation, particularly through its large holdings in artificial intelligence and semiconductor-related businesses. When SoftBank rises this sharply, it often reflects renewed optimism about the broader tech cycle rather than any single company announcement.
I have followed SoftBank for years and still find its price action fascinating. It can lag during risk-off periods and then lead hard when sentiment flips. Tuesday’s gain felt like one of those classic catch-up moves. Investors who had reduced exposure during the previous week’s sell-off appeared eager to rebuild positions before the opportunity slipped away.
Of course, volatility remains part of the package with SoftBank. The stock has delivered both spectacular rallies and painful drawdowns in the past. Still, the scale of this particular advance suggests that many market participants now see the recent political concerns as less immediate than they did just a few trading days earlier.
SK Hynix And Samsung Lead The Chip Rebound
South Korean memory giants delivered equally impressive performances. SK Hynix climbed a little more than eight percent while Samsung Electronics advanced over five percent. Samsung SDI, which focuses on batteries and energy storage, also participated with a gain above six percent. These numbers matter because memory chips sit at the core of almost every artificial intelligence system being built today.
High-bandwidth memory has become one of the most sought-after components in the current technology cycle. Demand from data-center operators remains strong even as some investors worry about future regulatory hurdles. The market appears to be separating short-term political noise from the longer-term structural need for more advanced chips.
In my view, the strength in these names also reflects a simple valuation reset. After last week’s decline, many of the leading semiconductor stocks had become more attractive on a relative basis. Buyers stepped in once the selling pressure eased, and the resulting short-covering probably amplified the upward move.
Japanese Equipment Makers Join The Rally
The recovery was not limited to chip producers. Japanese companies that supply the tools used to manufacture advanced semiconductors also posted solid gains. Tokyo Electron rose nearly six percent. Advantest, which specializes in testing equipment, advanced more than five percent. Lasertec and Disco each climbed over six percent. These moves show how broadly the renewed optimism spread across the technology supply chain.
Equipment makers often act as leading indicators. When their shares start to outperform, it usually means investors expect higher capital spending from the chip foundries and memory producers further down the line. That is exactly the signal the market received on this particular day.
I find the Japanese names especially interesting because they tend to trade with a bit more sensitivity to global technology cycles than many local industrial stocks. Their participation gave the rally an extra layer of confirmation that the move was more than a one-country story.
How Last Week’s Sell-Off Set The Stage
To understand the strength of the rebound, it helps to remember how steep the previous decline had been. Concerns about potential new restrictions on data-center development in the United States had hit technology stocks hard. Investors worried that slower growth in artificial intelligence infrastructure could reduce demand for the very chips and equipment that Asian companies supply.
Those fears were real enough to trigger widespread selling. Yet markets rarely move in straight lines. Once the initial wave of risk reduction ran its course, buyers began looking for opportunities. The combination of cheaper oil, a strong Wall Street session, and attractive valuations after the drop created a favorable setup.
Markets often overreact to political headlines in the short term and then refocus on underlying demand trends once the dust settles.
That process appears to have started this week. Whether it continues will depend on how future policy discussions evolve and whether corporate earnings continue to support the optimistic narrative around artificial intelligence spending.
Broader Market Context And Investor Sentiment
It is worth placing this Asian tech rebound inside the larger global picture. Equity markets had been digesting a series of mixed signals for several weeks. Interest rate expectations, energy prices, and political developments all competed for attention. When the technology sector finally found a floor, the relief was palpable.
Sentiment indicators had reached levels that historically coincide with short-term bottoms. Put-call ratios and volatility measures suggested that many investors had already positioned defensively. Once a catalyst appeared in the form of stronger U.S. trading and lower oil, the path of least resistance shifted higher.
I have seen this pattern before. Sharp declines driven by uncertainty often give way to equally sharp recoveries once the market decides the worst-case scenario is less likely. The current move fits that template, at least for now.
Key Factors Supporting The Recovery
Several concrete elements helped propel the gains. First, the overnight performance of U.S. technology shares removed some of the immediate pressure. Second, the decline in oil prices improved the overall risk environment. Third, the sheer scale of last week’s selling had left many portfolios underweight the very names that had been leading the market for most of the year.
- Stronger-than-expected U.S. equity session reduced global risk aversion
- Lower energy costs supported broader market confidence
- Attractive valuations after the prior week’s decline invited fresh buying
- Continued structural demand for high-performance memory and equipment
- Positioning that had become overly cautious during the sell-off
Each of these factors reinforced the others. The result was a session in which many of the hardest-hit stocks from the previous week led the rebound.
Looking At Valuation And Momentum
Valuation is never the only driver, yet it matters. After last week’s decline, several leading Asian technology names were trading at more reasonable multiples relative to their expected growth. That created room for multiple expansion once sentiment improved. Momentum then took over as short-term traders and systematic strategies began to chase the upward move.
In my experience, these technical and fundamental elements often work together. When both point in the same direction, the resulting price action can be powerful. Tuesday’s session offered a clear example of that dynamic.
Still, investors should remember that momentum can reverse just as quickly as it builds. The same political questions that triggered the original sell-off have not disappeared. Any fresh headlines on data-center regulation or trade policy could test the durability of this recovery.
What The Move Means For The Artificial Intelligence Theme
The artificial intelligence investment cycle remains one of the most important long-term stories in global markets. Companies across Asia play critical roles in supplying the memory, logic chips, and manufacturing equipment required to build the next generation of data centers. When those stocks rebound together, it reinforces the idea that the structural demand story is still intact.
That does not mean every company will benefit equally. Competitive dynamics within the memory industry, capital expenditure plans at major foundries, and the pace of new product introductions will all influence relative performance. Yet the broad participation on this particular day suggests investors are still willing to look through near-term uncertainty toward longer-term growth.
I remain constructive on the overall theme while staying mindful of the risks. Political developments can alter the timing of investment cycles even if they do not change the ultimate direction. Watching how companies manage their own capital spending and inventory levels will provide important clues in the months ahead.
Practical Considerations For Investors
For those following these markets, a few practical points stand out. First, volatility is likely to remain elevated until greater clarity emerges on the regulatory front. Second, diversification across different parts of the technology supply chain can help manage company-specific risks. Third, keeping an eye on U.S. market leadership remains essential because Asian technology shares often take their cue from overnight developments in New York.
Position sizing also deserves attention. Sharp rebounds can tempt investors to increase exposure quickly. A more measured approach that accounts for the possibility of further setbacks usually serves long-term portfolios better.
| Company Focus | Recent Move | Key Driver |
| Investment Holdings | Strong double-digit gain | Renewed AI optimism |
| Memory Production | High single-digit advance | Data center demand |
| Equipment Supply | Solid mid-single-digit rise | Capex expectations |
The table above offers a simplified snapshot of how different segments participated. The common thread was a willingness to look past last week’s political concerns and re-engage with the growth narrative.
Risks That Still Deserve Attention
No recovery is risk-free. The same issues that drove the previous sell-off could return if new information emerges. Changes in U.S. policy toward data-center construction or energy usage could affect the pace of artificial intelligence infrastructure spending. Currency moves, particularly involving the Japanese yen and Korean won, can also influence reported results for exporters.
Geopolitical tensions remain another background factor. Supply chains for advanced semiconductors are complex and span multiple countries. Any disruption, whether from trade measures or logistics challenges, would quickly show up in the share prices of the companies involved.
I prefer to treat these risks as ongoing rather than temporary. Building that awareness into investment decisions helps avoid unpleasant surprises when markets inevitably turn more cautious again.
How This Fits Into The Bigger Market Cycle
Looking further out, the current episode fits a familiar pattern within technology cycles. Periods of rapid growth and rising valuations are often interrupted by corrections linked to external shocks or shifts in investor psychology. The strongest companies tend to emerge from those corrections with their competitive positions intact or even improved.
Whether the present rebound marks the start of a sustained recovery or merely a pause within a longer consolidation remains to be seen. The answer will depend less on one or two trading sessions and more on how corporate fundamentals and policy developments evolve over the coming quarters.
What feels clear right now is that Asian technology shares still command significant attention from global investors. When the sector moves, it moves with force. Tuesday’s session served as a reminder of that reality.
Final Thoughts On Navigating The Current Environment
Markets rarely offer perfect clarity. The recent swing from heavy selling to strong buying in Asian tech stocks illustrates that point well. Investors who stayed disciplined through the volatility were better positioned to benefit from the rebound. Those who reacted emotionally to the political headlines may have sold near the lows.
Going forward, a balanced approach seems sensible. Respect the structural growth story around artificial intelligence and advanced semiconductors. At the same time, remain realistic about the political and macroeconomic uncertainties that still exist. That combination of optimism and caution has served thoughtful investors well through many previous cycles.
The names that led this particular rally SoftBank, SK Hynix, Samsung Electronics and the Japanese equipment makers will continue to be watched closely. Their performance often provides an early read on how the broader technology complex is digesting new information. For now, the message from the market is one of renewed willingness to engage with risk. Whether that message grows stronger or fades will be one of the more interesting questions for the weeks ahead.
In the end, successful investing in this space usually comes down to separating signal from noise. Last week’s sell-off contained a heavy dose of noise. This week’s rebound may contain more signal. Sorting the two will remain the central task for anyone following these markets.
The speed of the recovery also highlights how quickly sentiment can shift when liquidity and positioning align. Many participants had reduced risk during the prior decline. Once buying began, the limited supply of shares available at lower prices helped fuel the upward momentum. That mechanical aspect of markets often surprises those who focus only on headlines.
Looking across the region, the breadth of the advance offered additional encouragement. It was not limited to one or two high-profile names. Memory producers, equipment suppliers and investment vehicles all participated. Such coordination usually indicates a genuine change in risk appetite rather than isolated company-specific news.
Of course, one strong session does not define a trend. Confirmation will require follow-through in the days and weeks ahead. Volume, leadership consistency and the behavior of related sectors will all provide useful clues. For the moment, however, the direction of travel has clearly improved.
Investors who maintain a longer time horizon may view the recent volatility as an opportunity rather than a threat. The fundamental drivers of demand for advanced semiconductors have not disappeared. Data centers continue to expand. Artificial intelligence models keep growing in complexity. The companies that supply the necessary components remain strategically important.
At the same time, valuation discipline still matters. Paying any price for growth has rarely worked well over complete market cycles. The more attractive entry points created by last week’s decline may prove valuable if the recovery continues. Those who waited for perfect certainty may find themselves chasing prices higher.
The interplay between U.S. and Asian markets also deserves ongoing attention. Overnight leadership from the Nasdaq often sets the tone for the following Asian session. When that leadership turns positive, the odds of a constructive day in Tokyo, Seoul and Taipei increase meaningfully. The reverse is equally true. Monitoring that relationship remains a practical tool for anyone active in these markets.
Currency effects add another layer. A weaker yen can support Japanese exporters even when global demand is mixed. Moves in the Korean won influence the competitive position of memory producers. These cross-currents sometimes amplify or dampen the underlying equity moves, making them worth tracking alongside the pure equity story.
In practical terms, many professional investors will now reassess their regional and sector allocations. The sharp rebound may encourage some to restore exposure that was reduced during the sell-off. Others may prefer to wait for additional confirmation. Both approaches can be valid depending on individual risk tolerance and time horizon.
What feels most important is avoiding the extremes. Panic selling at the lows and euphoric buying at the highs have destroyed more capital over time than almost any other behavior. Staying grounded in the fundamental trends while remaining flexible about short-term price action tends to produce better outcomes.
The current episode also serves as a useful reminder of how interconnected global markets have become. A political development in one country can trigger selling across multiple continents within hours. The subsequent recovery can travel just as quickly. Understanding those transmission mechanisms helps investors prepare rather than simply react.
As the week progresses, attention will turn to whether the gains can be sustained. Corporate commentary, economic data and further policy signals will all influence the path. For now, the message from Asian technology shares is clearer than it was a few days ago. The worst of the recent selling appears to have passed, at least temporarily, and a more constructive phase has begun.
Whether that phase develops into something more durable will depend on forces larger than any single trading session. Yet the strength displayed by SoftBank, SK Hynix, Samsung Electronics and their peers has already changed the near-term conversation. Investors who were focused solely on downside risks last week now have fresh evidence that upside scenarios remain very much alive.
That shift in tone, more than any individual percentage gain, may prove to be the most meaningful development of the day. Markets move on changes in perception as much as changes in fundamentals. On this particular Tuesday, perception improved markedly, and prices responded in kind.