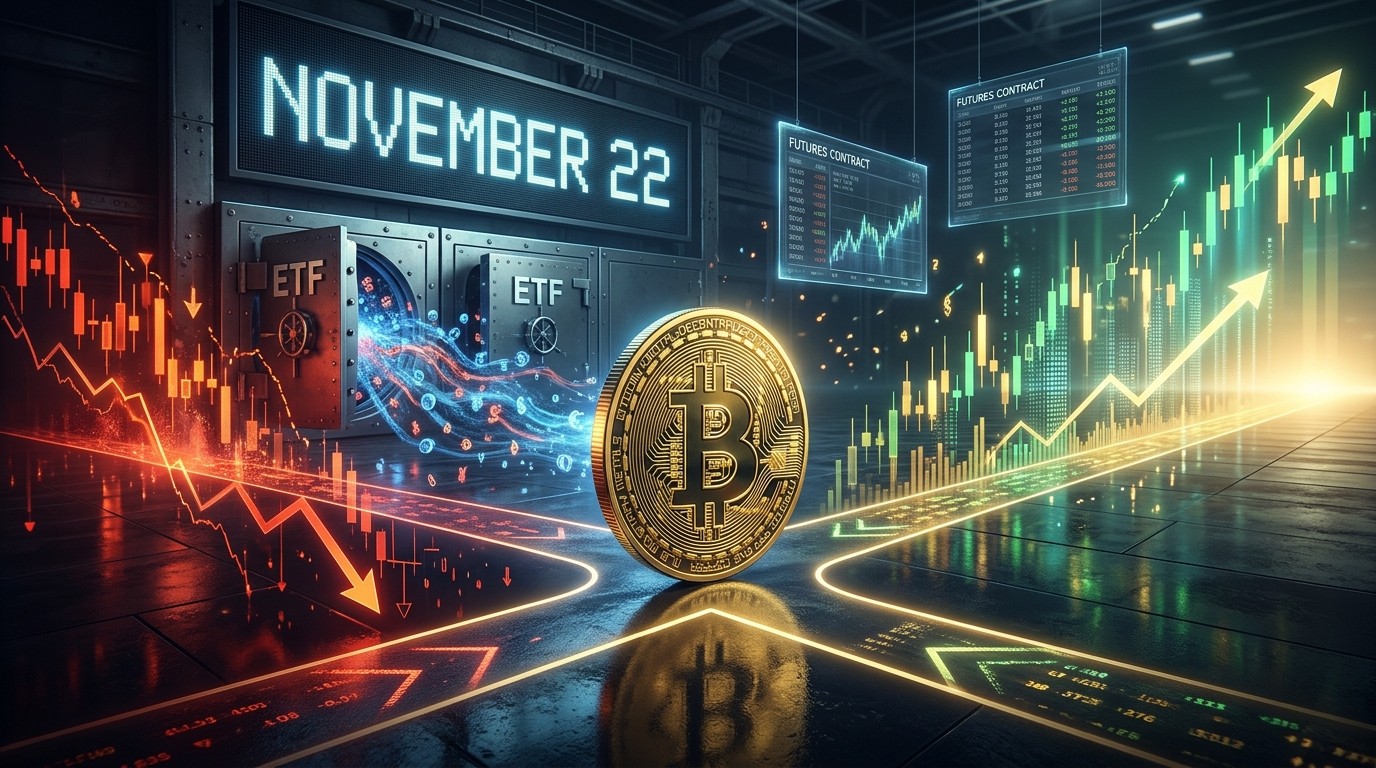

I’ve been watching Bitcoin long enough to know that some dates start to feel heavier than others. Right now, November 22 sits on the calendar like a quiet deadline. After more than two billion dollars left spot Bitcoin ETFs in just eight sessions, the market is sitting below a level that short-term holders paid for their coins. The question hanging over everything is simple: can buyers return in time, or does this correction stretch into something longer and more painful?
Why November 22 Matters More Than Most Dates
Bitcoin has already fallen as much as 16.8 percent from its September peak. That kind of move always shakes confidence, but what makes the current situation different is the combination of heavy ETF selling and traders who keep adding leverage even while the price drops. Analysts tracking on-chain data have zeroed in on one clear hurdle. The average cost basis for coins held less than 155 days sits near 75,717 dollars. Bitcoin spent several days under that mark after sliding toward 72,706 dollars following the latest inflation numbers.
When price sits below the short-term holder cost basis, those recent buyers tend to sell into any bounce that gets them close to break-even. I’ve seen this pattern play out before. It creates a ceiling that is hard to break until fresh spot demand appears. Roughly 1.6 million Bitcoin bought between 75,000 and 80,000 dollars is currently underwater. That is a lot of potential supply waiting for a reason to exit.
The Scale of Recent ETF Outflows
The numbers are hard to ignore. Across eight sessions starting from late October, net withdrawals from U.S. spot Bitcoin ETFs reached 2.22 billion dollars. That stands as the largest outflow stretch since early July. Even though daily outflows have slowed, the damage is already on the books. One session saw 201 million leave, the next another 95 million. The pace has eased, yet the cumulative effect remains.
What stands out is how concentrated the selling has been. One major product accounted for the large majority of the total outflow. When that kind of volume leaves the market, it removes a key source of steady buying that had supported price for months. Earlier this year, outflow periods that later reversed usually needed at least three straight sessions of inflows before a meaningful rebound took hold. We have not seen that yet.
Corporate treasury buying has not filled the gap either. Even though one large holder continued adding a modest amount of Bitcoin, the overall corporate demand has not been strong enough to offset the ETF selling. Some other treasury holders have even reduced positions. The result is a market that feels thinner on the bid side than many expected at this stage of the cycle.
Leverage Keeps Climbing While Price Falls
Perhaps the most interesting and worrying part of the recent price action is what has happened in the futures market. Between early November and midweek, open interest rose more than three percent to around 701,900 Bitcoin even as the price itself dropped 2.6 percent. That means traders were adding positions while the market was moving against them.
After the inflation data hit, roughly 729 million dollars in positions were liquidated, most of them long. Yet open interest barely moved. Traders simply replaced the closed positions almost immediately. This is not a new pattern. The same behavior appeared in mid-October and already triggered one wave of forced selling. When funding rates stay elevated near 11 percent annualized while price is falling, it tells you that many participants are still willing to pay to stay long. That kind of stubborn optimism leaves the market exposed to another round of long liquidations if price drops further.
Such behaviour also leaves the market exposed to further long liquidations.
In my experience, markets that keep rebuilding leverage into weakness rarely find a clean bottom until that leverage is cleared. It is uncomfortable to watch, but the data is clear.
Historical Patterns Around the Short-Term Cost Basis
Looking back at similar situations since 2016 gives some useful context. There have been fourteen occasions when Bitcoin fell below its short-term holder cost basis after spending at least sixty days above it. In eleven of those cases, price recovered the level within two weeks. The other three took between 57 and 114 days. During those longer recoveries, the lowest point over the following ninety days sat 17 to 35 percent below the cost basis.
The current break below the cost basis began on November 8. That puts the two-week checkpoint squarely on November 22. If Bitcoin can climb back above 75,717 dollars and ETF flows turn positive for three consecutive sessions, the more constructive correction scenario remains intact. If not, the historical record suggests the market may need more time and possibly lower prices before a lasting recovery begins.
One positive note is that the intensity of selling so far has been milder than the May-to-July period. Realized losses over twelve consecutive days reached about 172,700 Bitcoin, averaging roughly 14,400 per day. That is significantly lower than the 45,000 daily average seen during the earlier sell-off. Coins that changed hands on one recent day were sold at an average loss of only about one percent. Meanwhile, the amount of Bitcoin acquired between 70,000 and 75,000 dollars has grown by more than 230,000 in just a few days. That suggests some buyers are still willing to step in at these levels, but they need the underwater holders to stop selling into every bounce.
How Equity Moves Have Failed to Lift Bitcoin
Bitcoin’s attempts to recover have been short-lived. One bounce above 80,000 dollars earlier in the month coincided with a wave of short liquidations, yet the move did not stick. The inflation report that followed quickly pushed trading back under 74,000 dollars. Over the twenty-five sessions after the Nasdaq 100 made its early October high, Bitcoin captured most of the index’s losses on down days but only a little more than half of the gains on up days. That is a clear change from the prior sixty sessions when Bitcoin had been capturing far more of the upside.
On one recent day the Nasdaq rose more than three percent while Bitcoin finished lower than it had been at the previous equity close. That kind of divergence is never comfortable for crypto traders who have grown used to following risk assets higher. It raises the possibility that Bitcoin is trading more on its own internal supply and demand dynamics right now than on broader market sentiment.
What Needs to Happen for a Cleaner Recovery
For the market to move past this phase cleanly, a few things need to align. First, ETF flows have to turn and stay positive for several sessions. Second, the short-term holder cost basis needs to be reclaimed and held. Third, the constant rebuilding of leveraged long positions needs to ease so that the market is less vulnerable to forced selling. None of these are guaranteed, but they are measurable. That is one reason the November 22 date feels useful. It gives a clear window to judge whether the correction is resolving or extending.
I keep coming back to the idea that selling pressure from recent buyers remains the main near-term obstacle. Until those holders feel more comfortable holding through higher prices, every rally toward their cost basis risks meeting fresh supply. At the same time, the fact that realized losses have been relatively contained suggests the broader holder base is not in full panic mode. That distinction matters.
The Role of Spot Demand Versus Leverage
One of the clearest lessons from the past year is that sustained advances in Bitcoin tend to require genuine spot buying rather than leveraged speculation. When ETFs were seeing consistent inflows, price found support even during broader market weakness. Once those inflows reversed, the market became more dependent on short-term traders who are quicker to exit. The recent rise in open interest while price fell is a classic sign that leverage is trying to do the work that spot demand should be doing. That rarely ends smoothly.
It is worth remembering that funding rates remaining elevated while price declines is usually not a sign of healthy conviction. It often reflects traders who are reluctant to accept that the short-term trend has changed. When those positions eventually get squeezed, the liquidations can accelerate the move lower and create the very conditions that force a longer reset.
Comparing the Current Sell-Off to Earlier Periods
The May-to-July decline offers a useful contrast. Selling then was more aggressive, with much higher daily realized losses. The current period has seen steadier but less intense distribution. That could mean the market is working through supply more orderly, or it could simply mean that the real pressure has not fully arrived yet. Both interpretations remain possible until we see how price behaves around the November 22 window.
Another difference is the presence of large ETF products that did not exist in earlier cycles. Their outflows introduce a new source of consistent selling pressure that was not a factor in previous corrections. When one product alone accounts for the bulk of the outflows, it becomes harder for smaller buyers to absorb the volume. That is a structural shift the market is still learning to navigate.
On-Chain Signals That Deserve Attention
Beyond the cost basis level, the growth in Bitcoin held between 70,000 and 75,000 dollars is notable. More than 230,000 coins moved into that band in a short window. Those buyers are now sitting closer to the current price and may act as a source of support if the market stabilizes. At the same time, the larger group of underwater holders between 75,000 and 80,000 dollars remains the bigger near-term concern. Their willingness to hold or sell will likely decide whether rallies stick or fade.
Realized loss data also paints a picture of controlled rather than panicked selling. An average loss of only one percent on recent transactions suggests many participants are still relatively close to their entry points. That can change quickly if price drops further, but for now it is a modestly constructive detail.
Possible Paths From Here
Two broad scenarios stand out. In the first, Bitcoin reclaims the short-term holder cost basis before or around November 22, ETF flows turn positive for several days, and leveraged positions begin to unwind more gradually. That path would support the idea that the current move is a standard correction within a larger uptrend. In the second scenario, price remains below the cost basis past the two-week mark, outflows continue or only briefly reverse, and another wave of long liquidations hits. History suggests that path could open the door to a deeper and more time-consuming reset.
Neither outcome is locked in. Markets have a way of surprising even careful observers. What feels useful about the current setup is that the key levels and flow data are relatively clear. Traders and longer-term holders can watch the same markers and adjust as new information arrives.
Why Spot Buying Still Matters Most
I have found that the healthiest Bitcoin advances usually begin when genuine spot demand returns and stays present for more than a few sessions. Leverage can amplify moves in both directions, but it rarely creates lasting support on its own. The recent period of ETF outflows has removed one of the most consistent sources of that spot demand. Until it returns, the market remains more vulnerable to the kind of leverage-driven swings we have seen over the past few weeks.
Corporate buying has also cooled. While one well-known holder continued adding a relatively small amount, the broader picture shows that treasury demand is no longer providing the same cushion it did earlier. That shift forces the market to rely more on individual and institutional ETF buyers, exactly the group that has been selling of late.
The Psychological Side of the Cost Basis Level
There is a practical reason the short-term holder cost basis often acts as a magnet. Many of those buyers are still close enough to their entry that the difference between a small loss and break-even feels meaningful. When price approaches that zone from below, the temptation to sell and move on can be strong. Only when enough of those holders decide the longer-term case remains intact does the selling pressure ease and allow price to move higher with less resistance.
That is why reclaiming and holding the 75,717 dollar area would be more than a technical event. It would signal that recent buyers are becoming more comfortable again. Until that happens, every rally risks meeting the same overhead supply.
Putting the Numbers in Perspective
A 2.22 billion dollar outflow over eight sessions is large by any recent standard. Yet it is still only a fraction of the total capital that has entered Bitcoin through ETFs since their launch. The question is not whether the products can absorb future demand, but whether the current wave of selling has further to run. Daily outflows have already slowed, which is a necessary first step. Three consecutive inflow sessions would be a stronger signal that the tide is turning.
Open interest expressed in Bitcoin terms rather than dollars helps remove some of the noise created by price changes themselves. The fact that it rose while price fell is a clean indication that positioning increased. Combined with funding rates that stayed elevated, the picture is one of traders who remain committed to the long side even as the market moves lower. That commitment can persist for a while, but it usually meets its limit when liquidations accelerate.
Looking Ahead Without Overconfidence
Markets rarely move in straight lines, and Bitcoin has a long history of testing patience before rewarding it. The current setup contains both cautionary and constructive elements. Heavy ETF outflows and rising leverage into weakness are clear reasons for caution. Contained realized losses and some accumulation in the 70,000 to 75,000 dollar range offer modest reasons for hope. The November 22 checkpoint simply gives a practical date against which to measure progress.
If price can climb back above the short-term cost basis and flows improve, the case for a standard correction strengthens. If those conditions are not met, the historical pattern of longer recoveries becomes more relevant. Either way, the data is available for anyone willing to watch it closely. In a market that often feels noisy, that clarity is useful.
For now, the focus remains on whether buyers will return in sufficient size before the two-week window closes. The answer will shape the tone of the weeks that follow. Bitcoin has faced similar tests before and eventually moved higher, but the path between here and there is rarely comfortable. Watching the cost basis, the ETF flows, and the behavior of leveraged traders offers the clearest way to track how this particular test is unfolding.
The coming days will show whether the recent selling has largely run its course or whether more time and lower prices are still required. That is the real story behind the November 22 date, and it is the one worth following closely.