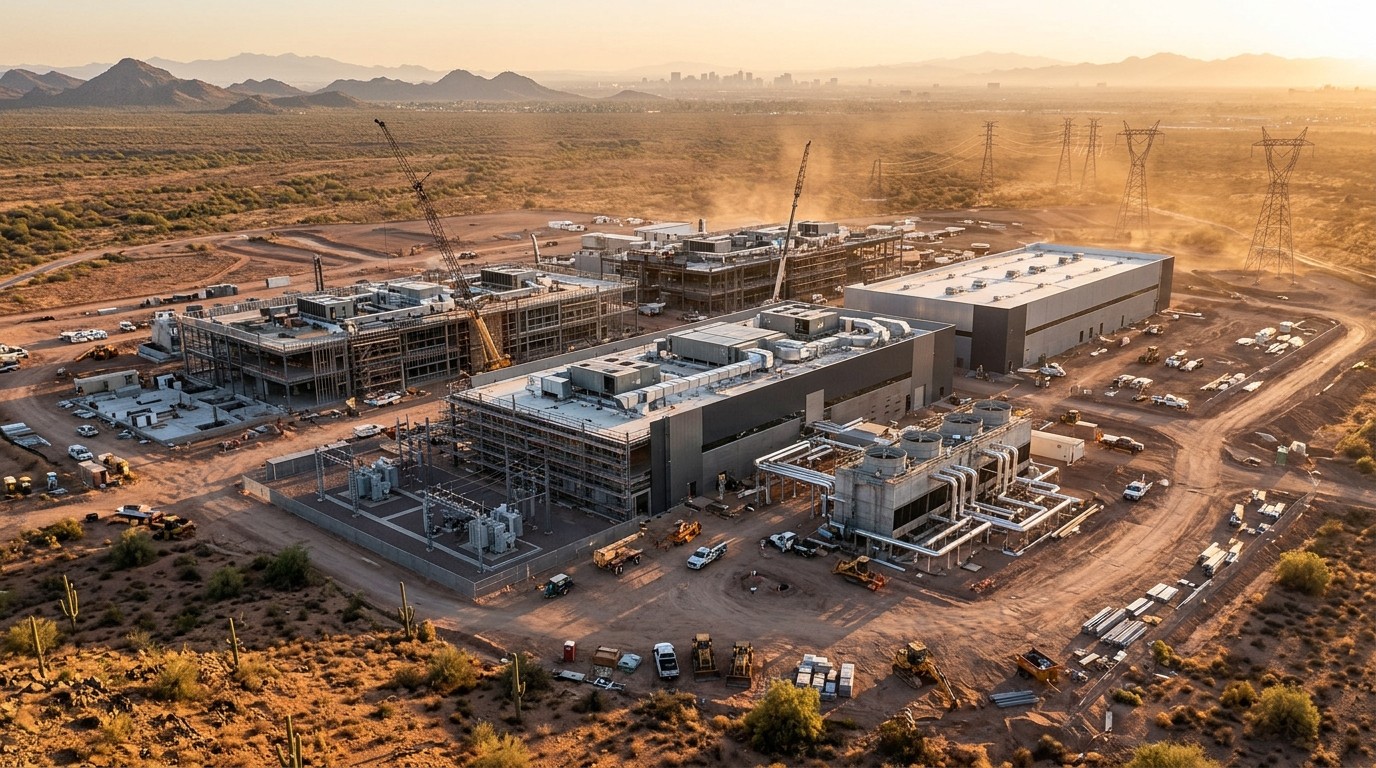

I’ve been watching the data center boom for a while now, and every time a big name announces another huge campus I catch myself wondering the same thing: can the power and water actually keep up? SpaceX’s latest plans in Arizona and Texas landed at a particularly interesting moment. Right after those midterm results flipped control in both states, the company still chose to push forward. That kind of confidence—or stubbornness, depending on how you look at it—immediately got markets talking.
Why SpaceX’s Timing Raised Eyebrows Across Wall Street
The announcement itself wasn’t shocking. Anyone following artificial intelligence knows the hunger for compute is still enormous. What surprised people was the political backdrop. Fresh Democratic victories in both states created an atmosphere of tighter scrutiny on energy-heavy projects. Yet SpaceX decided the projects still made sense. I’ve found that companies with deep pockets and long time horizons often move when others freeze. They bet that practical realities will eventually outweigh short-term political noise.
Arizona’s current governor has stopped short of a full stop on data centers. Tax incentives got suspended, sure, but the actual permitting machinery keeps running. That distinction matters more than the headlines suggest. In Texas the chatter is different. Industry people keep whispering that the current pause on new data centers might open up for a short window before the new administration settles in. If that happens, expect a rush of applications for air quality, construction, and on-site generation permits. Developers who move fast could lock in approvals that later become harder to obtain.
Political Headwinds Versus Real-World Constraints
Markets love a simple story: election results equal project delays. Reality is messier. Community pushback against data centers didn’t start on election night. Many towns have been arguing about water use and rising electricity bills for years. At the same time, plenty of local officials still welcome the jobs and tax base these facilities bring. The net effect is a patchwork of support and resistance rather than a clean political mandate.
Long-term demand for AI training and inference capacity keeps growing. That underlying pressure doesn’t care who sits in the governor’s mansion. Projects will continue, though the pace will probably slow to something more sustainable. I keep hearing the same refrain from people who actually build these things: the math still works. Companies can afford to solve electricity shortages, water recycling, and community concerns because the revenue potential remains so large.
Even the facilities that aren’t fully permitted yet are likely to get built. The economics of data centers give operators enough room to negotiate power deals, address water issues, and create local jobs. Solutions tend to appear when the numbers are this strong.
That kind of confidence isn’t pure optimism. It reflects the cold calculation that hyperscale operators and well-capitalized players can outlast temporary political friction. Still, not every announced megawatt will actually come online. Practical hurdles—permitting delays, weak tenant credit, developers who simply lack the experience—already filter out a large share of proposed capacity. One research note I read suggested roughly two-thirds of the pipeline faces serious realization risk for those exact reasons. Politics is only one variable among many.
The Resource Squeeze That Nobody Can Ignore
Data centers don’t just need land and fiber. They gulp electricity and water on a scale that strains local systems. SpaceX’s Arizona plans already triggered a petition signed by more than two thousand residents asking officials to deny permits. That kind of organized opposition forces conversations that politicians sometimes prefer to avoid. It’s easy to paint data centers as the villains driving up household power bills. The fuller picture is more nuanced.
In regions where the grid was never planned for sudden large loads, prices do climb. Inadequate forward-looking transmission investment is usually the real culprit. In places with better planning, the opposite can happen. Big industrial customers help spread the fixed costs of transmission infrastructure across more users. One transmission executive put it plainly: customers end up paying more for the absence of transmission than for the transmission itself. In parts of the Midwest, rates are actually set to fall next year partly because large loads improved the overall cost structure.
I’ve seen this dynamic play out in several states. When utilities and developers coordinate early, the addition of data centers can stabilize or even lower rates for everyone else. When they don’t, the pain shows up in residential bills and political blowback. SpaceX will have to navigate both scenarios depending on the exact sites it chooses.
Arizona’s Balancing Act on Incentives and Approvals
Arizona has become a preferred destination for data centers because of available land, relatively cool nights that help with cooling, and a history of business-friendly policies. The recent decision to pause certain tax credits changes the math for some developers, but it doesn’t kill projects that already pencil without those incentives. SpaceX appears to fall into that category. The company has the capital and the long-term vision to absorb higher costs if the strategic location still makes sense.
Local opposition focuses heavily on water. Arizona’s ongoing drought and population growth make every acre-foot a political issue. Modern data centers have gotten better at recycling and using treated wastewater, yet the perception lag remains strong. Residents see evaporative cooling towers and assume the worst. Operators who communicate early and transparently about closed-loop systems and water stewardship programs tend to face less resistance. Those who stay quiet invite the petitions.
Permitting itself remains the quieter battleground. Air quality permits, construction approvals, and interconnection studies all take time. A governor who isn’t actively blocking projects still sets the tone for how aggressively agencies process applications. SpaceX’s decision to move ahead suggests its internal models already account for longer timelines and higher compliance costs.
Texas and the Possible Permitting Window
Texas offers a different set of variables. The state’s competitive electricity market and abundant generation capacity have long attracted energy-intensive industries. The recent temporary pause on new data center approvals created uncertainty, yet it also created a potential scramble. If the pause lifts before the new governor’s team fully takes over, developers could file a concentrated wave of applications. Air permits, building permits, and on-site generation approvals would all move in parallel.
That kind of rush isn’t ideal for careful planning, but it is predictable human behavior. Companies hate uncertainty more than they hate higher costs. Locking in approvals during a narrow window can be rational even if the resulting projects face later challenges. I’ve watched similar windows open and close in other regulated industries. The winners are usually the teams that prepared their filings in advance and can move the moment the door cracks open.
Texas also has its own water and transmission questions. Some rural counties welcome the tax revenue. Others worry about strain on local aquifers and the need for expensive transmission upgrades. SpaceX’s scale means any single campus will be noticed. The company’s public profile guarantees that every local hearing will attract attention far beyond the county line.
Market Skepticism and the Reality of Project Pipelines
Whenever a high-profile company announces multi-billion-dollar infrastructure, stock watchers start running scenarios. Can these projects actually get built on schedule? Will power be available at the prices modeled in the original pitch decks? How much local opposition will delay groundbreaking? Those questions are fair. They are also incomplete.
A meaningful portion of announced U.S. data center capacity was always going to fall away for non-political reasons. Development timelines slip. Tenant credit profiles sometimes look weaker under closer inspection. Some developers simply lack the track record to raise the next tranche of financing. Politics gets the headlines, yet operational and financial filters do most of the actual screening. That perspective should calm some of the more dramatic market reactions.
At the same time, the projects that do move forward tend to be larger and better capitalized than the average. Hyperscale operators and well-funded newcomers can absorb cost overruns and timeline extensions that would sink smaller players. SpaceX sits in that stronger group. Its ability to self-fund or attract partners gives it options that pure real-estate developers lack.
Electricity Prices: Perception Versus Grid Economics
One of the stickiest talking points is the claim that data centers force household electricity rates higher. In some constrained markets that has happened. In others the opposite is true. Large, steady loads improve the utilization of existing transmission and generation assets. Fixed costs get spread across more kilowatt-hours. The result can be lower unit rates for everyone, including residential customers.
The difference usually comes down to planning. Utilities that anticipated industrial growth and invested early in transmission see data centers as rate stabilizers. Utilities caught flat-footed face congestion, higher wholesale prices, and angry customers. SpaceX’s projects will succeed more easily in the first category of markets. The company has every incentive to site campuses where the grid can actually support them without triggering political firestorms.
I keep coming back to a simple observation from transmission operators: the real cost to customers is often the transmission that never got built. Data centers that force the conversation about grid upgrades can end up benefiting the broader system even if the short-term politics look messy.
Water, Community Relations, and the Long Game
Water remains the emotional flashpoint in arid states. Petitions with thousands of signatures get attention. They also force operators to improve their messaging and their engineering. Closed-loop cooling, treated wastewater, and on-site recycling are no longer experimental. They are becoming table stakes for any serious project in water-stressed regions. Companies that treat community concerns as a public-relations problem rather than an engineering challenge tend to lose time and goodwill.
SpaceX has experience managing complex public interfaces on other projects. That institutional knowledge should help, yet every new location brings unique local dynamics. Listening sessions, transparent water-use data, and partnerships with local water districts can turn skeptics into cautious supporters. Ignoring those steps invites prolonged fights that raise costs and delay timelines.
Perhaps the most interesting aspect is how these local battles feed into national narratives about AI infrastructure. Every petition and every rate case becomes ammunition in broader debates about whether the United States can expand compute capacity fast enough to stay competitive. The tension between local resource limits and national strategic goals is not going away.
What Successful Projects Will Actually Look Like
The data centers that reach commercial operation in the next few years will share certain traits. They will sit in locations with credible power supply plans, not just optimistic interconnection queues. They will demonstrate measurable water stewardship rather than vague promises. They will engage local communities early instead of treating outreach as an afterthought. And they will be backed by balance sheets strong enough to ride out permitting delays and construction cost inflation.
SpaceX’s dual-state approach gives it portfolio diversification. Problems in one jurisdiction can be offset by progress in another. That flexibility is valuable when political winds shift. It also forces the company to maintain parallel regulatory and community strategies, which increases complexity but reduces single-point failure risk.
- Credible long-term power contracts or on-site generation options
- Transparent water-use reporting and recycling commitments
- Early and consistent local stakeholder engagement
- Financial capacity to absorb delays without project collapse
- Flexibility to adjust site plans as political conditions evolve
None of those factors guarantee success. They simply raise the odds. In a market where two-thirds of announced capacity may never materialize, raising the odds is the entire game.
The Bigger Picture for AI Infrastructure Investment
Zoom out and the SpaceX announcement is one data point in a much larger trend. Global demand for AI compute continues to outpace supply. That imbalance creates powerful incentives for capital to flow into new facilities even when local conditions look challenging. Capital is patient when the alternative is missing the next wave of technological growth.
Investors watching the sector should separate political theater from operational reality. Election results matter. So do interconnection queues, turbine delivery times, and transformer shortages. The companies that navigate all of those constraints simultaneously will capture the bulk of the economic value. Pure political narratives that ignore the engineering and financial filters tend to overstate near-term disruption.
I’ve found that the most useful mental model treats politics as a timing variable rather than a binary on-off switch. Projects get delayed, costs rise, designs change, but the underlying demand rarely disappears. SpaceX appears to be operating under that model. Whether the market ultimately rewards the bet will depend on execution details that are still years away.
Practical Lessons for Other Developers and Investors
Anyone evaluating similar projects can take a few practical notes. First, map the political calendar against the permitting timeline. Narrow windows can appear and disappear quickly. Second, treat community water and power concerns as design constraints from day one rather than problems to be managed later. Third, stress-test financial models against longer interconnection delays and higher compliance costs. Fourth, maintain optionality across multiple jurisdictions so that a single political shift does not strand capital.
Those steps sound obvious, yet many early-stage data center proposals still treat them as afterthoughts. The difference between a press release and an operating facility often comes down to how seriously those constraints were modeled at the beginning.
SpaceX’s decision to proceed in the current environment will be studied by other large operators. If the projects move forward relatively smoothly, it will reinforce the view that well-capitalized players can push through political headwinds. If they encounter prolonged delays or significant redesigns, the market will recalibrate its assumptions about timeline risk. Either outcome provides useful information.
Looking Ahead Without the Hype
The next twelve to eighteen months will reveal more than any announcement can. Permitting applications will either advance or stall. Local opposition will either intensify or find workable compromises. Power purchase agreements and interconnection studies will either confirm the original economics or force adjustments. Markets will watch those concrete milestones far more closely than the initial political reactions.
In the meantime, the underlying driver remains unchanged. Artificial intelligence workloads continue to expand. That expansion requires physical infrastructure. The companies willing to navigate messy local politics, constrained resources, and long lead times will determine how quickly that infrastructure appears. SpaceX has signaled it intends to be one of those companies. The real test is still ahead.
I keep returning to the same practical question: can the power and water actually keep up? The answer will vary by site, by utility, and by how creatively engineers and policymakers respond. The companies that treat those constraints as solvable design problems rather than immovable barriers are the ones most likely to turn ambitious announcements into operating assets. That is the story worth watching, far more than any single election cycle.
Data centers will keep getting built. The pace will fluctuate. The locations will shift. The political arguments will continue. Through all of it, the demand for compute capacity keeps rising. SpaceX’s latest move is simply the newest chapter in that longer story—one that mixes engineering ambition, local resource limits, and the inevitable friction of democratic decision-making. How that chapter ends will depend less on the headlines of the moment and more on the unglamorous work of permits, power lines, and water recycling systems that still have to be designed and approved.
For investors, policymakers, and communities alike, the useful posture is cautious curiosity rather than reflexive optimism or pessimism. The projects that succeed will be the ones that solve real constraints in real places. Everything else is noise. SpaceX has chosen to step into that noise. The coming years will show whether the company’s long-term vision can convert political uncertainty into operational reality.
That conversion process is rarely elegant. It involves public hearings, engineering studies, rate cases, and quiet negotiations with utilities and local officials. It also involves the steady pressure of AI demand that does not pause for election cycles. Balancing those forces is the actual work of building the next generation of digital infrastructure. SpaceX’s Arizona and Texas plans put that work on full display. Watching how it unfolds should prove more instructive than any single announcement or market reaction.
In the end, the data center story is a resource story as much as a technology story. Electricity, water, land, and political capital are all finite. Companies that allocate those resources carefully will build lasting assets. Those that treat them as afterthoughts will struggle. SpaceX appears to understand the distinction. Whether its specific projects succeed will depend on details still being worked out on the ground. The broader lesson for the sector is already clear: ambition must be matched by practical problem-solving, or the announcements remain just announcements.