
What happens when a painting that has stayed out of public view for half a century suddenly carries a $180 million price tag? That question sits at the center of the art world’s attention right now. Next week’s New York auctions are shaping up as one of the most closely watched tests of collector confidence in recent memory, and the numbers are hard to ignore.
The Scale of Next Week’s Auctions
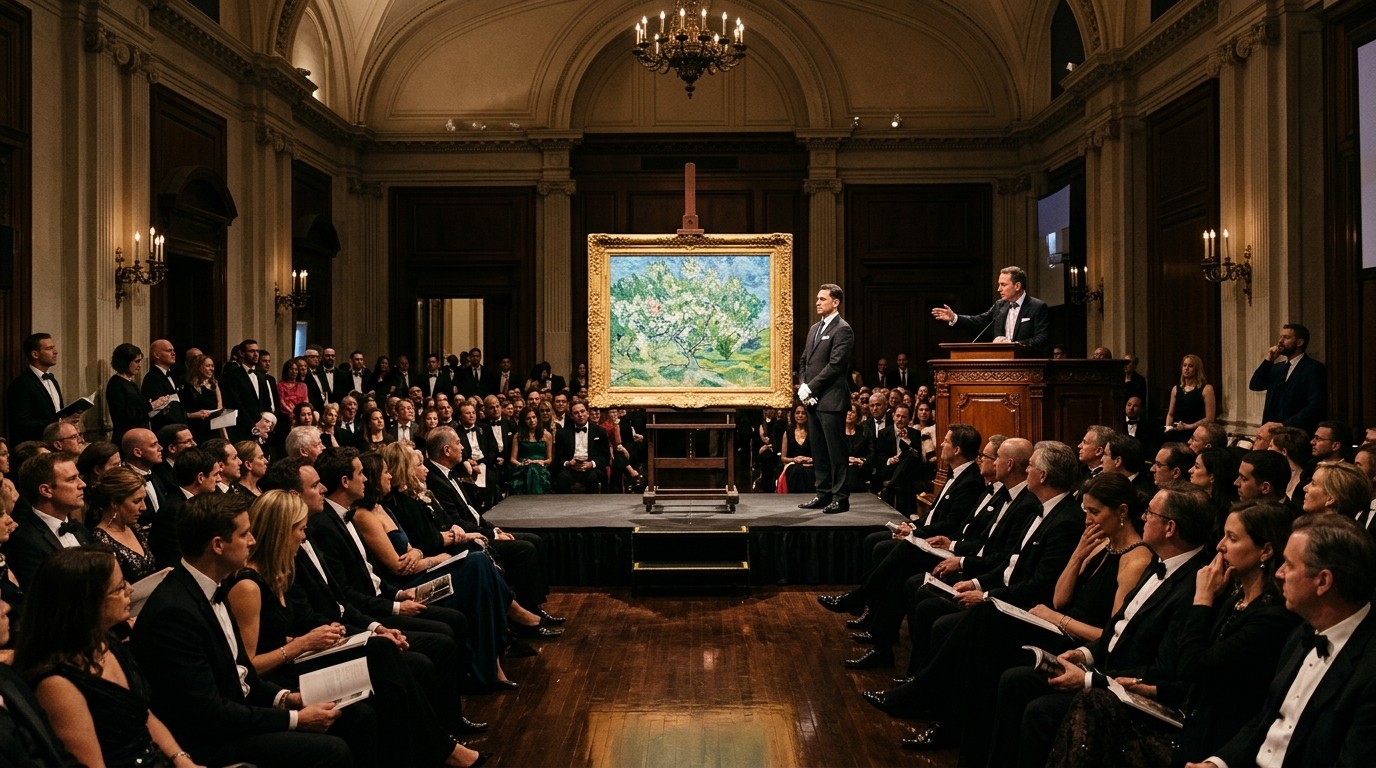
Industry forecasts put the combined total for the major houses somewhere around $2.4 billion. That figure would roughly match last year’s overall result. One house alone is projected to clear more than $1.1 billion, driven in large part by a single private collection estimated near $450 million. Inside that group sit two works that have already become the talk of the season: a Van Gogh landscape estimated at $180 million and a Cézanne figure piece carrying a $120 million estimate. Neither has appeared in public for roughly fifty years.
I’ve followed these November sales for years, and the concentration of fresh material feels different this time. When works of this caliber stay off the market for decades, their reappearance tends to reset expectations. Collectors who usually wait on the sidelines start paying closer attention. The question is whether that attention will translate into the kind of aggressive bidding that defined earlier peaks.
Why Blue-Chip Works Still Command Attention
At the highest level the market has always behaved a bit differently from the broader art trade. Serious buyers of Impressionist and Modern masterpieces tend to think in longer cycles. Short-term swings in equities or headlines about technology valuations rarely dictate their decisions the same way they might for mid-tier contemporary pieces. One senior auction executive put it simply: the chance to acquire a true masterpiece may come only once in a generation, and that rarity can outweigh what any stock index did last week.
That mindset helps explain why demand for the top tier has stayed relatively firm even during periods when overall sales softened. Blue-chip material has historically acted as a kind of store of value for ultra-high-net-worth individuals. When private wealth expands and equity markets deliver strong returns, more capital becomes available for these trophy works. The reverse can also hold, of course, but the lag is often longer and the response less dramatic than people outside the field expect.
There’s been enormous wealth creation and a lot of confidence in markets. It’s a global phenomenon.
Those words from a major auction house chief capture the prevailing mood among many dealers and advisors. Interest is no longer concentrated in the traditional Western centers alone. Buyers from Asia have been more active in recent seasons, and activity from the Middle East through Singapore has added another layer of competition. Europe and the United States remain core markets, yet the geographic spread of capital has widened the potential bidder pool for the most important lots.
Fresh Collections Change the Equation
One of the quieter strengths of this particular series of sales is the amount of material that has not traded publicly in decades. When a collection of this quality comes to market after long private ownership, it creates a sense of scarcity that pure secondary market offerings often lack. Buyers know they may not see comparable works again for many years. That knowledge can sharpen focus and, in the right conditions, support higher prices.
Bank of America research noted that auction sales in the first half of the year rose sharply compared with the prior period, with Impressionist and Modern categories leading the rebound. Improving liquidity combined with an unusual concentration of fresh private collections has created what one art services head described as a favorable backdrop. Cautious optimism remains the dominant phrase among professionals I speak with, but the tone is clearly more constructive than it was twelve or eighteen months ago.
Still, nobody is declaring a new boom. The market has learned from previous cycles. Participants remember periods when estimates ran ahead of actual demand and when speculative buying left some owners with works that later proved difficult to resell. The current environment feels more measured. Buyers appear willing to pay strong prices for exceptional quality, yet they remain selective. Works that fall short of the highest standard continue to face resistance.
What Collector Confidence Really Looks Like
Confidence in this context is not a simple yes-or-no proposition. It shows up in different ways across price levels and categories. At the very top, it can mean the willingness to compete for a once-in-a-generation picture even when broader economic signals are mixed. In the middle market it often appears as a preference for works with clear provenance and strong exhibition history. Across the board it reflects a belief that the best examples will hold value over long horizons.
Recent volatility in public markets and ongoing debate about technology valuations have not gone unnoticed. Yet many advisors report that their clients treat art acquisitions as long-term decisions rather than short-term trades. That distinction matters. When collectors approach a purchase with a multi-decade time frame, temporary market noise carries less weight. The opportunity cost of missing a rare work can feel greater than the risk of short-term price fluctuation.
I’ve noticed that conversations with collectors have shifted in tone over the past year. Earlier there was more hesitation and a stronger preference for waiting. Now the discussion more often centers on which works are truly special and how to position for them. That change does not guarantee every estimate will be met or exceeded, but it does suggest a healthier foundation than the market enjoyed during the softer periods of 2023 and 2024.
Geographic Shifts and New Sources of Demand
One of the more interesting developments has been the broader geographic base of interest. While New York remains the primary stage for these November sales, the capital supporting the bidding increasingly comes from multiple regions. Stronger participation from Asian collectors has been visible for several seasons. Activity linked to the Middle East and parts of Southeast Asia has also grown more consistent. European and American buyers remain essential, yet the competition for the very best lots has become more international.
This diversification can act as a stabilizing force. When demand rests on a wider set of economic conditions and cultural preferences, individual regional slowdowns carry less systemic risk. It also means that marketing efforts and private viewing schedules have grown more complex. Auction houses now invest significant resources in presenting works to clients across multiple continents before the public sales even begin.
In practical terms this wider net increases the chance that a major work will find a motivated buyer. It does not eliminate the possibility of a soft result, of course. Estimates still need to be realistic, and condition, provenance, and aesthetic quality continue to matter enormously. But the larger pool of potential underbidders changes the dynamics inside the saleroom.
Lessons from Recent Market Cycles
Looking back at the past few years offers useful perspective. After a period of rapid expansion, the market cooled. Sales volumes declined and some categories struggled more than others. The rebound that began this year has been uneven, with blue-chip Impressionist and Modern works recovering faster than many contemporary segments. That pattern is not unusual. Historically the highest-quality material has often led recoveries and proved more resilient during downturns.
What feels different now is the combination of improving liquidity and an unusually strong supply of fresh collections. When those two factors align, the conditions for healthy results improve. Still, professionals remain careful with their language. “Cautiously optimistic” appears far more often than any stronger claim. That restraint itself may be a positive sign. Overconfidence has preceded soft patches in the past.
Another lesson concerns the importance of transparency and realistic pricing. Works that arrive with stretched estimates or incomplete documentation tend to underperform. By contrast, pieces that are carefully researched, well presented, and priced with an eye toward actual demand often attract competitive bidding even in uncertain environments. The upcoming sales will test how well those principles have been applied to the headline lots.
The Role of Private Wealth Creation
Behind the auction totals sits a more fundamental driver: the growth of private wealth in recent years. Rising equity markets and entrepreneurial success have expanded the ranks of individuals and families capable of competing for eight- and nine-figure works. When that wealth feels secure, a portion of it often flows into tangible assets that combine aesthetic pleasure with potential long-term value retention.
Art occupies a particular place in that mix. Unlike purely financial instruments, a major painting or sculpture offers daily enjoyment and social signaling alongside any investment characteristics. For many collectors the emotional and cultural dimensions matter at least as much as the financial ones. That dual nature helps explain why demand can remain firm even when other markets experience turbulence.
At the same time, the link between wealth creation and art buying is not automatic. It depends on confidence, on the availability of compelling works, and on the broader cultural conversation around collecting. Periods of strong wealth growth that coincide with thin supply of top material can still produce muted auction results. The reverse can also occur. The current moment appears to combine both expanding wealth and meaningful supply, which is why so many observers are watching closely.
How Auction Houses Are Positioning Themselves
The major houses have spent months preparing for this week. Private viewings, carefully produced catalogues, and targeted outreach to key collectors form the backbone of the strategy. Guarantees and third-party arrangements also play a role in managing risk for both the sellers and the houses. Those financial structures have become more sophisticated over time, allowing larger consignments to reach the market with greater certainty for the owners.
Communication from the houses themselves has been measured. Executives speak of confidence at the highest end while acknowledging that the market remains selective. That balance feels appropriate. Overpromising can create expectations that are difficult to meet. Underplaying the strength of the material risks dampening interest. Finding the right tone is part of the craft of presenting these sales.
From my vantage point the presentation of the leading lots has been thoughtful. Emphasis has been placed on rarity, historical importance, and the long private ownership that kept the works out of circulation. Those narrative elements matter. Collectors respond not only to visual impact but also to the story that accompanies a work. A painting that has remained unseen for fifty years carries an aura that a frequently traded piece rarely matches.
Potential Risks That Still Exist
No market test is free of risk. If the headline works fail to meet their estimates or sell only after prolonged bidding that falls short of expectations, the narrative could shift quickly. Broader economic uncertainty, changes in tax policy, or unexpected geopolitical developments could also influence sentiment. Art markets do not operate in isolation from the rest of the financial world, even if the correlation is imperfect and often lagged.
There is also the perennial question of depth. Strong results for a handful of masterpieces do not automatically lift the rest of the market. Mid-level works can still struggle even when the top end performs well. Observers will look beyond the record headlines to see how the broader offerings fare. Healthy results across a wider range of lots would signal more robust confidence than a few spectacular prices alone.
Liquidity remains another consideration. Buying a major work is one step. Knowing that a comparable piece could be sold in the future without excessive friction is another. Markets function better when participants believe exit opportunities exist. The current rebound has improved that perception, yet memories of thinner trading periods linger.
What Success Would Look Like
A successful week would not require every lot to exceed its high estimate. Solid sell-through rates, competitive bidding on the most important works, and a sense that quality was rewarded would already constitute a positive outcome. If the Van Gogh and the Cézanne find buyers near or above their estimates, the psychological impact would be significant. Those results would reinforce the idea that exceptional material continues to attract capital even in a complex environment.
Beyond the numbers, the tone of the sales matters. Energetic bidding, active participation from multiple regions, and a general feeling of engagement would support the cautiously optimistic outlook that many professionals currently hold. Conversely, quiet rooms and lots that struggle to open could prompt a more restrained assessment of the near-term outlook.
I expect the results to fall somewhere between those extremes. The quality of the material is high enough to generate genuine interest. The estimates, while ambitious, appear grounded in recent comparable sales and the rarity of the works. Whether that combination produces standout prices or simply solid ones will become clear in the coming days.
Broader Implications for Collectors and Advisors
For collectors the week offers a reminder of how important timing and preparation can be. Opportunities at this level do not appear on a regular schedule. When they do, the collectors who have done their research, clarified their priorities, and maintained relationships with advisors and dealers are best positioned to act. Impulse buying at these price levels is rare and often regretted.
Advisors face their own set of considerations. Helping clients evaluate whether a particular work fits long-term goals, assessing condition and provenance thoroughly, and managing the logistics of bidding or private negotiation all require careful attention. The emotional intensity that can surround major sales sometimes complicates rational decision-making. Experienced counsel helps keep the focus on fundamentals.
There is also a longer-term dimension. Strong results for blue-chip works tend to reinforce the category’s status as a core holding for certain collectors. Softer results can prompt questions about valuation and future liquidity. Either outcome will influence how portfolios are discussed in the months ahead.
Looking Past the Headlines
It is easy to become absorbed by the largest estimates and the most famous names. Those stories drive coverage and conversation for good reason. Yet the health of the market depends on more than a few trophy lots. The performance of solid but less spectacular works, the level of private sales activity surrounding the public auctions, and the willingness of new collectors to enter the field all contribute to a fuller picture.
In that sense next week represents both a test and an opportunity. The test is whether collector confidence is strong enough to support ambitious estimates for rare material. The opportunity lies in the chance for the market to demonstrate resilience and depth after a period of adjustment. How that balance resolves will shape discussions well into the following year.
Personally I find these moments illuminating. They reveal how different participants weigh risk, rarity, and long-term value. They also show the continuing power of exceptional works to capture attention across cultures and generations. A painting created more than a century ago can still stop people in their tracks and prompt serious financial commitments. That capacity remains one of the more remarkable features of the art market.
Final Thoughts Before the Sales Begin
As the salerooms prepare to open, the atmosphere mixes anticipation with the usual undercurrent of uncertainty that accompanies any major auction series. The material on offer is strong. The estimates are substantial. The global pool of potential buyers appears engaged. Those ingredients create the conditions for meaningful results, yet nothing is guaranteed until the hammer falls.
Whatever the final totals, the week will provide useful data points about the current state of collector confidence. In an environment where wealth has expanded and quality material has become available, the response of the market will say a great deal about how participants view the intersection of art, capital, and long-term value. That information will be valuable far beyond the next few days of bidding.
For now the focus remains on the works themselves. A landscape that has remained private for half a century carries its own quiet drama. So does a figure composition of comparable rarity. Their appearance on the public stage after so many years is itself a notable event. The prices they achieve will simply add another chapter to already long stories.
In the end the art market has always moved between periods of exuberance and caution. The current moment feels closer to measured confidence than to either extreme. Whether that assessment holds after the sales conclude is the question everyone in the field is waiting to answer. The coming days will supply the evidence.