
Have you noticed how quickly the gold market can shift when central bankers start talking tough? Last week’s inflation numbers landed, a few key voices from the Federal Reserve spoke up, and suddenly the whole tone changed. Gold, which had been holding its ground for months, began sliding again. It is not the first time this has happened, and it will not be the last, but the speed of the move still catches people off guard.
Why Gold Is Feeling the Heat Right Now
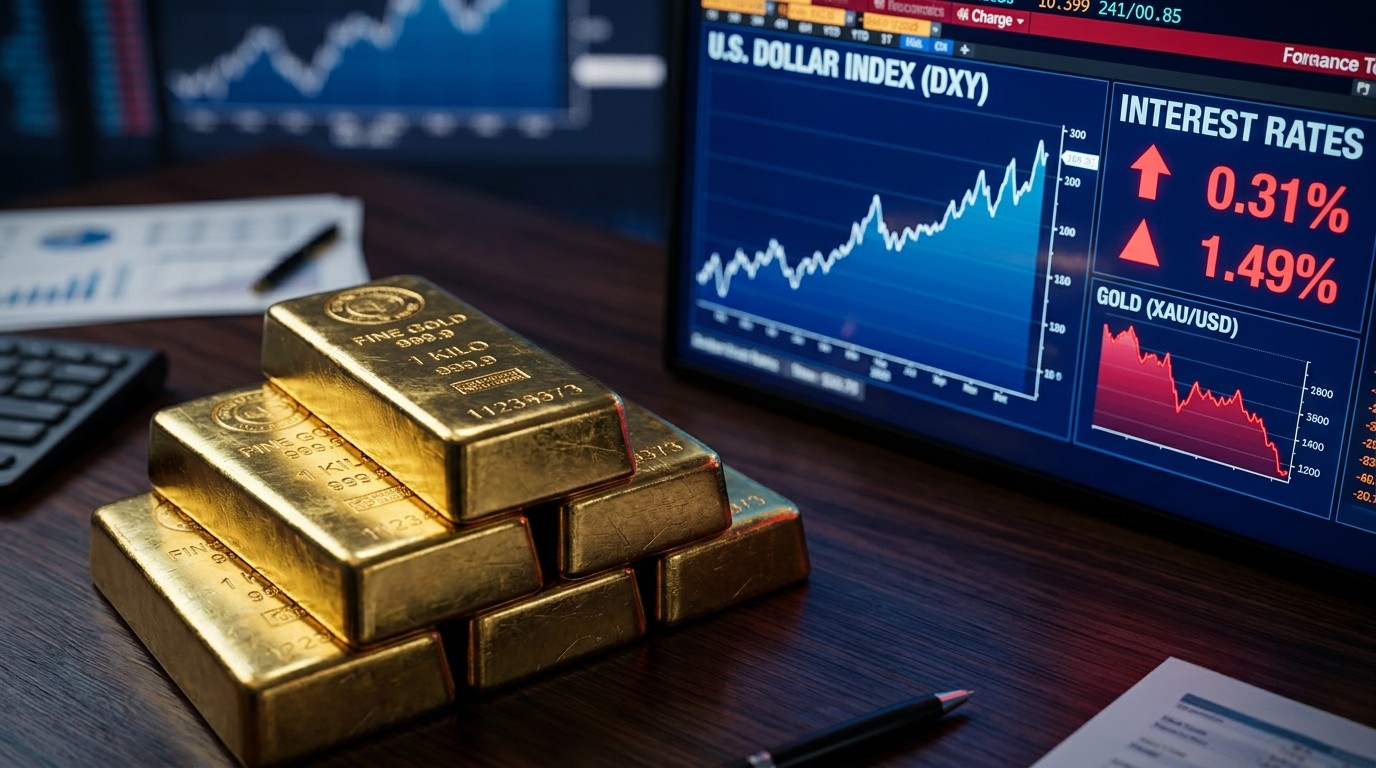
The main force pushing prices lower is simple on the surface and a bit more layered once you dig in. Markets now put the chance of another interest-rate increase in December at nearly 90 percent. Some traders have even started pricing in the possibility of a half-point move rather than the usual quarter. That kind of shift does not stay contained inside interest-rate futures. It spills straight into the dollar and into bond yields, and both of those matter a great deal for gold.
Because gold is priced in dollars, a stronger greenback makes the metal more expensive for anyone holding other currencies. At the same time, higher Treasury yields raise the opportunity cost of sitting on an asset that pays no interest. Real rates climb, and the metal starts looking less attractive relative to cash or bonds. I have watched this pattern play out enough times to know it rarely reverses overnight.
The Hawkish Turn After Inflation Data
October inflation figures came in, and several Federal Reserve officials wasted little time delivering firmer messages. New York Fed President John Williams was among those who sounded notably cautious about declaring victory too soon. Markets heard the tone clearly. The probability of a December hike jumped, and the dollar index, which tracks the greenback against a basket of six major currencies, pushed to a 19-month intraday high by Friday. Ten-year Treasury yields, meanwhile, hovered near levels last seen back in 2007.
That combination is tough for gold. Elevated yields make holding bullion feel more expensive in relative terms. A strong dollar raises the cost for international buyers. Both forces work in the same direction, and they have been working hard lately. One market participant put it bluntly:
The real rates are really impacting gold. Gold is also a risk-on asset where clients have to liquidate. It’s liquid.
– Head of Singapore Branch, Chief Investment Officer Asia
Liquidity is a double-edged sword. When investors need cash or want to reduce exposure, gold is easy to sell. That ease can amplify downward moves once the selling starts.
Near-Term Resistance Versus Longer-Term Optimism
Most analysts I follow agree that gold lacks an immediate catalyst strong enough to push it back above the 4,000-dollar mark in the next few weeks. The path of least resistance for now points sideways to slightly lower. Yet the same people who sound cautious about the short term often sound far more constructive once the conversation stretches out to 12 or 24 months.
One major investment bank recently projected that gold could reach 4,650 dollars per ounce by the end of next year. That would represent nearly a 20 percent rise from current levels. Those kinds of forecasts do not appear out of thin air. They rest on a handful of structural supports that are still very much in place even while the near-term pressure builds.
Oil Prices and the Quiet Support for Gold
One of the quieter but important factors is the expected path of oil. The International Energy Agency noted that the global oil market is set to return to a supply surplus in the fourth quarter of this year. Lower oil prices would ease dollar liquidity pressures on oil-importing countries. Those nations would face less need to sell gold reserves simply to raise the dollars required for expensive crude. Reduced selling pressure from that channel can matter more than many people realize.
In my view this is one of those background forces that rarely makes headlines yet steadily removes a source of supply from the market. When fewer countries feel forced to liquidate metal to fund energy imports, the overall balance tilts a little more in gold’s favor over time.
Fiscal Gridlock and the Dollar’s Longer Path
Another element worth watching is the political landscape in the United States after the midterm elections. Gridlock tends to limit large new spending packages. Over time that can pull Treasury yields and the dollar lower, creating a more supportive environment for gold. At the same time, the sheer size of outstanding government debt and ongoing fiscal deficits continue to raise quiet questions about the long-term creditworthiness of dollar-denominated assets.
Those concerns do not reverse a strong dollar in a single week, but they accumulate. Central banks around the world have already been diversifying reserves for years. That process does not stop just because yields spiked for a few sessions. One market veteran summed up the longer view this way:
There’s de-dollarization, which is attractive for gold. Widening fiscal deficits, but central banks continue to be buyers. Even if it chops around a bit for the next month or so, I expect a strong finish to the year and a strong start next year.
– Founder and President of an investment firm
Central-bank buying has been a steady undercurrent. Official sector demand does not swing as wildly as private investment flows, and that consistency provides a floor that private investors sometimes overlook in the heat of a short-term sell-off.
Real Rates Still Dominate the Conversation
If there is one concept that keeps coming up in every serious discussion of gold right now, it is real rates. When inflation-adjusted yields rise, gold tends to struggle. When they fall, the metal usually finds its footing. The recent hawkish messaging has pushed real rates higher, and the market is responding exactly as textbooks would predict.
Yet real rates are not static. They move with both nominal yields and inflation expectations. Should inflation cool faster than the market currently anticipates, or should growth concerns resurface, those real rates could ease again. That possibility is what keeps longer-term bulls from abandoning the metal even while the short-term tape looks soft.
What the Next Few Months Could Look Like
Near-term, the consensus seems to be that gold will have a hard time reclaiming 4,000 dollars without a clear shift in the rate outlook. Resistance is real. Liquidity is high, so any further disappointment on the inflation front or another firm speech from a Fed official can still produce additional downside.
At the same time, the structural story has not disappeared. Central-bank purchases continue. De-dollarization trends remain gradual but persistent. Fiscal deficits show little sign of shrinking in a meaningful way. Oil markets may soon move into surplus, reducing one source of potential gold selling. And post-election gridlock could eventually limit the scale of new fiscal stimulus that would otherwise keep yields elevated.
I find it useful to separate the tactical picture from the strategic one. Tactically, the metal is under pressure and may remain so for a few more weeks or even a couple of months. Strategically, the setup still points toward higher prices over a one-to-two-year horizon. That tension is what makes the current environment interesting rather than simply discouraging.
How Investors Are Positioning Around the Move
Some investors have chosen to reduce exposure while the rate path remains uncertain. Others are treating the pullback as an opportunity to add on weakness, especially those with longer time horizons. The second group often points to the same factors already mentioned: official-sector demand, fiscal concerns, and the eventual peaking of real rates.
There is no single correct answer. Risk tolerance, investment horizon, and overall portfolio construction all matter. What does seem consistent is that few serious participants expect gold to remain permanently capped by the current bout of dollar strength and yield pressure. Markets have a way of looking past the immediate noise once the underlying drivers begin to shift.
The Role of Opportunity Cost in Everyday Terms
Sometimes it helps to strip the jargon away. Holding gold means forgoing the interest you could earn on a Treasury bill or a money-market fund. When those rates climb, the decision to own the metal becomes more expensive in pure opportunity-cost terms. That is the core of the current pressure. It is not that gold has suddenly become less useful as a store of value or a hedge against extreme outcomes. It is simply that the alternative of holding cash or bonds has become more rewarding for the moment.
Once those alternative yields start to look less attractive again, the calculation flips. History suggests that flip can arrive faster than many expect once the Federal Reserve signals that the hiking cycle is truly complete. Until then, patience is required.
Looking Beyond the Immediate Noise
Markets love to focus on the next data release or the next speech. That focus is understandable. Yet the bigger forces shaping gold’s path over the coming years are slower-moving. Swelling public debt, the gradual diversification of global reserves, and the long-term credibility of major fiat currencies do not reverse course because one inflation print came in hotter than expected.
Those slower forces are still operating in the background. They help explain why longer-term price targets from major houses remain well above current levels even while the short-term tape looks soft. In my experience, the best opportunities often appear when the near-term story and the longer-term story diverge. We may be living through one of those periods right now.
Gold has already proven it can absorb rate-hike cycles and still reach new highs once the cycle turns. The question is not whether that pattern can repeat, but how long the current pressure lasts and how investors choose to position themselves while they wait. For those willing to look past the next few weeks, the setup still contains more constructive elements than the recent price action alone would suggest.
The dollar’s strength and the climb in yields have done their work. They have raised the bar for gold in the short run. Yet the same forces that created this pressure are also the ones that eventually reverse. When they do, the metal that looks heavy today often starts looking lighter again. That is the part of the story worth keeping in mind even while the headlines focus on the latest dip.
Central banks continue to buy. Fiscal conditions remain challenging. Oil markets may soon ease one source of selling pressure. And political gridlock could eventually limit the scale of new stimulus that would otherwise keep real rates elevated. None of these factors guarantee a straight-line move higher, but together they form a foundation that has supported gold through previous periods of short-term weakness.
Perhaps the most interesting aspect is how little the longer-term narrative has actually changed despite the recent price action. The metal is still viewed by many as a hedge against currency debasement and geopolitical uncertainty. Those roles do not disappear simply because the Federal Reserve is sounding more cautious for a few weeks. They remain part of the fundamental case even while the technical picture looks challenging.
Investors who can separate the noise of the next FOMC meeting from the slower trends in debt, reserves, and real rates may find the current environment more useful than it first appears. Pullbacks of this nature have historically offered better entry points for those with multi-year horizons. Whether this episode follows the same pattern remains to be seen, but the ingredients for a recovery are still present once the rate outlook begins to stabilize.
In the end, gold rarely moves in a straight line. It responds to real rates, to the dollar, to liquidity conditions, and to shifts in official-sector demand. Right now those factors are aligned against it. That alignment will not last forever. When it begins to loosen, the metal that is under pressure today will likely find its footing again. Until then, the market will keep testing how much further prices can fall before the longer-term supports reassert themselves.
The conversation around gold is always more nuanced than a single week of price action suggests. Rising rate-hike odds and a stronger dollar explain the recent decline clearly enough. The more lasting supports explain why many still expect the metal to trade higher over the next couple of years. Holding both ideas at once is the practical way to navigate the current environment without getting lost in either the short-term pessimism or the long-term optimism alone.