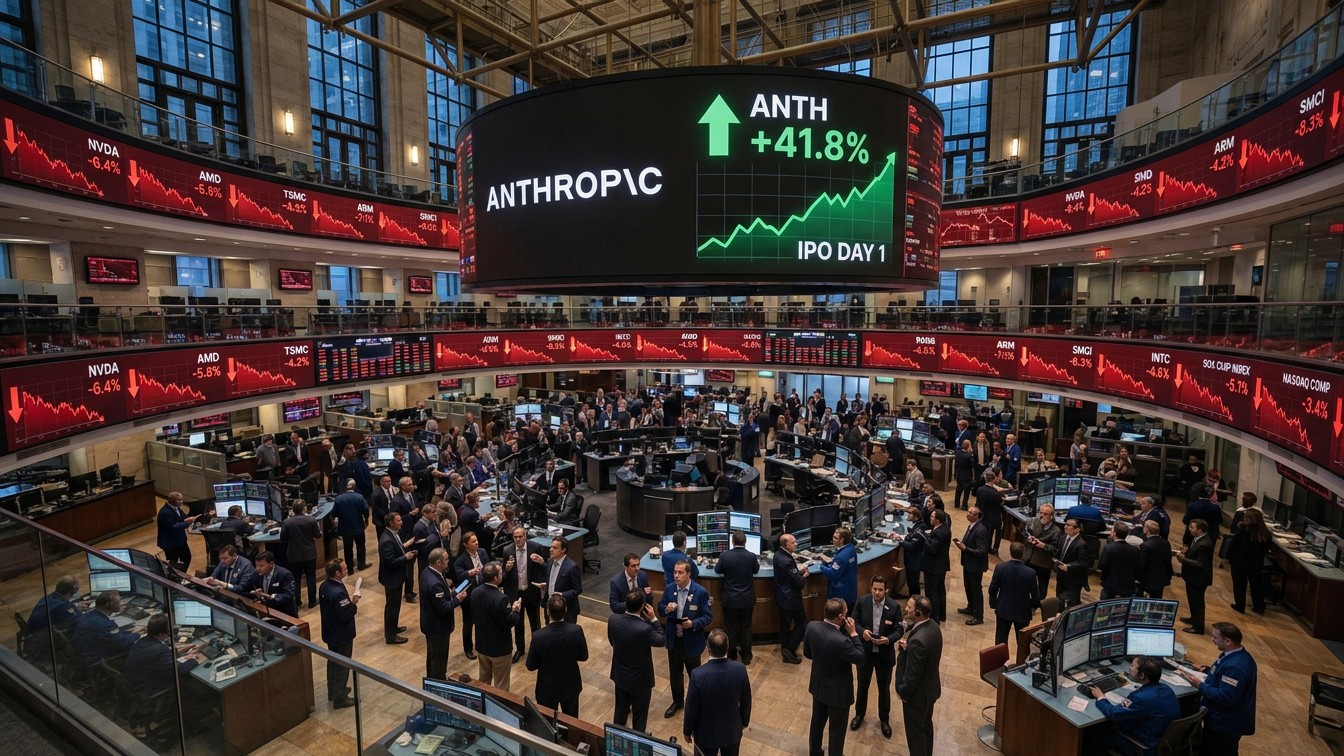

I kept refreshing the quote page Thursday afternoon thinking the numbers had to be wrong. Anthropic had just priced the largest IPO in U.S. history, the stock was ripping higher, and somehow the entire AI complex was getting crushed. Nasdaq off more than two percent, S&P sliding hard, AMD in freefall. It felt like watching a fireworks show while the neighborhood burned. Something important shifted under the surface, and I have been trying to unpack it ever since.
Why A Record Breaking Debut Still Could Not Save The AI Trade
Investors had treated the Anthropic listing as a potential clearing event. After months of choppy action, an espionage scare around a major chip name, and growing nervousness about export rules to Asia, the hope was that a clean, massive public debut would inject fresh confidence. Capital would rotate back into the theme. Animal spirits would return. Instead the opposite happened. The stock itself closed up roughly seventeen percent from its IPO price and the company raised more than eighty-one billion dollars, yet almost every related name finished in the red.
That disconnect is the real story. A company can succeed spectacularly on its own while the broader trade that supports it starts to crack. I have seen versions of this before, but rarely with so much capital and so many expectations concentrated in one single event.
The Price War Nobody Wanted To Talk About
One of the quieter but more damaging factors sits in the competitive dynamics between the two leading frontier labs. Aggressive pricing has become the new normal. When two companies race to undercut each other on model access, the immediate result is faster adoption. The longer-term result is thinner margins and larger combined losses.
Recent sequential numbers tell the tale clearly. Combined revenue growth for the pair slowed from roughly seventy-five percent in the second quarter to about forty-eight percent in the third. At the same time the combined losses expanded from around seven point nine billion to roughly eight point four billion. Those are not the kind of figures that make long-term capital allocators sleep well at night. I keep coming back to that gap between top-line momentum and bottom-line reality. It is the sort of tension that eventually forces a reckoning.
You could still make money in a tough year. You just needed the right combination of longs and shorts.
– Veteran portfolio manager describing the current environment
That observation feels especially relevant right now. Blind buying of anything with an AI label no longer works the way it did twelve or eighteen months ago. The market is demanding more discrimination.
Export Control Shadows And Short Seller Reports
Layered on top of the competitive pressure came fresh headlines about chips and China. A short-seller report claimed that certain firmware associated with a major chip designer had appeared inside companies on U.S. restricted lists. The stock in question dropped more than seven percent on the day. The company stated it complies with the law, but the market did not wait for the full investigation. Meanwhile congressional documents showed that a sub-agency had approved the sale of hundreds of thousands of advanced AI chips to Chinese entities in earlier periods. That disclosure immediately raised the possibility of tighter future controls and slower Asia-related revenue for the entire semiconductor complex.
These are not abstract policy debates. They hit order books and guidance numbers. When investors start modeling lower export volumes, the valuation multiples that once seemed reasonable suddenly look stretched. I noticed several large holders quietly reducing exposure to the more levered names even while the IPO was still celebrating its first-day gains.
Neoclouds And The Outer Edges Of The Trade
The most visible pain showed up in the so-called neoclouds—the specialized, often highly leveraged providers of AI-specific computing capacity. One of the larger names in that group closed down more than six percent. These companies sit further out on the risk curve. Their business models depend on sustained demand for training and inference clusters, continuous access to the latest silicon, and financing markets that remain open and reasonably priced. When confidence dips, they feel it first and hardest.
Hyperscalers, by contrast, held up a little better though still finished lower. Their diversified cash flows and fortress balance sheets give them more room to absorb short-term uncertainty. Even so, the fact that the perceived safer AI bets also declined tells you the selling pressure was broad rather than selective.
A Rare Bright Spot In Cybersecurity
Not everything related to artificial intelligence moved lower. Cybersecurity names continued their relative strength. Two of the larger pure-plays both closed higher. The logic is straightforward. As AI systems proliferate across software stacks, they also introduce new classes of vulnerabilities. Attackers move quickly. Defenders scramble. Budgets follow. In a market that is suddenly more discriminating, security has become one of the cleaner ways to stay exposed to the theme without taking on the full valuation risk of the frontier model builders or the leveraged infrastructure providers.
I have spoken with several risk managers over the past week who are actively shifting a portion of their AI allocation into this corner of the market. It is not a perfect hedge, but it is a rational response to the current uncertainty.
What The Next Few Sessions Could Reveal
Trading desks are already looking past the first-day pop. Friday is being described as a wild-card session. It could produce a final flush that washes out remaining weak hands, or it could simply leave the market stuck in a high-volatility no-man’s-land. The more meaningful test arrives Monday when listed options on the new stock begin trading. Retail participation often shows up most clearly in the options market. Heavy call buying would signal continued confidence. Heavy put activity or simply muted volume would suggest the opposite.
One experienced market technician put it plainly: if people think the stock is going higher they will buy shares, but retail especially will buy calls. The options open will give a cleaner read on whether the broader AI narrative still has retail support or whether that support has started to crack.
Strategic Positioning In A Higher-Tension Market
Several managers I follow have shifted from a pure long-only stance to a more balanced long-short approach inside the sector. They remain constructive on the multi-year adoption curve for generative AI, yet they acknowledge that the path will be far less linear than the 2023-2024 advance. The comparison some of them draw is to the second half of 2022, when the major indices suffered sharp declines yet selective portfolios still generated positive returns through careful pairing of longs and shorts.
That mindset feels appropriate. Capital spending by the large cloud providers remains robust. The technology itself continues to improve at a remarkable pace. None of that has changed. What has changed is the willingness of the market to pay any price for exposure. Valuation discipline is back. Balance-sheet quality matters again. Competitive intensity is being scrutinized rather than ignored.
- Focus on companies with clear paths to positive free cash flow within a reasonable horizon
- Prefer diversified platforms over pure-play infrastructure names carrying heavy debt loads
- Watch export-control developments closely; they can alter demand forecasts overnight
- Consider cybersecurity as a higher-conviction way to stay inside the AI ecosystem
- Use options markets and institutional flow data as real-time sentiment gauges rather than relying solely on price action
None of these points is revolutionary. They simply reflect a market that has moved from exuberance into a more adult phase. I have found that the investors who adapt fastest to that shift tend to protect capital better when volatility spikes.
The Longer View Still Holds
It is easy to get lost in the daily tape and forget the larger picture. Generative AI remains one of the most significant technological shifts of the past several decades. The capital already committed by the largest technology companies runs into the hundreds of billions. Training runs continue to scale. New use cases appear almost weekly across enterprise software, scientific research, and creative industries. Those structural forces have not disappeared simply because one trading session disappointed.
What the Anthropic debut revealed is that the market now wants proof of durable economics alongside the growth story. Revenue acceleration alone is no longer enough when losses are still expanding and competitive pricing pressure remains intense. That is a healthy evolution, even if it feels uncomfortable in the moment.
In my own work I have started weighting more heavily toward the picks-and-shovels providers that sit closer to actual cash flow generation and further from pure model development risk. I have also reduced exposure to the most levered infrastructure plays until financing conditions and demand visibility improve. These are not permanent judgments. They are adjustments to the current risk environment.
Reading The Institutional Tea Leaves
Institutional positioning data over the coming weeks will matter. Large funds that participated in the IPO allocation process will have lock-up considerations and performance pressures. Some will choose to take partial profits quickly. Others will add on any meaningful pullback. The balance between those two camps will influence price discovery more than any single headline.
At the same time, the options market will begin providing daily information about implied volatility and skew. Elevated implied vols after the first week of trading would signal that participants still expect large swings. A rapid decline in implied volatility would suggest the market is beginning to digest the listing and move on.
I plan to watch both the equity volume and the options open interest carefully. Together they form a more complete picture than price alone.
Lessons From Previous Technology Cycles
Every major technology wave eventually moves from a phase of indiscriminate buying into a phase of differentiation. The internet boom of the late 1990s, the smartphone and cloud build-out of the 2010s, and now the generative AI build-out all follow versions of the same pattern. Early winners can still become long-term compounders, but the set of winners narrows and the valuation gap between leaders and laggards widens.
The current moment feels like the early stages of that differentiation. Companies that can demonstrate pricing power, efficient capital allocation, and clear customer retention will likely be rewarded. Those that rely primarily on narrative and continuous external funding will face a harder road. That is not a bearish statement about the technology. It is a realistic statement about how public markets eventually price risk.
Perhaps the most interesting aspect is how quickly sentiment can pivot. Only a few weeks ago many desks were still treating every AI-related dip as a buying opportunity. Now the same desks are asking harder questions about unit economics and competitive intensity. That shift itself is useful information.
Practical Steps For Portfolio Construction
For investors who remain constructive on the multi-year story, the practical response is not to abandon the theme but to refine exposure. Concentration risk has become more visible. A portfolio that was once happy to own a basket of AI names may now prefer a smaller number of higher-conviction positions paired with explicit hedges or short positions in the weaker names.
Liquidity also deserves more attention. Some of the neocloud and secondary infrastructure names trade with thinner order books. When volatility rises, those thinner books can produce exaggerated moves in both directions. Position sizing needs to respect that reality.
Finally, time horizon matters more than ever. Traders focused on the next few sessions will face a different set of risks than investors focused on the next few years. Mixing the two mindsets is a common source of underperformance. Clarity about which game one is playing helps avoid costly mistakes.
Where Confidence Could Return
Several catalysts could help restore broader confidence. Greater regulatory clarity around export rules would remove one source of uncertainty. Evidence that the pricing war is stabilizing and that unit economics are improving would address the core profitability concern. Continued strong capital expenditure guidance from the largest cloud providers would reinforce the demand side of the equation. Any one of those developments could shift the tone. A combination of them would likely produce a more durable rebound.
Until then the market appears content to remain selective. The successful IPO proved that capital is still available for high-quality AI stories. It also proved that a single successful listing is no longer enough to lift the entire complex. That distinction is important. It suggests the next phase of the AI trade will be won by companies that can deliver both technological leadership and financial discipline.
I came away from Thursday’s session with a clearer sense of the market’s current priorities. Growth still matters. Narrative still matters. But durability of margins and balance-sheet resilience matter more than they did six months ago. Adjusting to that new weighting is the practical task facing every portfolio that wants to stay involved in the theme without taking unnecessary risk.
The Anthropic debut will be remembered as a landmark capital markets event. Whether it also marks the beginning of a more mature and selective AI market remains to be seen. The evidence so far points in that direction. The next few weeks of trading, options activity, and corporate commentary will tell us how lasting the shift proves to be.
For now the message from the tape is straightforward. Success at the company level no longer automatically translates into success at the sector level. Investors who internalize that distinction and position accordingly will be better prepared for whatever comes next. The technology remains transformative. The market’s willingness to pay for it has simply become more conditional. That is not the end of the story. It is the start of a more interesting chapter.
Looking across the full set of signals—the price war data, the export headlines, the neocloud weakness, the relative strength in cybersecurity, and the upcoming options open—I see a market in transition rather than a market in retreat. Transitions create opportunity for those willing to do the work of differentiation. They punish those who continue to treat every name as interchangeable. The record IPO gave us a clear data point. The broader sell-off gave us another. Reading both together is the real work of the moment.
In the end the question is not whether artificial intelligence will reshape industries. That outcome looks increasingly inevitable. The question is which public companies will capture durable economic value along the way and at what valuations investors will be willing to pay. Thursday’s session offered an early, imperfect answer. The coming sessions will refine it further. Staying attentive to the evolving evidence, rather than clinging to earlier assumptions, remains the most reliable approach I know.