

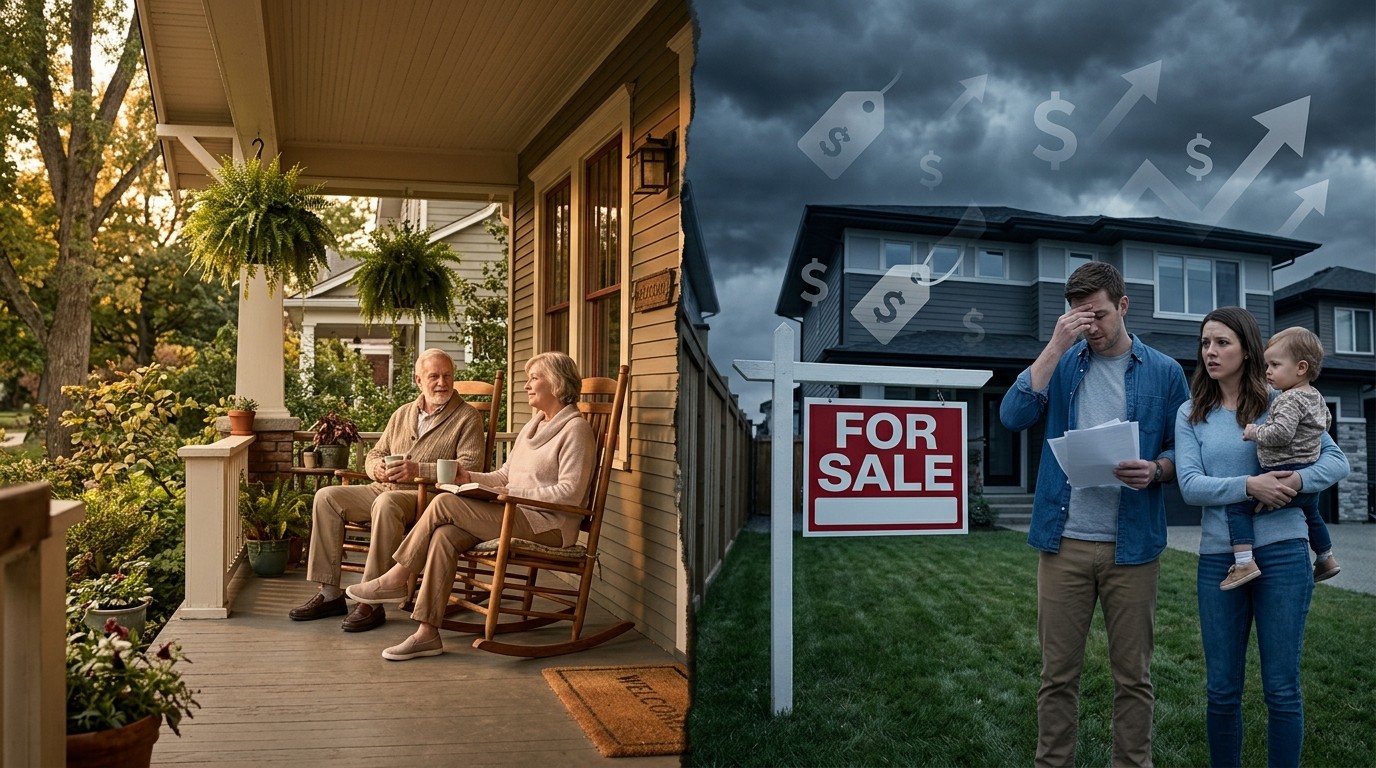

Have you noticed how some people talk about rising prices like it’s a minor annoyance while others sound genuinely exhausted by the same news? I’ve been thinking about that gap a lot lately. It turns out the affordability squeeze isn’t landing the same way on every household, and the difference between generations might end up mattering more at the ballot box than many expect.
Why Older Households Feel Less Pressure Right Now
Let’s start with the group that seems to be weathering the storm better than most. People in their mid-sixties and beyond are certainly paying more for groceries, gas, and electricity. Nobody is completely immune. Yet when you look at the bigger picture, many of them sit in a very different financial position than the typical thirty-something couple trying to buy a first home or pay for daycare.
One of the biggest reasons is simple ownership. A large share of seniors already own their homes outright or carry only small remaining balances. They are not shopping for a new mortgage at today’s rates. They are not competing with bidding wars that push prices higher every year. That single fact removes one of the heaviest monthly burdens younger families face.
There’s also the matter of daily habits. Older adults tend to drive fewer miles and keep the same car for longer periods. Higher gasoline prices still sting, but the overall impact is smaller. Auto loan rates that have climbed along with bond yields matter far less when you are not financing a new vehicle every few years.
And then there is childcare. For most retirees that expense simply does not exist. Families with young children, however, watch a growing chunk of their income disappear into daycare costs that have risen faster than overall inflation. There is no easy substitute for that particular bill.
Perhaps the most important buffer is the way Social Security works. Those monthly checks receive regular cost-of-living adjustments designed to keep pace with inflation. A recent announcement delivered a 3.6 percent increase for the coming year, which is higher than the long-term average. That automatic protection is something wage earners rarely enjoy.
When you add everything together, people seventy-five and older are often doing pretty well relative to the rest of the country.
I’ve found that this perspective surprises some readers. We tend to assume seniors live on fixed incomes and therefore suffer the most when prices rise. The data paints a more nuanced picture.
The Numbers Behind the Generational Gap
Economists have examined how different age groups experience price changes. One analysis weighted consumer price categories according to actual spending patterns by generation. From early 2019 through the middle of this year, older cohorts saw cumulative price increases around 31.5 percent. Millennials faced closer to 33.3 percent. Generation Z came in just behind them.
Two percentage points may not sound dramatic, but over several years it compounds. Younger households are spending more of every dollar on the categories that have risen fastest. Housing is the clearest example.
Consider what it takes to buy a home today. The monthly payment on a typical thirty-year fixed mortgage now claims about one-third of the median family’s income. That share has climbed sharply in just a few years. Interest rates sit near levels not seen outside the post-pandemic period for more than two decades. Home values themselves have outpaced income growth by a wide margin, especially for households headed by people under forty.
Between 2019 and 2024 the inflation-adjusted median home value rose roughly thirty percent. Median income for younger households grew only about nine percent over the same stretch. The last time the price-to-income ratio looked this stretched for young buyers was during the housing bubble years of the mid-2000s.
That kind of gap changes behavior. Some couples delay buying. Others stretch their budgets thin or take on more debt. Neither option feels comfortable.
Childcare Costs Keep Climbing Faster Than Everything Else
Housing is not the only pressure point. Full-day care for one child can consume anywhere from nine to sixteen percent of a family’s median income. In some markets the bill exceeds the rent payment. Recent reports show these expenses rising about one and a half times faster than the overall inflation rate.
Unlike groceries, where a shopper can switch from steak to chicken, there is no real substitute for reliable childcare if both parents work. The expense is sticky. It arrives every month whether the broader economy is cooling or not.
Young families therefore face a double squeeze: elevated housing costs plus elevated childcare costs. Older households largely avoid both.
Wealth Trends Are Moving in Opposite Directions
The Federal Reserve’s latest survey of consumer finances revealed another striking contrast. Between 2022 and 2025 the median net worth of families headed by someone under thirty-five fell by about twenty-three percent. At the same time, households headed by people seventy-five and older saw their median net worth climb roughly thirty-seven percent.
Stock market gains have played a large role. Strong returns concentrated among households that already held significant investment assets. Those assets tend to sit with older age groups. Younger families often hold little more than a retirement account with a modest balance, if that.
When older households see their portfolios rise, many feel comfortable drawing on those gains to support spending. Recent banking data shows a clear increase in the share of higher-income retirees making net withdrawals from investment accounts. Those withdrawals now cover a larger slice of their monthly outlays than they did several years ago.
Younger households do not have the same option. They either cut back or borrow more. In my view that difference in flexibility is one of the least discussed aspects of the current environment.
Healthcare Reality Check for Seniors
It would be unfair to paint older Americans as completely carefree. Medical costs and long-term care expenses weigh more heavily on them. Medicare Part B premiums continue to rise each year. Many retirees also face out-of-pocket costs that younger workers with employer coverage do not see in the same way.
Still, the broader social safety net tilts toward this age group. Social Security provides a floor. Medicaid serves as a backstop for long-term care once private resources run low. Those protections are simply not available in the same form for working-age families struggling with rent or daycare.
The net result is that seniors, as a group, retain more financial breathing room even while they deal with higher medical bills.
How This Divide Could Shape the Midterm Vote
Affordability has become the dominant conversation heading into the November elections. When people feel financially pinched they look for change. The question is which voters feel the pinch most acutely and whether they will show up.
Younger adults are the ones experiencing the highest effective inflation rates. Many of them express deeper frustration. Political analysts note that higher turnout among this group has historically tended to favor one side of the aisle. Older voters, more insulated from the worst of the cost pressures, may not feel the same urgency.
A recent national poll found that a large majority of adults place at least some blame for higher costs on current leadership. The share was high across party lines, though strongest among those already inclined to seek alternatives. When money feels tight, the instinct to look for new solutions grows stronger.
I keep coming back to a simple observation. People who are struggling with housing payments and childcare bills are more likely to treat the election as a referendum on everyday costs. People who own their homes free and clear and receive inflation-adjusted retirement checks may approach the same election with different priorities.
What the Data Suggests About Turnout Patterns
Historically, older Americans vote at higher rates than younger ones. That pattern has held for decades. Yet the intensity of economic pain can shift motivation. If the households feeling the most pressure decide the status quo is unacceptable, their participation rate could rise enough to matter in close races.
Forecasts currently point to a competitive environment in both chambers of Congress. Small shifts in turnout among specific age groups have flipped outcomes before. The generational difference in lived experience of inflation is therefore more than an interesting economic footnote. It is a potential electoral variable.
None of this means older voters are content or younger voters are uniformly angry. Individual circumstances vary widely. A senior living solely on Social Security in a high-cost area still faces real challenges. A young dual-income couple without children may feel less pressure than the numbers suggest. The aggregate picture, however, remains clear.
Looking Ahead at Policy and Perception
Policymakers on both sides have offered different responses to the cost-of-living concerns. Tax changes, energy policy, housing supply measures, and childcare support all enter the conversation. What matters for voters is whether they believe any of those proposals will reach their particular situation.
Younger households focused on homeownership and daycare may respond to different signals than retirees focused on preserving Social Security and controlling medical premiums. Campaigns that speak only in broad terms about “the economy” risk missing these distinct pain points.
In my experience following these debates, the most effective messages acknowledge that inflation does not hit every kitchen table the same way. Acknowledging the difference does not require choosing sides. It simply reflects the reality visible in the data.
Practical Differences in Daily Budgets
Walk through a typical monthly budget and the contrast becomes even sharper. A retired couple might allocate a larger share to healthcare and prescriptions, yet their housing cost is often stable and modest relative to income. A young family frequently sees housing and childcare together consume half or more of take-home pay before they buy groceries or fill the gas tank.
Transportation costs also diverge. Retirees who no longer commute can absorb higher fuel prices more easily. Working parents driving children to school and daycare feel every cent at the pump.
Even discretionary spending follows different patterns. Older households with rising portfolio values sometimes increase restaurant meals or travel. Younger households more often report cutting back on exactly those categories.
- Homeownership status creates the single largest gap in monthly obligations
- Childcare expenses fall almost exclusively on working-age parents
- Investment account gains provide spending flexibility mainly to older cohorts
- Automatic inflation adjustments protect a core portion of retirement income
These structural differences help explain why public conversation about affordability sometimes feels mismatched. One person’s experience of “high prices” is another person’s experience of manageable adjustments.
The Role of Asset Ownership in Feeling Secure
Wealth is not the same as income, and the distinction matters. A household can have modest monthly cash flow yet feel secure because home equity and investment balances have grown. Another household can earn a solid salary yet feel precarious because nearly every dollar is spoken for before the month ends.
Recent years have widened that gap. Equity markets delivered strong cumulative returns. Home values in many regions continued climbing even as mortgage rates rose. Both trends favored people who already owned those assets.
Younger adults trying to enter the asset ladder face higher entry costs precisely because of those same trends. The result is a generation that may delay major milestones or take on more leverage to achieve them.
I sometimes wonder whether we understate how much psychological weight that delay carries. Buying a first home or starting a family used to feel like natural next steps. For many it now feels like a high-stakes financial calculation.
What History Tells Us About Generational Economic Stress
Earlier periods of high inflation also created uneven experiences. The late 1970s and early 1980s punished borrowers with variable rates and rewarded those who held fixed-rate debt or real assets. The current episode shares some of those features while adding unique elements such as the rapid rise in childcare costs and the concentration of equity gains.
One difference worth noting is the strength of the retirement safety net today compared with earlier decades. Cost-of-living adjustments and Medicare provide floors that earlier generations of retirees lacked. That institutional support helps explain why the oldest households currently report stronger balance sheets relative to younger ones.
History also shows that prolonged periods of relative hardship for younger cohorts can influence long-term political preferences and policy demands. Housing policy, student debt discussions, and family support programs often gain traction when a large share of working-age adults feel locked out of traditional markers of stability.
Possible Paths Forward Without Easy Answers
There is no single lever that simultaneously lowers housing costs, expands childcare supply, and protects retirement security. Trade-offs are inevitable. Increasing housing supply takes time. Expanding childcare capacity requires both funding and workforce growth. Any change to Social Security or Medicare carries its own set of intergenerational questions.
What remains clear is that the current distribution of economic pressure is uneven. Treating affordability as a uniform national experience risks missing the groups that feel it most intensely. Those groups are disproportionately younger, and their voting behavior in the coming weeks could reflect that reality.
I’ve watched enough election cycles to know that economic narratives rarely stay static. A few months of cooling prices or a shift in interest rates can change the mood. For now, though, the generational split in lived experience is one of the more important undercurrents in the political conversation.
Younger families continue to confront higher effective inflation, elevated housing costs, and childcare bills that claim a large share of income. Older households benefit from higher rates of homeownership, inflation-adjusted retirement income, and stronger balance sheets. Those differences do not dictate how any individual will vote, yet they shape the intensity of economic concern that different age groups bring to the polls.
Understanding the divide does not require assigning blame. It simply requires looking at the data with clear eyes. The affordability conversation becomes more useful once we acknowledge that not every voter is starting from the same place.
As November approaches, watch the turnout numbers among different age groups as closely as the overall margins. The households feeling the greatest financial strain may decide they have the most at stake. That possibility alone makes the current generational gap worth paying attention to.
The story of rising costs is not one story. It is several overlapping stories, and the ending of each chapter depends on which generation is reading it.



