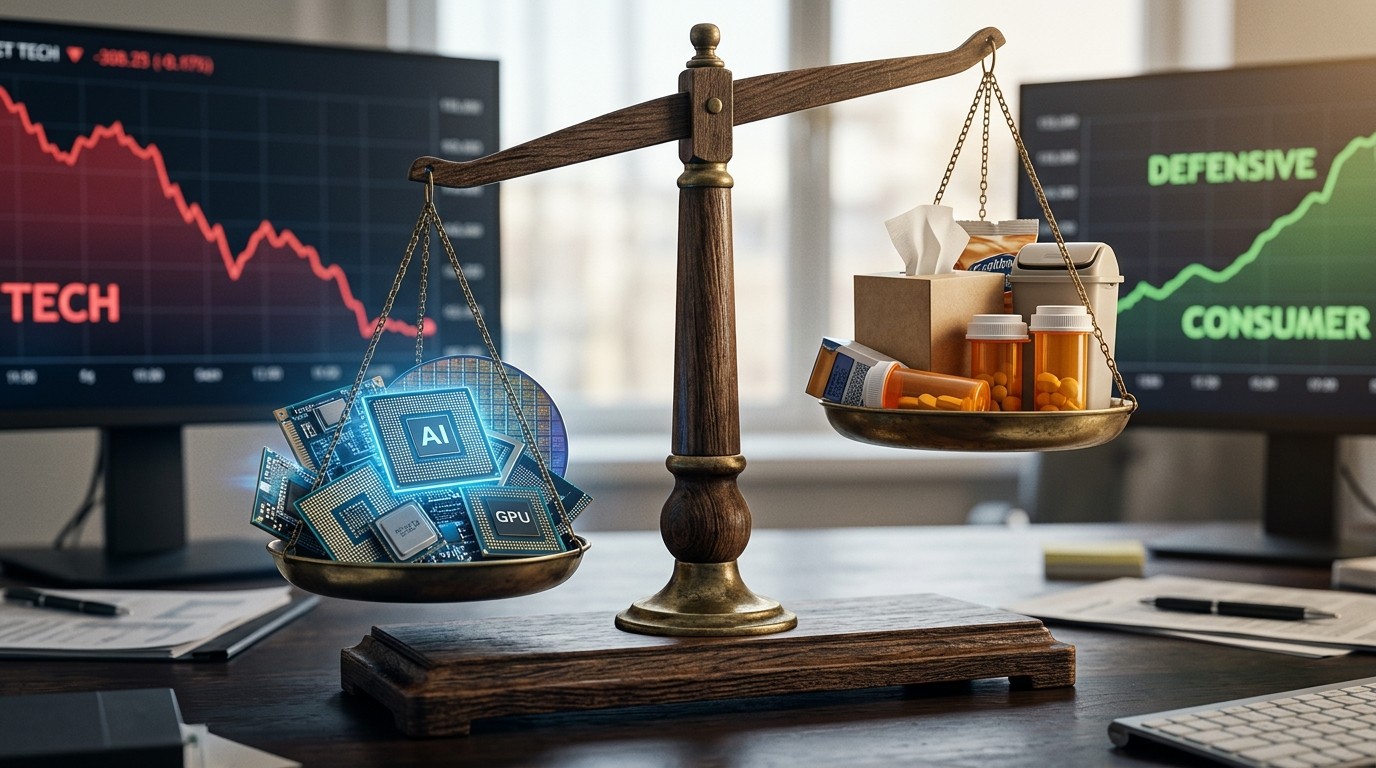

Have you ever watched one group of stocks race ahead for months while everything else lagged, only to see that same group suddenly stumble? That exact scenario played out this week with artificial intelligence names, and it left more than a few investors wondering what just happened to their carefully built gains. The sharp pullback in AI-related shares has delivered a clear message: spreading investments across different areas of the market is not just a textbook recommendation. It is the difference between staying in the game and watching hard-earned progress evaporate in a matter of days.
Why The Recent AI Reversal Matters For Every Investor
For a long stretch, AI infrastructure and semiconductor names dominated headlines and performance tables. Money flowed steadily into companies tied to data centers, chips, and the broader technology build-out. Returns looked almost effortless if you stayed concentrated in that single theme. Then the tide turned. What followed was an extended stretch of declines for the semiconductor group, marking one of the longer losing streaks in years. Meanwhile, quieter corners of the market quietly stepped forward.
Consumer staples, healthcare names, and waste-management businesses posted solid gains over the same period. Some of those defensive holdings advanced several percentage points in a single session and even more across the full week. The contrast could not have been sharper. Investors who kept meaningful exposure outside the hottest trade found their overall results far more stable. Those who leaned too heavily into the AI story faced sharper drawdowns and, in some cases, the temptation to abandon equities altogether.
I have seen this pattern before. When one sector becomes the undisputed leader, conversations about balance tend to fade. People start questioning why anyone would own slower-moving names when the growth engine keeps delivering. The answer becomes obvious only after leadership shifts. Diversification rarely feels exciting during the boom phase, yet it is the quiet force that preserves capital when the boom cools.
The Real Cost Of Concentrating In One Theme
Concentration feels smart when the concentrated names keep rising. It feels dangerous the moment they reverse. The recent AI weakness illustrated that risk with unusual clarity. An extended string of down days for semiconductor-focused vehicles left many growth-oriented portfolios looking softer than expected. At the same time, companies tied to everyday consumer needs and essential services moved higher.
Consider the difference in weekly performance. Certain AI-related holdings slipped while names linked to household products, waste services, and pharmaceuticals advanced more than six percent in some cases. That kind of rotation does not happen every week, but when it does arrive, the investors who already own a mix of styles tend to experience less emotional strain. The ones heavily tilted toward a single narrative often feel the pressure more acutely.
In my view, the greater danger is not the temporary paper losses themselves. The greater danger is the psychological impact. Significant declines in a concentrated portfolio can push people out of the market at precisely the wrong moment. Once an investor steps to the sidelines after a painful stretch, returning becomes harder. Diversification helps reduce the odds of that outcome by limiting how severe any single sector’s move can become relative to the whole portfolio.
When one group crashes to earth after a long period of outperformance, only a broader mix of holdings can meaningfully protect overall results.
That observation captures the essence of the current moment. The market does not reward permanent concentration. Leadership rotates. The names that felt invincible for months can lose momentum quickly, and the quieter businesses that seemed dull suddenly look more appealing.
How Thoughtful Portfolio Adjustments Can Make A Difference
One practical illustration of this principle appeared in a managed portfolio that reduced exposure to an AI-linked materials name earlier in the season and added a position in a consumer staples company instead. At the time, the shift looked early. The AI-related holding continued climbing for a while, and the new position drifted lower. Patience proved useful. Once the broader rotation began, the materials name softened while the consumer staples holding gained ground from its recent low.
Subsequent purchases of the staples name helped lower the average cost basis. The position moved from a modest unrealized loss toward a more comfortable standing as the stock recovered. Meanwhile, the exited name gave back a noticeable portion of its earlier advance. The sequence offers a useful reminder that timing every rotation perfectly is nearly impossible. What matters more is maintaining a process that systematically reduces reliance on any single theme.
I find it helpful to think of these adjustments as ongoing risk management rather than market timing. No one knows how long a rotation will last. The current move away from AI infrastructure could prove temporary or it could extend further. The point is not to predict the duration. The point is to ensure that no single group of stocks holds the power to define the entire portfolio’s fate.
Practical Ways To Build More Balanced Exposure
Building a more resilient mix does not require complicated formulas. It starts with an honest look at current holdings. Many growth-oriented investors discover that their largest positions share common drivers: capital spending on technology infrastructure, semiconductor demand, or cloud computing trends. When those drivers slow, the entire group can move together.
A simple first step is to identify a handful of high-quality companies whose revenues come from more stable end markets. Think of businesses that sell everyday household items, manage essential waste and recycling services, or develop medicines that patients need regardless of the economic cycle. These names rarely deliver the same explosive upside during a technology boom. They also tend to hold up better when technology momentum fades.
- Review the percentage of portfolio value tied to any single theme or industry
- Identify two or three defensive or less-correlated holdings that fit your quality standards
- Consider gradual additions rather than abrupt wholesale changes
- Track how the new mix behaves during both strong and weak periods for the former leaders
- Reassess allocation targets on a regular schedule rather than only after sharp moves
These steps sound straightforward because they are. The difficulty usually lies in the emotional resistance that appears when the concentrated approach is still working. It takes discipline to lighten exposure while a theme remains popular. Yet that discipline is exactly what creates breathing room later.
Understanding Sector Rotation Without Overreacting
Sector rotation is a normal feature of equity markets. Capital does not stay forever in the same place. After extended periods of outperformance, valuations often become elevated, profit-taking emerges, and investors begin searching for areas that look relatively attractive. The current shift away from pure AI infrastructure plays fits this historical pattern.
What makes the present moment instructive is the length of the prior AI leadership phase. When one group leads for so long, the eventual correction can feel more abrupt. Investors who grew comfortable with that leadership sometimes struggle to accept that other parts of the market can deliver competitive returns. The numbers this week offered a concrete demonstration. While one popular semiconductor vehicle logged consecutive declines, several non-technology names advanced solidly.
It is worth remembering that rotations rarely unfold in a straight line. There will almost certainly be days when AI-related stocks bounce and defensive names lag again. The goal is not to eliminate exposure to growth themes. The goal is to avoid letting any single theme become so large that temporary weakness forces uncomfortable decisions.
Perhaps the most interesting aspect is how quickly market psychology can change. Only a short time ago, many conversations centered on how far AI infrastructure spending could go. Now a growing share of attention focuses on valuation, capital intensity, and the need for broader participation. Both perspectives contain truth. Markets tend to overshoot in both directions, which is another reason balance remains useful.
Lessons From Past Leadership Changes
History is filled with examples of dominant themes that eventually shared the stage. Technology has led multiple cycles, only to hand the baton to other groups for stretches of time. Energy, financials, industrials, and consumer staples have each taken turns at the top. Investors who stayed flexible across those transitions generally experienced smoother rides than those who treated any single leadership phase as permanent.
The same principle applies today. AI and the broader technology complex remain powerful long-term forces. That does not mean every investor needs maximum exposure at every moment. Ownership can be scaled according to conviction, valuation, and overall risk tolerance. Maintaining a core of more stable businesses provides a foundation that allows growth positions to fluctuate without threatening the entire structure.
I have found that the investors who handle rotations most calmly are the ones who already own a range of styles before the rotation begins. They do not need to make dramatic changes under pressure. Their portfolios already contain both the former leaders and the new participants. That preexisting balance reduces the need for reactive trading.
Avoiding The Temptation To Abandon Equities
One of the quieter risks of heavy concentration is the potential for investors to exit the asset class after a painful stretch. Large losses concentrated in a small number of holdings can feel personal. The emotional response sometimes leads people to conclude that stocks themselves are too unpredictable. In reality, the problem often traces back to the lack of balance rather than the asset class as a whole.
A diversified approach helps keep drawdowns within a range that most people can tolerate. When some holdings decline while others advance or hold steady, the overall portfolio moves less dramatically. That relative stability makes it easier to stay invested through the inevitable periods of sector weakness. Staying invested, in turn, is one of the most reliable ways to participate in the long-term upward bias of equity markets.
Think of diversification as a form of insurance that costs very little during calm periods and becomes invaluable during turbulent ones. The cost appears as slightly lower returns during the strongest phases of a single theme. The benefit appears as smaller losses and greater staying power when that theme weakens. Over complete market cycles, the benefit usually outweighs the cost.
Building A Process That Survives Different Environments
Successful long-term investing depends less on predicting the next rotation and more on preparing for the reality that rotations will occur. A useful process includes regular portfolio reviews that examine sector exposure, correlation among holdings, and the potential impact of a meaningful decline in the largest positions.
Some investors set explicit limits on the maximum percentage allocated to any single industry or theme. Others prefer a qualitative approach that simply ensures meaningful ownership of both growth and defensive businesses. Either method can work if applied consistently. The key is deciding on the approach during calmer periods rather than inventing rules after a sharp move has already occurred.
- Define the maximum acceptable exposure to any one sector or theme
- Identify high-quality alternatives that offer different economic drivers
- Implement changes gradually to reduce timing risk
- Monitor the overall portfolio’s behavior across varying market conditions
- Adjust targets only when fundamental views or risk tolerance change meaningfully
These guidelines keep the focus on process rather than prediction. Markets will continue to surprise. A well-constructed mix of holdings makes those surprises less disruptive.
What The Current Environment Suggests Going Forward
No one can say with certainty how long the present preference for non-AI names will last. Leadership can reverse quickly if new catalysts appear or if valuations in the defensive group become stretched. The more important takeaway is the demonstration of how quickly relative performance can change. Investors who treated the AI theme as the only game in town experienced a different set of results this week than those who maintained broader exposure.
Looking ahead, the technology sector will likely remain a significant source of innovation and growth. At the same time, other parts of the economy continue to generate steady cash flows and more predictable demand. Owning both sides of that spectrum creates a portfolio capable of participating in upside while cushioning the downside of any single narrative.
In my experience, the most durable results come from investors who accept that no theme lasts forever at the top of the performance tables. They treat leadership changes as expected rather than shocking. That mindset makes it easier to own a range of businesses and to rebalance when concentrations become extreme.
Putting The Principle Into Everyday Practice
Applying these ideas does not require constant trading or complex models. It begins with awareness of where risk is currently concentrated. Many portfolios that look diversified by number of holdings still share heavy exposure to the same underlying economic drivers. A closer examination often reveals that a large percentage of value depends on continued strength in capital spending related to technology infrastructure.
Once that concentration is recognized, the next step is identifying high-quality businesses whose results depend on different forces. Companies that supply essential consumer products, manage critical infrastructure services, or develop therapies for chronic conditions tend to respond to different economic signals. Adding measured exposure to such names can reduce the portfolio’s sensitivity to any single set of headlines.
The process works best when changes occur gradually. Selling an entire position in a former leader and immediately buying something completely different introduces unnecessary timing risk. Smaller, incremental shifts allow the investor to observe how the new mix behaves without making irreversible decisions based on short-term price action.
Over time, these modest adjustments compound into a more resilient structure. The portfolio still participates when growth themes lead. It also has ballast when those themes pause. That combination supports the most important long-term objective: remaining invested through multiple market environments.
The Emotional Side Of Staying Balanced
Numbers tell only part of the story. The emotional experience of investing matters just as much. Watching a concentrated portfolio swing sharply higher feels exhilarating. Watching it swing sharply lower feels draining. Diversification moderates both extremes. The upside may feel less dramatic during the strongest phases of a single theme. The downside also feels more manageable when weakness appears.
That moderation helps investors stick with their plans. Few people make their best decisions while staring at large paper losses in a handful of holdings. A more balanced portfolio reduces the frequency and severity of those moments. As a result, investors are more likely to stay the course and allow the long-term compounding process to work.
I have noticed that the people who talk most about diversification after a painful stretch are often the ones who paid the least attention to it beforehand. The better approach is to treat balance as a permanent feature of the process rather than a temporary reaction to market stress. Building the habit during quiet periods makes it far easier to maintain when markets become noisy.
A Final Perspective On Concentration Risk
The recent weakness in AI-related shares offers a timely reminder rather than a permanent verdict on the technology itself. Innovation continues. Capital spending on advanced computing infrastructure will likely remain significant for years. At the same time, other sectors of the economy keep generating reliable demand and cash flow. A portfolio that owns both sides of that reality is better positioned to weather the inevitable periods when one side underperforms.
Concentration can deliver impressive results for stretches of time. It can also deliver sharp setbacks that test even experienced investors. Diversification does not eliminate those setbacks, but it usually makes them smaller relative to the overall portfolio. That difference is often enough to keep people invested and focused on the longer horizon.
Markets will continue to cycle through periods of concentrated leadership and broader participation. The investors who prepare for both environments by maintaining thoughtful exposure across multiple areas tend to experience fewer forced decisions and more consistent progress over time. The latest rotation simply underscores a principle that has stood the test of many previous cycles: spreading risk across different parts of the market remains one of the most practical ways to protect capital and stay in the game for the long run.
When the next dominant theme emerges, the same lesson will apply. Enjoy the upside while it lasts. Keep enough balance so that the eventual pause does not force you out of the market. That combination of participation and protection has proven durable across decades of market history, and it remains just as relevant today.