
What happens when the one place in America that was supposed to welcome data centers with open arms suddenly decides it has had enough? I keep coming back to that question after watching the latest twist in Northern Virginia. A company that has poured tens of billions into the region just walked away from a major project, handed over land and cash, and promised never to put servers on the property. The county that relies on these facilities for a huge slice of its budget accepted the deal. Something has shifted, and the change feels bigger than one parcel of land.
The Moment Data Center Alley Started Saying No
For years Northern Virginia earned the nickname Data Center Alley for good reason. Loudoun County in particular became the place where hyperscalers could move fast. Zoning was friendly. Power was available, at least for a while. Local officials understood the tax revenue that came with those windowless buildings. Amazon alone has invested more than sixty billion dollars in the county since 2011. The numbers look impressive on paper. Roughly two hundred thirty-three data center buildings already generate about 1.2 billion dollars in property tax revenue for the fiscal year, nearly forty percent of the entire county budget.
Then the ground started to move. Residents grew louder. Supervisors who once waved projects through began to hesitate. Earlier this year a big private equity player sold its stake in three local facilities after facing grassroots anger. Now the biggest name in the space has done something even more striking. It bought a former university campus for hundreds of millions, filed plans for nearly a million square feet of data center space, and then reversed course completely.
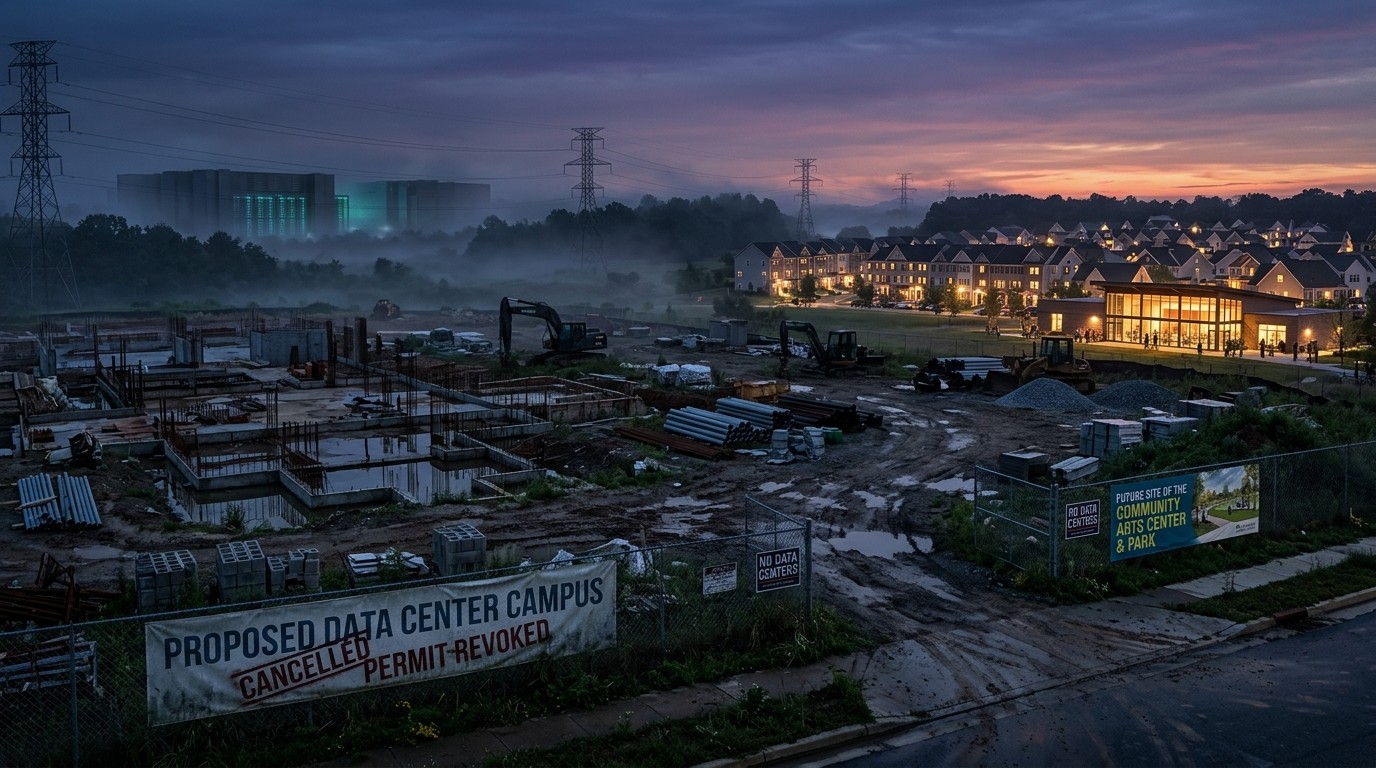
The agreement is straightforward on the surface. The company will redevelop most of the 122-acre site for mixed-use and residential purposes. It will donate twenty-five acres for a community arts center and recreational facility. It will also put five million dollars into the county housing fund. In return it promises never to build data centers on that land. The county gets gathering places, more attainable homes, and roughly seventy million dollars in combined land value and cash. The company is left holding an expensive future apartment complex.
I find the optics fascinating. The same county that needs these facilities more than almost any other just accepted a sizable check to make sure one never gets built. If Data Center Alley is drawing this kind of line, where exactly are the next projects supposed to go?
How a Four-Hundred-Million-Dollar Bet Turned Into Townhouses
The land deal itself tells a story about expectations. The company paid roughly four times the assessed value for the former campus earlier this year. Officials noted that the existing zoning made data centers a reasonable expectation. Site plans filed in late summer outlined four two-story buildings totaling more than eight hundred thousand square feet. Local supervisors immediately signaled they would fight the project every step of the way. Meetings followed. Legal differences over what the land could actually support became clear. Rather than dig in for a long fight, the company chose a shared vision and agreed not to sue.
Rezoning will take about a year even on a fast track. In the meantime the capital that was meant to expand digital infrastructure is now committed to housing and community amenities. That is not a small pivot. It is a full about-face.
By choosing dialogue over reflexive disagreement, the county and the company created an opportunity for residents to gather, create, and play while adding more attainable homes for working families.
The statement sounds cooperative. The underlying reality is that community pressure forced a renegotiation that few expected in this particular zip code. Money was on the table. Legal leverage existed. Permission still evaporated.
A Pattern of Reversals Across the Region
This is not an isolated event. Next door in Prince William County a massive project covering more than two thousand acres faced a court ruling that voided its rezoning. A major developer backed by institutional capital pulled out after spending tens of millions and years chasing approvals. Another large operator abandoned a significant planned facility. Loudoun itself voted to draft a pause on new applications lasting up to twelve months, the maximum allowed under state law. Officials carefully avoided calling it a moratorium, yet the practical effect is the same. The final decision on that pause was delayed until mid-November.
None of these setbacks stem from companies running out of cash. The capital is available. The demand for capacity is intense. The permission to build is what has become scarce. That distinction matters. When the bottleneck shifts from money to politics, the entire timeline for AI infrastructure changes.
I’ve watched these stories accumulate over recent months and the speed is what stands out. Community opposition used to rank near the bottom of industry surveys on delivery constraints. Equipment lead times, power availability, and permitting sat at the top. Political risk barely registered. Then opposition numbers climbed sharply in national polling. The share of people strongly against a data center near their home rose dramatically within a single year while overall support collapsed. Local moratoriums multiplied several times over in a matter of months.
Why the Six Percent Problem Suddenly Matters
Industry respondents once ranked community opposition as a minor issue. That ranking looks outdated now. The same political pressure that once seemed peripheral has blocked or delayed projects even in the most hospitable counties. Zoning fights, threatened litigation, and negotiated community payments do not always appear on formal moratorium trackers. They still kill projects. Deterrence works quietly. Some proposals never get filed. Others get reimagined as residential developments before anyone starts counting megawatts.
The bipartisan nature of the pushback adds another layer. In one of the top data center states both leading candidates for governor have called for tighter restrictions. One favors a conditional approach requiring developers to cover utility costs fully, use union labor, and meet strict environmental standards. The other outlines non-negotiable requirements around free electricity for nearby residents, full property tax payments without abatements, and preference for brownfield sites. The message is consistent across party lines. Data centers have become unpopular.
Midterm elections could tighten the screws further in states that currently host tens of gigawatts of planned capacity. One large state has already ordered a halt on new projects pending an audit. The political calendar is not abstract. It is part of the construction schedule now.
Power Constraints Arrive Right After the Zoning Board
Even when a project clears local approval, the next wall appears quickly. Interconnection timelines have stretched dramatically. The median time from request to commercial operation has more than tripled compared with two decades ago. A data center can be developed in two to three years. Heavy-duty gas turbines often take five to seven years to arrive. Reservations for major equipment now extend into the next decade.
Transformers and switchgear sit in the same bottleneck. Lead times of two years are common. Larger units can stretch far longer. Electricians remain in short supply. When every link in the chain must arrive on time, delays compound. One delayed component can stop an entire project from delivering capacity.
Analysts who add up every available fix still see a multi-gigawatt shortfall through the end of the decade. Spare grid capacity, nuclear options, announced turbines, and on-site generation help, yet the gap remains. The combination of people, power, and politics creates a harder environment than pure capital constraints ever did.
Behind-the-meter solutions keep coming up as a possible answer. If the community will not share its grid, bring your own power plant. That approach carries its own zoning and permitting challenges. It also requires capital and long-lead equipment that are already scarce. The idea is logical. Execution is another matter.
What Delayed Buildouts Mean for Winners and Losers
When capacity arrives later than expected, certain positions strengthen. Owners of operating facilities can raise rents and fill every available megawatt. Holders of land that already has power and grid access gain leverage. Manufacturers of long-lead equipment and on-site power producers see stronger demand. Scarcity has a price.
On the other side sit the hyperscalers whose revenue growth depends on new supply. Committed capital continues to accrue while capacity sits idle or delayed. Developers and construction-stage investors watch cash flows push further into the future while interest and carrying costs keep running. Equity valuations that assumed on-time delivery face potential revisions.
A delay is not the same as a cancellation. Delayed assets can still become more valuable if scarcity persists. The greater risk appears when supply eventually catches up in a rush or demand softens. That scenario would erode the premium currently attached to existing capacity. Some large investors have already sold operating facilities at elevated prices while the scarcity narrative remains strong. Others are absorbing full cancellations.
The Loudoun campus falls into the cancellation category. It joins a growing list of projects that have been re-envisioned, paused, or abandoned. Each one reduces the near-term pipeline even if long-term demand remains robust.
Forecasts That Already Assume Half the Pipeline Disappears
Major research houses continue to publish relatively constructive outlooks. Capacity estimates for the next couple of years look largely intact in some reports. Look closer at the assumptions and the picture changes. Many forecasts already bake in the idea that only fifty to sixty percent of currently scheduled additions will actually materialize. Historical relationships between announced and activated capacity support that haircut.
In other words, the base case already assumes that a large share of the planned buildout will not switch on when expected. Near-term numbers sometimes get revised upward as projects pull forward. Later years get trimmed. The revisions themselves reveal the underlying caution. Political pushback and power constraints are no longer footnotes. They are core inputs.
Effective spare capacity on the grid has tightened across key regions. That reality reinforces the view that even approved projects face a second, harder filter. Permission is necessary. Power is decisive.
Where Does the Industry Go From Here
The bull case has long rested on the belief that physical constraints could eventually be overcome with enough capital. Chips, transformers, and turbines take time, but money usually finds a way. Loudoun showed that money cannot always buy permission. Hundreds of millions for the land, additional tens of millions in community contributions, and the threat of litigation still produced a residential outcome instead of servers.
Perhaps the most interesting aspect is how quickly the conversation has shifted. A year ago community opposition felt secondary. Today it ranks among the primary risks. Local officials who once competed for data center tax revenue now weigh quality-of-life concerns more heavily. Residents who once stayed quiet now organize. The political spectrum offers little shelter.
Some observers still argue that formal moratoriums affect only a small fraction of planned capacity. That may be true on the narrow numbers. The quieter risk is deterrence. Projects that never get proposed do not appear in any tracker. Re-envisioned parcels look like housing wins rather than infrastructure losses. The cumulative effect can still be substantial.
I keep returning to the practical question. If the friendliest county in the country is accepting deals that lock out data centers, who is left to say yes? Other regions will compete, of course. Some will offer incentives. Others will face the same resident concerns once projects reach a certain scale. Power constraints travel with the facilities. The underlying tensions do not disappear simply by changing the map.
The Quiet Shift in Risk Profiles
For investors the change in risk profile is real. Operating assets with power and permits look more valuable in a constrained environment. Greenfield development carries higher political and interconnection risk than it did even eighteen months ago. Equipment suppliers with long order books enjoy visibility. Companies that can deliver behind-the-meter solutions or modular approaches may find more receptive audiences.
The AI buildout itself is not going away. Demand for compute continues to expand. What is changing is the speed and certainty of supply. Timelines that once stretched two or three years now routinely run longer. Carrying costs accumulate. Revenue recognition shifts. Valuation models that assumed smooth delivery face adjustments.
In my view the next twelve months will clarify how deep the political resistance runs. Votes on pauses, gubernatorial races, and local board decisions will provide more data points. Turbine delivery schedules will remain a hard constraint regardless of politics. The combination of both forces suggests that the haircut already embedded in many forecasts may prove conservative rather than aggressive.
Amazon can try again somewhere else in the same county after the pause window closes. Other developers will keep filing applications. The path is not closed. It is simply narrower and more expensive than it used to be. Community dividends are now part of the cost of doing business. Zoning fights are part of the timeline. Power remains the ultimate gatekeeper.
Data Center Alley has not gone dark entirely. It has, however, flipped a switch that was long assumed to stay on. The region that once said yes to almost everything has shown it can also say no. That demonstration will travel. Other communities will take note. Developers will adjust. The infrastructure needed to support the next wave of artificial intelligence will still get built. It will just take longer, cost more, and face harder questions along the way than most models originally assumed.
The real story is not one cancelled campus. It is the broader realization that permission and power now sit alongside capital as equal constraints. When those three elements fail to line up, even the largest players change course. The Loudoun deal is a clear example. It will not be the last.
Looking ahead, the industry will likely experiment with new approaches. More aggressive community benefit packages. Greater emphasis on brownfield and industrial sites. Expanded use of on-site generation. Modular designs that reduce local footprint. Whether those adjustments prove sufficient remains an open question. The political and physical realities on the ground will decide.
For now the message from Northern Virginia is unmistakable. Even in the heart of Data Center Alley, the old playbook no longer guarantees results. The next phase of the buildout will require more than money and ambition. It will require negotiation, patience, and a willingness to accept that some projects simply will not happen on the original timetable or in the original form.
That adjustment may ultimately prove healthy. Scarcity can drive efficiency. Higher hurdles can force better site selection. Community engagement, when done early and sincerely, can reduce later conflict. None of those benefits appear automatically. They require deliberate changes in how projects are planned and presented.
The companies that adapt fastest will capture the limited capacity that does come online. The ones that continue to treat local opposition as a minor checklist item will keep discovering expensive surprises. The market is already sorting those outcomes. Operating assets trade at premiums. Greenfield risk is being repriced. The Loudoun reversal simply made the shift visible to a wider audience.
In the end the servers will still arrive. The question is how many, how soon, and at what total cost. The answer is being written not only in equipment lead times and interconnection queues but also in county board meetings and neighborhood associations. Data Center Alley has reminded everyone that both sides of the equation matter.