

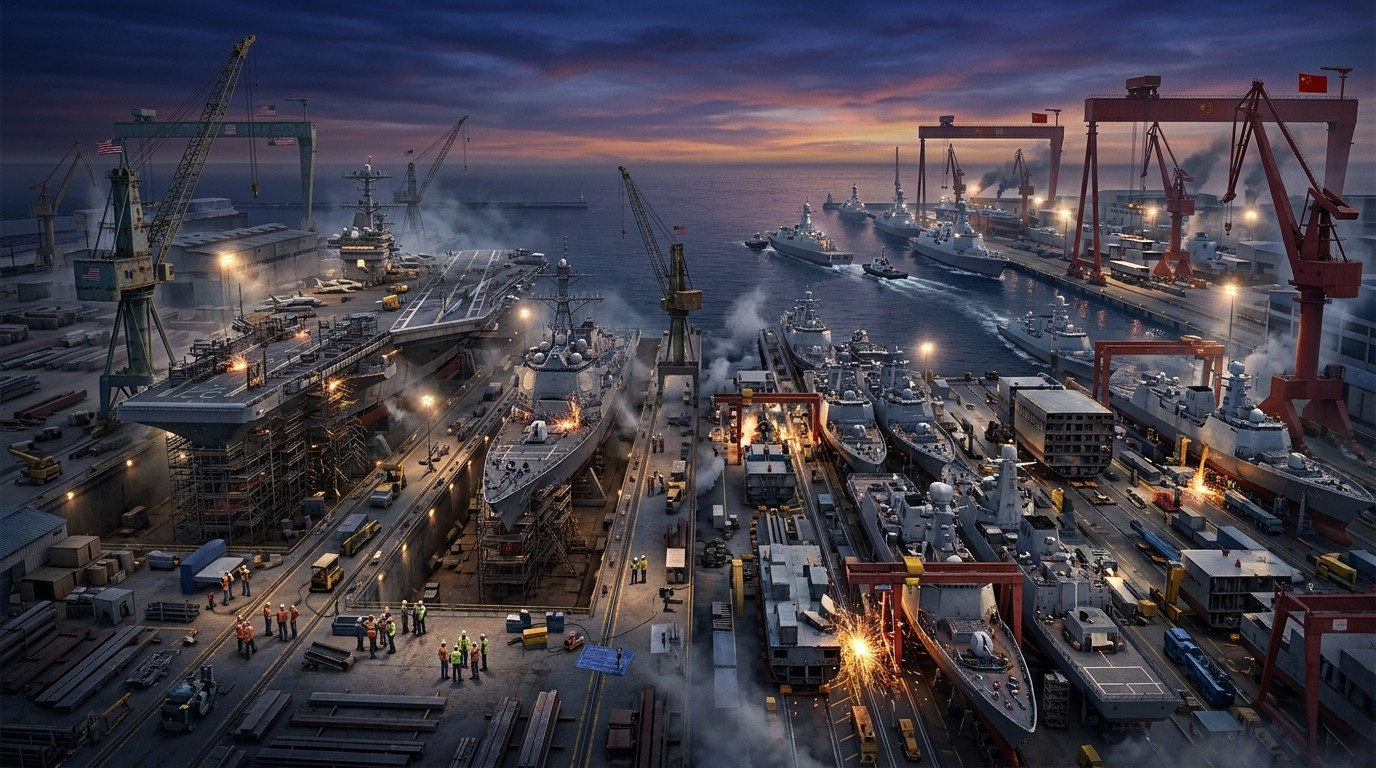

I still remember the first time I stood on a shipyard dock years ago and felt the sheer scale of what it takes to put steel into the water. The noise, the heat, the coordinated chaos of hundreds of people moving with purpose. That memory hits differently now. Because the numbers coming out of the industry these days feel less like progress and more like a wake-up call that arrived late.
The United States once built ships at a pace the world could barely match. Today the story has flipped. China turns out roughly seventeen hundred vessels a year while American yards manage about five. That is not a rounding error. It is a structural gap that officials now openly call a national security problem. The Navy is asking for more than sixty-five billion dollars in shipbuilding funds for 2027 as Washington tries to claw back lost ground. I have watched industrial capacity stories unfold before, and this one carries a particular weight.
The Long Decline That No One Wanted To Notice
For decades the American maritime industrial base quietly contracted. After the Second World War the country had poured roughly nine hundred million dollars into shipbuilding in a single year, money that would equal about twenty billion today. Within three years those yards were launching more than nineteen hundred ships annually. Then the support faded. Subsidies ended in the early eighties. Commercial work drifted overseas. Naval construction became a specialized, slow, and expensive craft practiced in a handful of remaining facilities.
China took a different path. It treated commercial and naval construction as two sides of the same industrial machine. The result is more than fifty-three percent of the world’s ship tonnage now coming from Chinese yards. Scale compounds. When a nation builds commercial hulls at high volume, the skills, the supply chains, and the workforce stay sharp. When another nation builds only a few complex warships each year, those same muscles atrophy.
In 2016 the Navy settled on a target of three hundred fifty-five battle force ships for a potential conflict with major rivals. China’s fleet at the time stood near two hundred fifty-five. Current estimates put the Chinese total above four hundred. The American Navy remains roughly sixty ships short of that older goal, and the requirement itself has only grown. The arithmetic is simple and uncomfortable.
Why Building Ships Takes So Long In American Yards
Visit a facility like the one on Blakeley Island in Mobile and the bottlenecks become visible. Even a relatively lightly armed Expeditionary Fast Transport still needs thirty-two to thirty-three months from start to delivery. Design changes on the first ship of a new class can stretch schedules by months and add tens of millions in cost. Building the same vessel in the United States often runs four to five times more expensive than in China or South Korea.
Labor sits at the center of the problem. The industry faces a shortage of roughly two hundred fifty thousand skilled workers. Training two hundred apprentices over several years can cost more than three million dollars. Conditions are harsh. Pay has historically lagged what many skilled tradespeople can earn elsewhere. Turnover stays high. I have spoken with people who left the yards after a few years because the physical demands and the uncertainty around long-term careers simply wore them down.
Recent contract talks have started to change the equation. At one major yard an immediate base-wage increase of at least eighteen percent arrived, with total raises of thirty-five to forty-seven percent stretched through 2031. Higher wages have begun attracting more experienced hires. Yet workers themselves will tell you that money alone is not enough. They want healthcare that feels reliable, some flexibility in scheduling, and a clear path toward retirement. Without those pieces the talent pipeline remains leaky.
A Sudden Surge Of Funding And Political Attention
After years of relative neglect the funding picture has shifted dramatically. Thirty billion dollars for new Navy and Coast Guard ships became law in 2025. The request for 2027 jumps to sixty-five point eight billion. That figure alone roughly matches the entire defense budget of certain nuclear-armed European nations. It still represents only a little more than four percent of a much larger overall defense request, but the direction of travel is unmistakable.
An executive order on shipbuilding arrived the same year, calling for a Maritime Action Plan that would include investment incentives, dedicated funding streams, expanded workforce training, and reforms aimed at cutting procurement delays and regulatory costs. Whether those reforms survive contact with bureaucracy remains an open question, yet the intention is clearer than it has been in a generation.
South Korea, the world’s second-largest shipbuilder, has entered conversations about helping restore domestic capacity. American officials are counting on at least seven shipyards to accelerate deliveries. The hope is that partnerships and capital can restart the flywheel that once spun so effectively.
Workforce Culture Is Starting To Shift
Something interesting is happening on the shop floor. At one California yard union membership climbed from twenty-one percent to sixty-seven percent during recent contract negotiations. Younger workers are beginning to see themselves as skilled tradespeople rather than temporary labor. Solidarity feels stronger. Half the members at that particular facility cross the border each day, some leaving home at two in the morning to reach the yard by six. That level of commitment deserves better infrastructure and support than it has often received.
Yards are experimenting with transportation aid, gas cards, transit support, hiring campaigns, and formal training pipelines. Artificial intelligence and robotics are entering the conversation as tools to handle the most repetitive and physically punishing tasks. One contract in Maine created a formal process for bringing workers into technology decisions earlier rather than springing automation on them at the last minute. That kind of inclusion matters. People who feel ownership of change are less likely to resist it.
Pay alone will not hold skilled workers. Yards must offer a long-term career with healthcare, flexibility, and retirement benefits.
I tend to agree. The most expensive training investment is the one that walks out the gate after two years because the job never felt like a future.
The Cost Of Complexity And The Price Of Delay
Modern warships are not Liberty ships. They carry sophisticated combat systems, layered sensors, and requirements that change mid-construction. Every design modification ripples through schedules and budgets. First-of-class vessels almost always absorb the largest overruns. Once serial production begins the learning curve can flatten costs, but only if the program survives long enough to reach that stage.
The Navy has floated ambitious concepts including a fifteen-ship battleship program with a projected price tag near two hundred seventy-five billion dollars. Whether that specific effort moves forward or evolves into something else, the underlying lesson remains the same. Capacity cannot be rebuilt overnight. Supply chains for specialized steel, propulsion systems, and electronics take years to reconstitute. The people who know how to weld thick plate or integrate complex combat systems are not created by a single budget cycle.
Perhaps the most interesting aspect is how commercial and military construction reinforce each other. Nations that maintain high commercial volume keep their industrial base warm. Nations that treat naval construction as a pure boutique activity watch that base cool. China understood the interaction early. The United States is relearning it under pressure.
Lessons From The Last Time America Built At Scale
World War II shipbuilding succeeded because the country treated the effort as a national priority rather than a procurement category. Capital flowed. Designs were simplified where possible. Labor was mobilized and trained at volume. The result was an output rate that still looks astonishing. After the war the urgency vanished and so did the sustained investment. The current scramble is an attempt to reverse that long arc of disinvestment in a compressed timeframe.
History suggests that industrial capacity, once lost, is expensive and slow to regain. The skills exist in fragments. The facilities exist in reduced numbers. The institutional memory of how to surge production has thinned. Rebuilding requires more than money. It requires consistency across administrations and Congresses so that yards can hire, train, and invest without fearing the next budget cliff.
What Closing The Gap Would Actually Require
Money is necessary but not sufficient. Several parallel tracks need to move together.
- Stable multi-year funding so yards can plan capital improvements and workforce development without annual uncertainty
- Expanded apprenticeship and training pipelines that treat shipbuilding as a respected long-term career
- Regulatory and procurement reforms that reduce unnecessary delay without sacrificing safety or capability
- Selective partnerships with allied shipbuilders that transfer best practices while protecting core national capacity
- Integration of automation and advanced manufacturing in ways that augment rather than simply replace skilled labor
None of those elements is simple. Each carries political, technical, and cultural friction. Yet the alternative is continued erosion of relative maritime strength at a moment when that strength is once again contested.
I have found that industrial recovery stories rarely follow a straight line. Progress appears, setbacks arrive, budgets shift, and the public attention span moves elsewhere. The difference this time is that the strategic environment is less forgiving. A gap that once seemed abstract now looks concrete when measured in hulls afloat and industrial output rates.
The Human Element Behind The Steel
It is easy to talk about tonnage and budget lines. Harder to remember that every ship is the product of individual people making daily decisions under pressure. The welder who shows up at dawn. The designer who revises drawings for the third time. The supervisor trying to keep a critical path moving while parts arrive late. Culture inside the yards matters as much as capital outside them.
When workers gain more voice in how new technology is introduced, resistance drops. When pay and benefits begin to reflect the difficulty of the work, retention improves. When younger employees start to view the trade as skilled and durable rather than temporary and punishing, the pipeline starts to refill. Those cultural shifts are quieter than budget announcements, yet they may prove more decisive over the next decade.
One coordinator noted that half the union members at a major California facility make the daily cross-border commute. That fact alone should focus attention on practical supports such as reliable transportation options and predictable schedules. Small frictions compound into attrition. Removing them is not glamorous, but it is effective.
Looking Ahead Without Illusions
Can the gap be closed? In absolute numbers the Chinese industrial base is unlikely to shrink. The more realistic goal is to restore American capacity to a level that prevents further relative decline and supports the force structure the strategy requires. That will take sustained funding, realistic program management, and a workforce that believes the industry has a future worth investing in personally.
The United States spent decades watching its shipyards shrink while another nation built the world’s largest fleet. The bill for that neglect has come due. Whether the current surge of attention and capital produces lasting results will depend on how long the effort is maintained after the initial headlines fade. Industrial recovery is a marathon run under the pressure of a sprint.
In my view the most promising sign is not any single budget number. It is the combination of higher wages, stronger worker voice, targeted infrastructure investment, and a clearer political acknowledgment that maritime industrial capacity is a strategic asset rather than a pure cost center. Those elements, if held together long enough, can begin to reverse the long slide.
The yards are still there. The water is still waiting. The question is whether the country will treat the work of putting steel into the sea with the seriousness the moment demands. History shows it is possible. The present will decide whether it is probable.
The next few years will reveal whether this moment of recognition turns into durable capacity or simply another temporary spike. Shipbuilding rewards consistency more than bursts of enthusiasm. The people who swing the hammers and run the cranes already understand that. The rest of the system is catching up.
Watch the apprenticeship numbers. Watch the retention rates. Watch whether multi-year funding commitments survive the next budget cycle. Those indicators will tell the real story long before the next hull hits the water. The scramble is underway. Closing the gap will require more than money. It will require the kind of steady industrial focus that once felt ordinary and now feels almost radical.
That focus is still possible. The alternative is accepting a permanent disadvantage in a domain that has decided the outcome of conflicts for centuries. Few strategic choices carry higher stakes or demand clearer eyes.



