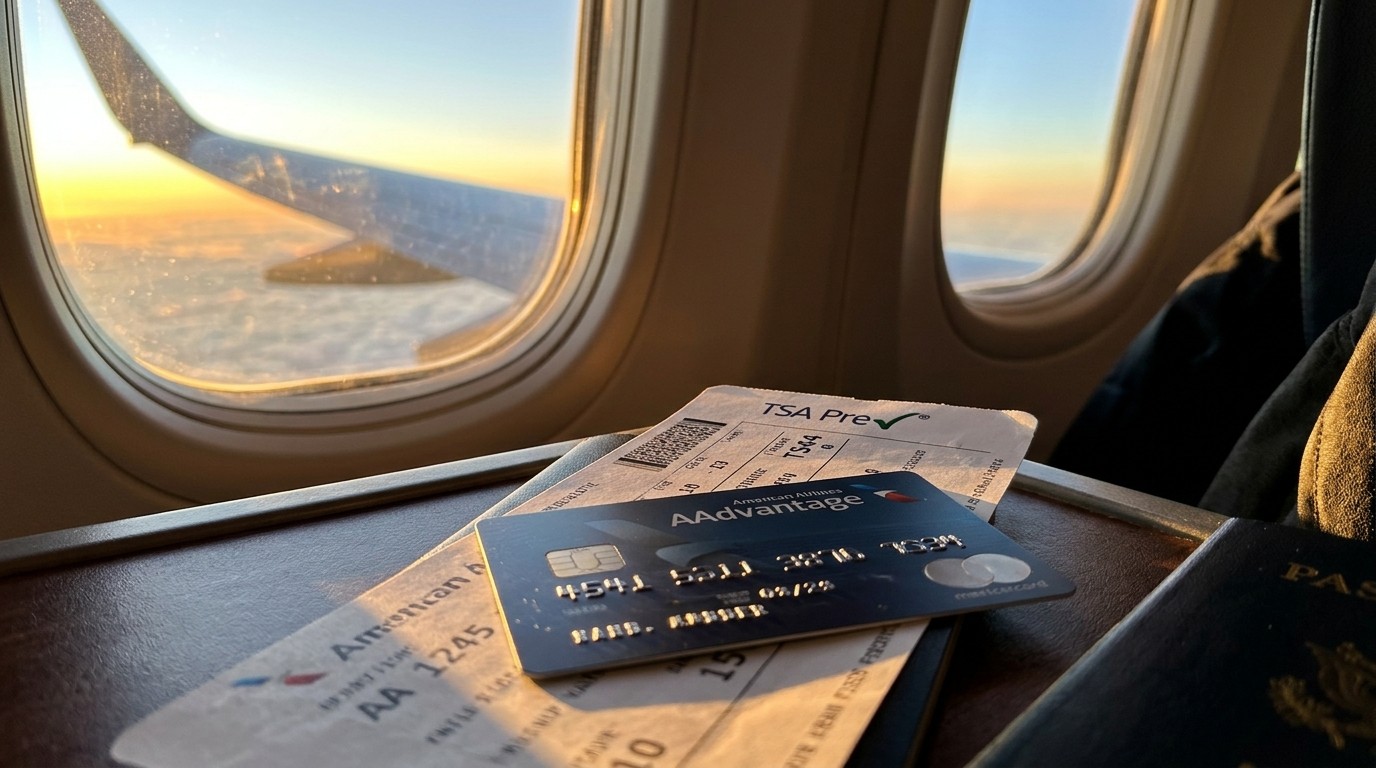

I’ve been watching airline rewards cards for years, and every time one of the big carriers adjusts fees it feels like a quiet signal that the whole industry is shifting again. This week American Airlines made its move. For the first time since 2018 the annual fee on two of its most popular Citi co-branded cards is going up. The Platinum Select World Elite Mastercard and the Business Mastercard will both jump to $150. That is a noticeable climb from the previous $99 on the consumer version. The change takes effect on January 24, so cardholders still have a little time to decide whether the new price tag still makes sense for their travel habits.
Why Airlines Keep Raising Card Fees
Airlines do not raise fees just for fun. These co-branded cards generate serious revenue. Banks pay the airlines for the miles that get deposited into customer accounts, and the annual fees themselves add another reliable stream of income. When fuel costs rise, labor expenses climb, or competition intensifies, the rewards side of the business often becomes a pressure valve. American has held the line longer than some rivals. United made similar moves earlier. The big premium cards from other issuers have also climbed sharply in the past couple of years. The pattern is clear: the era of relatively stable annual fees is over for many travel cards.
What surprises me is how long American waited. Holding the fee at $99 since 2018 felt almost old-fashioned in a market where other cards were already pushing higher. Now the gap is closing. The airline is pairing the increase with a handful of new benefits that try to soften the blow. Whether those extras actually deliver enough value depends entirely on how you travel and spend.
The Exact Fee Changes and Timeline
Let’s get the numbers straight. The Citi AAdvantage Platinum Select World Elite Mastercard moves from $99 to $150. The Citi AAdvantage Business Mastercard follows the same path to $150. Both changes become active on January 24. Existing cardholders will see the higher fee on their next annual billing cycle after that date. New applicants will pay the elevated amount from the start once the transition is complete.
I always tell people to check their statement carefully around that window. Sometimes the first higher fee appears sooner than expected depending on the anniversary date of the account. A quick call to the issuer can clarify the exact timing for any individual card.
New Benefits That Arrive With the Higher Fee
American is not simply raising the price and walking away. Several new or expanded perks are coming along for the ride. The most noticeable additions include a credit of up to $120 every four years that can be used toward Global Entry or TSA PreCheck. That is a practical benefit for anyone who travels enough to justify the trusted traveler programs. There is also a $100 annual statement credit for in-flight purchases. Food, drinks, Wi-Fi, and other onboard extras now come with a built-in rebate.
Hotel spending gets a boost too. Bookings made through the airline’s own portal will earn 3X AAdvantage miles. That is a meaningful jump for travelers who already plan stays around their flight itineraries. These extras are designed to make the higher fee feel less painful. The question is whether the average cardholder will actually use them enough to come out ahead.
The real value of any rewards card lives in the gap between what you pay and what you actually redeem. Everything else is marketing.
How the New Perks Stack Up Against the Extra Cost
Let’s do some simple math. The consumer card is going up by $51 a year. The $100 in-flight credit alone can cover that increase and still leave money on the table if you buy food or internet on board even a couple of times. The TSA PreCheck or Global Entry credit appears only once every four years, so its annual value is roughly $30. Hotel bonus miles depend entirely on how much you spend through the portal. Someone who books a few nights a year might earn an extra few thousand miles. Someone who rarely uses the portal will see almost nothing.
In my experience the people who benefit most from these cards already fly American enough to hit elite thresholds or at least redeem miles regularly. Casual users who keep the card mainly for the occasional free checked bag or priority boarding may find the higher fee harder to justify. It is worth running your own numbers before the January deadline arrives.
Broader Industry Trend Toward Higher Fees
American is not acting in isolation. Premium travel cards across the industry have seen steep fee increases in recent years. Some of the best-known premium products now sit well above $500 or even $700. The logic is the same everywhere: banks and airlines want higher-spending customers who will use the benefits and generate more transaction volume. Lower-fee cards still exist, but the mid-tier products that used to sit comfortably under $100 are slowly drifting upward.
I have watched this pattern for a while. Each increase is framed as an improvement package rather than a pure price hike. Sometimes the new benefits are genuinely useful. Other times they feel like padding. The smart approach is to ignore the marketing language and calculate personal return. If the extra perks match your actual spending, the higher fee can still be a bargain. If they do not, it is perfectly reasonable to look for alternatives or simply cancel.
What Frequent Flyers Should Consider Right Now
Anyone who already holds one of these cards has a decision to make before late January. Start by pulling the last twelve months of statements. Look at how many times you used the free checked bag, priority boarding, or any lounge access if applicable. Then estimate how often you buy food or drinks on board. Finally, check whether you have used or plan to use Global Entry or TSA PreCheck. Those three data points will tell you most of what you need to know.
Some people will discover the new benefits more than cover the increase. Others will realize they have been carrying the card mostly out of habit. There is no universal answer. Travel patterns differ too widely. A consultant who flies every week lives in a different world from a family that takes two leisure trips a year.
- Review your actual redemption history for the past year
- Estimate realistic use of the new in-flight credit
- Decide whether the trusted traveler credit matters to you
- Compare the total package against other cards you already carry
- Set a calendar reminder for early January so the decision does not sneak up
The Business Card Side of the Story
The business version of the card is also moving to $150. For small business owners and independent contractors the calculation can look different. Business travel often includes more hotel nights and more in-flight spending. The 3X hotel earning through the portal may deliver more value when the company is paying for rooms. The in-flight credit can offset meals that would otherwise come out of the business account. Still, the same discipline applies. Track the actual benefits used rather than the theoretical maximum.
I have spoken with several owners who keep the business card mainly for employee travel management and simplified expense tracking. For them the fee increase is simply another cost of doing business. Others who travel less frequently may decide the card no longer earns its keep.
How Miles Programs Fit Into the Bigger Picture
Airline loyalty programs have become sophisticated profit centers. The miles themselves are sold in bulk to banks. The more cards that sit in wallets and generate spend, the more revenue flows back to the airline. Raising the annual fee is one way to increase that revenue without touching ticket prices directly. At the same time the airline has to keep the product attractive enough that people do not simply walk away.
That balancing act is delicate. Push the fee too high and churn rises. Keep it too low and the airline leaves money on the table. American appears to have decided that $150 still sits in the acceptable range for its mid-tier cards, especially once the new credits are factored in. Time will tell whether cardholders agree.
Practical Steps for Current Cardholders
If you currently hold either card, the next few weeks are useful for evaluation. Log into your account and pull a full year of transactions if possible. Note every time you used a card-specific benefit. Then look at the new benefits and honestly assess how often you would use them. The $100 in-flight credit is straightforward. The trusted traveler credit is more of a long-term play. The hotel multiplier only helps if you actually book through the airline portal instead of other channels.
Some people will find the math still works in their favor. Others will conclude it is time to switch or simply drop the card. There is no shame in either choice. Loyalty programs work best when they align with real behavior rather than aspirational travel dreams.
Looking Ahead at Future Changes
I would not be surprised to see more adjustments in the next couple of years. The rewards landscape moves quickly. Fuel prices, labor contracts, aircraft delivery delays, and competitive pressure all influence how aggressively airlines monetize their loyalty programs. Card fees are one of the more flexible levers available. Once one carrier moves, others often follow within a relatively short window.
For travelers the best defense is staying informed and flexible. Keep an eye on the benefits that matter most to you personally. Be willing to switch cards when the value equation changes. And never assume that a card you opened years ago still delivers the same return it once did. Markets evolve. So should the tools we use to navigate them.
The January 24 effective date gives everyone a clear deadline. Use the time wisely. Run the numbers. Decide whether the higher fee still fits your travel life. And if it does not, explore the alternatives before the new price locks in. That kind of deliberate approach has always served travelers better than simply accepting whatever the latest fee letter announces.
In the end these cards remain useful tools for the right people. The fee increase simply forces a fresh look at whether you are still one of those people. For some the answer will be yes. For others it will be time to move on. Either way, making the choice consciously is better than letting inertia decide for you.
Balancing Cost Against Real Everyday Value
One thing I keep coming back to is how personal these decisions remain. Two people can look at the exact same fee increase and reach opposite conclusions. A road warrior who buys meals on almost every flight will treat the $100 credit as free money. Someone who packs snacks and skips the Wi-Fi will see almost no benefit. The trusted traveler credit is worthless if you already have Global Entry or simply never fly enough to care about the security line.
That variability is why blanket advice rarely works. The only reliable method is to measure your own usage against the new cost. Spend an evening with your statements. Be honest about the benefits you actually touch. Then decide. The process takes less time than most people expect and usually produces a clear answer.
Final Thoughts Before the Deadline
American Airlines has drawn a line in the sand. The days of the $99 mid-tier rewards card are ending for these two products. In their place sits a $150 card with a few extra credits and a higher hotel earning rate. Whether that package still represents good value is a question only individual cardholders can answer. The information is public. The deadline is known. The rest is simply math and personal travel patterns.
I plan to revisit my own accounts before the end of the year. A few minutes of review now can prevent an unwelcome surprise in the new year. That small habit has saved me more money over time than almost any other financial practice related to travel. Perhaps it will do the same for you.