
Have you noticed how quickly market sentiment can shift around the biggest names in tech? One day the narrative feels unstoppable, the next a single note from an analyst firm sends ripples through portfolios. That is exactly what happened with Apple recently when shipment expectations for its latest phones came under sharper scrutiny. I have followed these cycles long enough to know that the numbers behind the phones matter far more than the glossy keynotes.
Why The Latest Apple Assessment Caught Attention
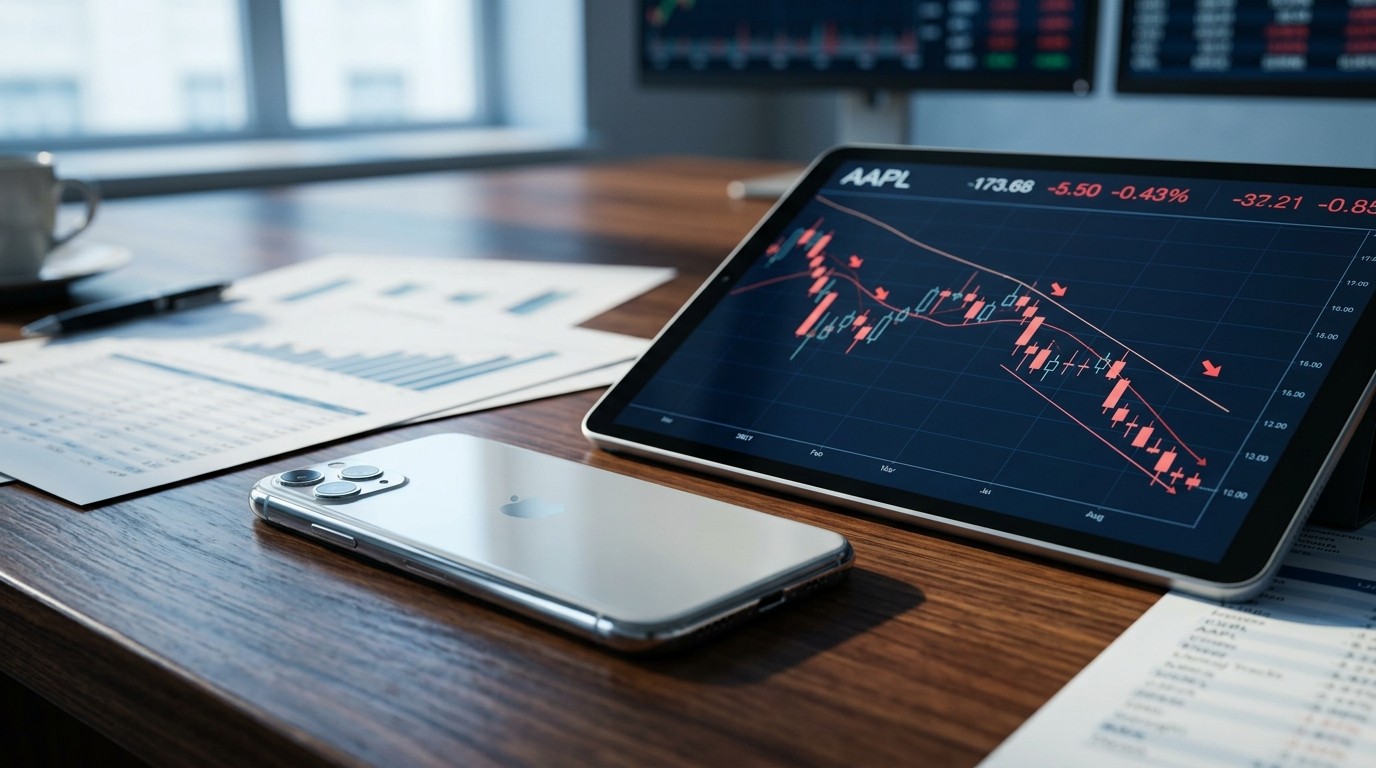
The firm behind the move shifted its stance from a clear buy recommendation to a more neutral hold. At the same time it trimmed the price target noticeably, pointing to limited near-term upside after a strong run. Shares had climbed roughly a quarter this year, lifted by progress in artificial intelligence features and steady growth in the subscription side of the business. Yet that advance also stretched the valuation to levels not seen in half a decade.
What stands out is the reasoning tied directly to unit shipments. Earlier cuts to production plans for the September and December quarters had been viewed as temporary supply constraints involving memory and processors. The expectation was that much of that volume could still be recovered later. Fresh commentary suggests the picture has changed. Demand itself appears softer than hoped for the newest Pro models. That distinction is crucial.
In my view, investors sometimes overlook how sensitive the stock can be to even modest adjustments in the core hardware story. Services continue to expand and the broader ecosystem remains powerful, but the phones still drive a large share of revenue and set the tone for everything else. When that piece looks less certain, the multiple starts to feel heavier.
The Valuation Stretch And Recent Momentum
Trading at around thirty-six times earnings marks a multi-year high. That kind of premium usually needs clear catalysts to stay justified. The company has delivered interesting integrations around intelligence tools and cloud capabilities, and the recurring revenue streams keep adding stability. Still, a stretch valuation leaves less room for disappointment.
Perhaps the most interesting aspect is how the market rewarded the longer-term narrative while the nearer-term hardware numbers quietly adjusted lower. Many holders focused on share gains and the services trajectory. Those themes remain attractive over a multi-year horizon. The question becomes whether the current price already reflects most of that optimism.
We continue to like the longer-term share gain and services story but believe the stock also requires a fundamental catalyst reset after its recent appreciation, particularly given trading at five-year valuation highs as phone shipments have been reduced.
That perspective captures the tension well. Support for the strategic direction sits alongside caution on timing and price. The stock slipped modestly right after the note circulated, a typical reaction when expectations get recalibrated.
Shipment Adjustments And What They Signal
Earlier reductions of roughly ten percent in planned units for the back half of the year looked manageable. Supply bottlenecks can ease. Demand softness is different. If the newest high-end models are not moving as briskly as modeled, the recovery path lengthens. Units that were expected to shift into the following calendar year may not fully materialize.
I have found that hardware cycles often reveal their true strength only after the initial launch window. Early enthusiasm can mask underlying trends until inventory data and channel checks accumulate. The latest assessment leans toward the view that the shortfall is no longer purely supply driven. That shift matters for how investors model the next several quarters.
Consider the broader context. The company has navigated multiple product transitions successfully. Innovation around processors, cameras, and software keeps the devices competitive. Yet consumer spending patterns, regional variations, and upgrade cycles all influence the final tallies. When those factors align less favorably, even a strong brand feels the impact.
Services Growth Versus Hardware Dependence
One consistent bright spot remains the expanding services portfolio. Subscriptions, content, payments, and cloud offerings generate higher-margin revenue that compounds over time. This segment has helped smooth the volatility inherent in device launches. Many long-term holders point to this mix shift as a key reason the overall business looks more resilient than it did a decade ago.
Still, the absolute scale of the phone business means it cannot be ignored. A softer shipment quarter affects not only hardware revenue but also the attached services that follow new device activations. The two pieces remain linked even as the balance gradually improves.
In practical terms, investors often weigh the durability of the services story against near-term hardware noise. The recent commentary acknowledges the former while flagging the need for a reset on the latter. That balanced take feels realistic rather than alarmist.
How Wall Street Views Differ
The more cautious stance stands somewhat apart from the broader consensus. A majority of covering analysts still lean constructive, with a sizable group maintaining positive ratings. A smaller portion already sat at neutral. Divergent opinions are healthy. They force clearer thinking about the assumptions baked into models.
Some observers emphasize the pipeline of intelligence features and the potential for deeper ecosystem lock-in. Others focus more tightly on unit volumes and the risk that elevated valuations leave little margin for error. Both angles contain truth. The weight each investor assigns depends on time horizon and risk tolerance.
I tend to favor a measured approach when a stock has already advanced substantially and valuation metrics sit at cycle highs. That does not mean abandoning a high-quality name. It does mean checking whether the next leg of appreciation requires cleaner fundamental progress.
- Longer-term share gains in key markets remain plausible
- Services revenue continues its multi-year expansion path
- Near-term phone volumes look softer than earlier supply-focused explanations suggested
- Valuation sits at a five-year peak, reducing the cushion for misses
- A catalyst reset may be needed before the next sustained advance
What The Price Target Adjustment Implies
Lowering the target from a higher level to one that implies modest downside from recent closes sends a clear signal. The previous upside case has been dialed back. That does not equate to a deeply negative view. It simply recalibrates expectations after the stock has already delivered strong year-to-date performance.
Targets are estimates, of course. Markets move on new information and shifting narratives. Yet the direction of the change matters. When an analyst who previously saw meaningful upside now sees limited room or slight pressure, it encourages holders to reassess position sizes and entry points.
For those who have ridden the advance, the development may prompt profit-taking or at least a pause in adding exposure. For potential new buyers, the combination of stretched multiples and softer shipment signals could justify waiting for a clearer fundamental inflection.
Broader Context Of Tech Valuations
Apple is not alone in commanding premium multiples. Many large technology platforms trade at elevated levels supported by growth in artificial intelligence related spending and recurring revenue models. The difference lies in the relative maturity and the weight of the hardware segment. Pure software or cloud names sometimes justify higher ratios more easily when growth remains robust.
When a company still derives a substantial portion of sales from physical devices, the market tends to demand clearer evidence that volumes can stabilize or recover. That is the hurdle the latest commentary highlights. Until shipment trends improve or the services mix advances further, the premium may face ongoing scrutiny.
Looking back at prior cycles, the stock has often rewarded patience through periods of temporary softness. Product refresh strength, regional recoveries, or new category contributions have eventually restored momentum. The current environment includes the added variable of rapid advances in on-device intelligence, which could influence upgrade behavior in ways that are still unfolding.
Practical Considerations For Portfolio Decisions
Anyone evaluating the shares right now faces a classic tension between quality and price. The underlying business retains formidable competitive advantages: brand loyalty, high switching costs, and a deepening services layer. Those attributes support a constructive multi-year outlook for many investors.
At the same time, the combination of a rich valuation and revised shipment expectations introduces near-term uncertainty. Adding to a position after a strong run and into a downgrade requires conviction that the fundamental reset will prove temporary and limited. Reducing exposure or simply holding steady can feel more comfortable until clearer data arrives.
Position sizing matters. A core long-term allocation can coexist with a more cautious stance on incremental buys. Dollar-cost averaging through any weakness remains a strategy some prefer, provided the overall thesis stays intact. Others wait for confirmation that demand has stabilized before committing fresh capital.
| Factor | Current Observation | Investor Implication |
| Valuation | Near five-year high | Less margin for error |
| iPhone shipments | Reduced, demand questions rising | Near-term revenue caution |
| Services | Continued expansion | Supportive longer-term offset |
| Analyst consensus | Mostly constructive overall | Mixed signals require independent judgment |
| Year-to-date performance | Strong double-digit gain | Profit-taking pressure possible |
Historical Patterns And Potential Paths Forward
Past periods of shipment adjustment have sometimes resolved more quickly than feared. Supply chain improvements, stronger marketing, or better-than-expected reception of new features can lift volumes. The reverse has also occurred when macroeconomic headwinds or competitive pressures lingered longer than expected.
The current situation includes the overlay of artificial intelligence capabilities rolling out across the product line. If those features drive higher attachment rates or accelerate replacement cycles, the demand narrative could improve. Conversely, if consumers treat the new tools as incremental rather than must-have, the upgrade incentive stays muted.
I have watched enough product cycles to appreciate that early read-throughs are imperfect. Channel inventory, regional sell-through, and carrier data all evolve over subsequent months. The initial assessment is useful as a flag rather than a final verdict.
Balancing Optimism With Realism
It is easy to become either overly defensive or complacently bullish after a single research note. A more useful posture sits in the middle. Acknowledge the longer-term strengths while respecting the near-term caution signals. The services trajectory and ecosystem advantages have not disappeared. The shipment outlook simply looks less supportive of immediate multiple expansion.
For many portfolios the shares still belong as a foundational holding, especially for those focused on durable competitive positions and recurring revenue growth. The recent development mainly affects the urgency of adding more exposure at current levels. Waiting for either a more attractive entry or clearer evidence of volume stabilization can reduce the risk of buying into temporary softness.
Market reactions often overshoot in both directions. A modest pullback after a strong run and a cautious note is ordinary. Whether it deepens or stabilizes will depend on upcoming data points around actual sell-through and any updates to production plans.
Key Takeaways For Thoughtful Investors
The core message centers on recalibration rather than reversal. The longer-term case built around share gains and services expansion retains support. The shorter-term hardware picture has grown cloudier, and the valuation leaves limited room for further disappointment. That combination justifies a more neutral posture until the fundamental picture clarifies.
Investors who already hold significant positions might consider whether the risk-reward still favors adding. Those on the sidelines gain a reason to stay patient. Across both groups, monitoring upcoming unit trends and any shifts in the services contribution will provide the most useful guidance.
- Recognize that valuation peaks increase sensitivity to operational updates
- Distinguish supply-driven shipment cuts from demand-driven ones
- Keep the multi-year services and ecosystem story in perspective
- Allow room for the possibility that demand softens further or stabilizes
- Adjust position sizes according to personal time horizon and conviction
Ultimately the decision rests on individual circumstances. Some will view any weakness as an opportunity to accumulate a high-quality compounder at a slightly better price. Others will prefer to wait for confirmation that the shipment trajectory has bottomed. Both approaches can be rational depending on the rest of the portfolio and risk parameters.
Looking Beyond The Immediate Headline
Headlines focus on the downgrade and the reduced target. The deeper discussion involves how the business evolves when hardware growth moderates while higher-margin services continue climbing. That transition has been underway for years and remains incomplete. Progress on that front will likely determine the stock’s path more than any single quarter’s unit numbers.
Innovation around intelligence features adds another layer. If those tools meaningfully enhance the user experience and encourage upgrades, the hardware story can regain strength. If adoption proves gradual, the services engine will need to carry more of the growth burden in the interim.
Either way, the company enters this phase from a position of considerable strength. Cash generation stays robust, the balance sheet provides flexibility, and the brand continues to command pricing power in most markets. Those structural advantages do not vanish because of one cautious research note.
What changes is the near-term risk-reward calculation. After a substantial advance and at elevated multiples, the margin of safety narrows. That is the practical takeaway many investors will weigh as they review their exposure.
Final Thoughts On Navigating The Uncertainty
Markets rarely move in straight lines, and neither do the narratives around major technology names. Periods of strong appreciation followed by cautious recalibration are common. The present moment fits that pattern. Shipment concerns have introduced a note of caution after a period of enthusiasm driven by artificial intelligence progress and services momentum.
Staying grounded means holding both ideas at once: the longer-term appeal of the franchise remains intact, while the shorter-term hardware outlook has become less supportive of further multiple expansion. Investors who can maintain that dual perspective are better positioned to respond thoughtfully rather than reactively.
Whether the next few quarters bring a faster recovery in volumes or a more prolonged adjustment, the underlying competitive position continues to offer a foundation for patient capital. The current environment simply asks for a bit more selectivity around entry points and position sizing. That kind of discipline has rewarded investors through previous cycles, and it remains relevant today.
In the end, the story is less about a single downgrade and more about the ongoing balance between hardware realities and the expanding higher-margin businesses that sit on top of them. Keeping that balance in view helps cut through the noise and focus on what actually drives durable value over time.