
Have you noticed how quickly energy markets can turn when one piece of the global puzzle shifts? Right now, Asia finds itself in a frantic scramble for thermal coal just as winter approaches, with prices climbing to levels not seen in two years. The combination of disrupted natural gas flows and strained crude product markets has utilities across the region racing to secure the so-called dirty fuel. I’ve been watching these developments closely, and the speed of this shift feels different from previous cycles.
Why Asia Is Suddenly Stockpiling Coal Again
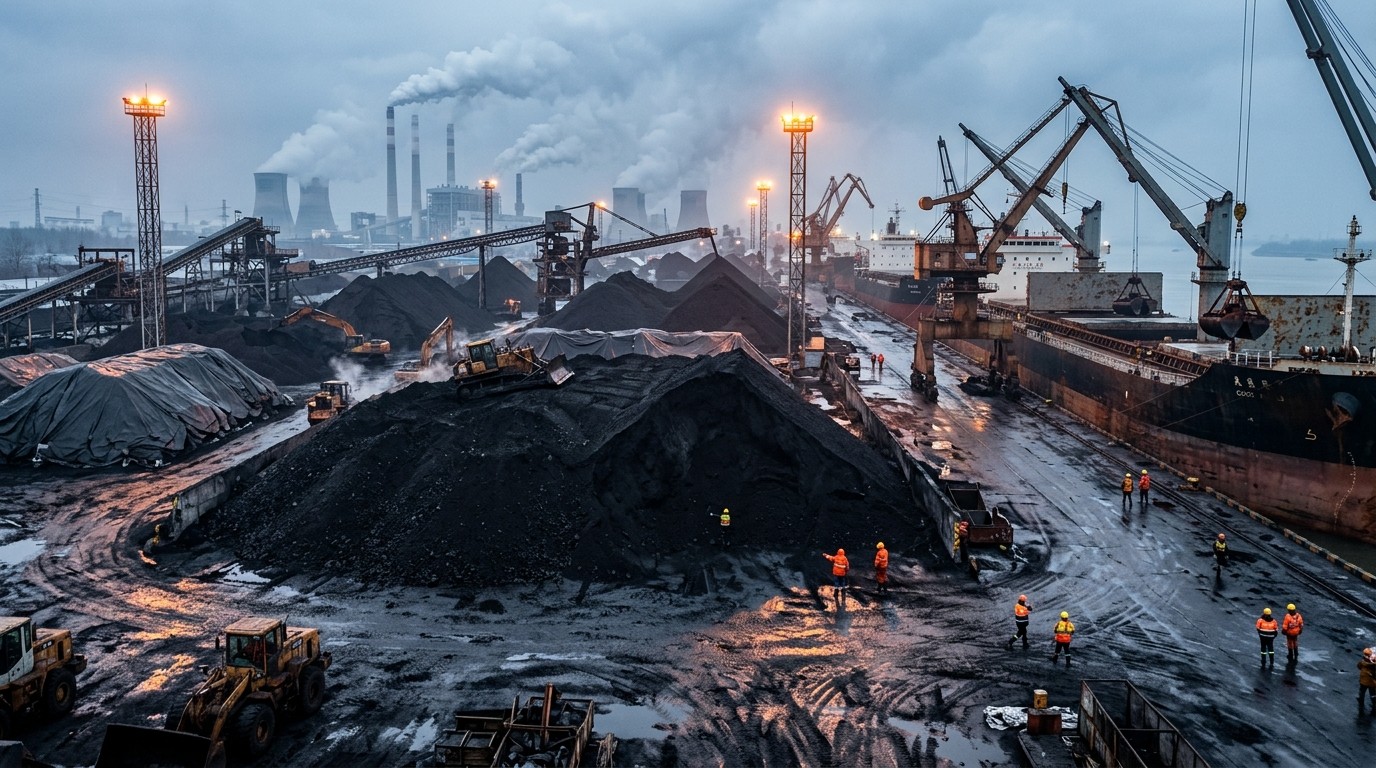
Winter always brings higher heating demand, but this year the pressure feels sharper. Newcastle coal futures, the key Asian benchmark, have jumped more than 40 percent since the start of the year. On one recent trading day they closed at their strongest point since August 2024. If the market holds above the $150-a-ton mark, many traders believe a further breakout becomes likely.
What changed? A refining squeeze created by damage to Russian processing capacity and interruptions along critical shipping routes has made natural gas and heating oil more expensive. Utilities faced with those higher costs are quietly switching back to coal wherever they can. It is a practical decision rather than an ideological one. Power plants need reliable fuel, and coal is currently the cheaper and more available option in several markets.
I find this pivot particularly interesting because it undercuts the long-term narrative that coal demand would steadily fade. Instead, short-term reliability is winning. Analysts recently noted that the refining problems have made the outlook for thermal coal demand more resilient than expected. One group even lifted its long-term Newcastle price forecast by a few percentage points to around $125 a ton. That kind of revision rarely happens without solid reasons.
The Role of Global Supply Disruptions
Two major factors sit at the center of this story. First, repeated strikes on refining infrastructure have reduced the availability of certain refined products. Second, shipping complications through a vital waterway have tightened energy flows more broadly. Together they have pushed buyers to look for alternatives that can keep the lights on and the heat running.
Coal has filled that gap faster than many expected. In my view, this is less about a permanent return to coal and more about pragmatic risk management. When gas prices spike and oil products become harder to secure, plant operators do what they must. Stockpiling becomes the logical next step before temperatures drop further.
The numbers tell part of the story. Prices have already risen sharply, yet demand continues to firm. That combination often signals further upside if weather turns colder than forecast or if additional supply issues appear.
China’s Production Constraints Add Pressure
China remains the largest piece of the Asian coal puzzle. Output there has declined by more than 3 percent over the first eight months of the year. A serious mining accident earlier triggered widespread safety inspections and extended shutdowns. Those measures were necessary, yet they removed meaningful volumes from the market at an awkward time.
Industry observers expect more mines to receive approval to restart after roughly four months of suspension. Even so, a rapid rebound looks unlikely. Approvals take time, and ramping production safely takes even longer. Any fresh supply will arrive with a lag. That lag keeps the market tight just when winter stockpiling peaks.
I’ve seen similar patterns after previous safety campaigns. Production recovers eventually, but the interim period often features higher prices and elevated buyer anxiety. This time feels no different. Chinese utilities and traders are competing for available cargoes, which adds further support to regional benchmarks.
Weather Forecasts Offer a Potential Soft Landing
Not every signal points to higher prices. Weather models currently suggest above-normal temperatures across much of Asia, linked to a strong El Niño pattern. Milder conditions would reduce heating demand and ease some of the pressure on coal inventories.
That prospect provides a degree of relief. Yet forecasts can shift, and a single cold snap can quickly erase the benefit of milder averages. Utilities know this. They prefer to build stockpiles early rather than risk running short later. The result is continued buying even while the longer-term weather outlook looks relatively friendly.
Perhaps the most interesting aspect is how these competing forces interact. Strong demand from stockpiling meets potential relief from warmer weather. The market will decide which factor dominates once winter truly arrives.
How Utilities Are Adjusting Their Fuel Mix
Power generators across Asia have limited options when gas and oil products become expensive. Many plants can burn coal with only modest operational changes. That flexibility is now being used more actively. Some operators are maximizing coal burn rates while carefully managing emissions within regulatory limits. Others are securing longer-term coal contracts to lock in current prices before they climb further.
This shift is not uniform. Countries with stricter environmental rules move more cautiously. Those with greater energy security concerns act faster. The common thread is the search for reliable, affordable supply during the colder months.
In my experience, these tactical switches often last longer than initially planned. Once plants reconfigure logistics and staffing around coal, reversing course requires another set of decisions. That inertia can keep demand elevated even after the original price spike fades.
- Utilities prioritize inventory builds before peak heating season
- Coal offers cost advantages while gas and oil products remain elevated
- Operational flexibility allows relatively quick fuel switching in many plants
- Longer-term contracts provide price certainty amid market volatility
Price Dynamics and Trader Positioning
Newcastle futures have become the clearest barometer of regional tightness. The recent climb above previous resistance levels has attracted both physical buyers and financial participants. Sustained trading above $150 a ton would likely draw additional speculative interest. Markets love round numbers, and that threshold has psychological weight.
Physical cargoes are also firming. Spot prices for high-quality thermal coal have tracked the futures move higher. Buyers who delayed purchases earlier in the year now face steeper costs. Some are absorbing the increase. Others are exploring lower-grade material or alternative sources, though quality constraints limit those options for many power stations.
I keep coming back to the resilience comment from market analysts. When professional observers raise their long-term price assumptions, it usually reflects a genuine reassessment of structural demand. That does not guarantee further immediate gains, but it does suggest the floor may sit higher than previously assumed.
Broader Implications for Energy Security
This episode highlights an uncomfortable reality. Diversified energy systems still depend on reliable baseload options during periods of stress. When gas markets tighten and refined products face disruption, coal remains a readily available backstop in many Asian economies. That fact sits uneasily with longer-term climate goals, yet short-term reliability often takes priority.
Governments face the same tension. Encouraging cleaner generation is important. Ensuring households and industries stay warm and productive through winter is equally critical. The current scramble shows how quickly policy preferences can bend when physical supply feels uncertain.
Looking ahead, the next few months will test how well the region balances these competing needs. If winter proves milder than average, the pressure may ease and prices could stabilize. If cold weather arrives in force or further supply interruptions occur, the upward move in coal could extend.
The refining squeeze has made the long-term outlook for thermal coal demand more resilient than many expected.
What Market Participants Should Watch Next
Several indicators will shape the path from here. Chinese mine restart progress remains central. Any acceleration in approvals and actual production would ease tightness. Conversely, further delays would keep support under prices. Weather data across Northeast and Southeast Asia will also matter. Cumulative heating degree days often drive the final stretch of winter demand.
Refining margins and product availability deserve attention too. If the squeeze on gasoil and related fuels persists, the incentive to burn coal stays elevated. Shipping rates and freight availability for bulk carriers can influence delivered costs as well. Finally, inventory levels at major Asian ports and power plants will reveal whether stockpiling has already reached comfortable levels or still has further to run.
I’ve found that tracking these variables together provides a clearer picture than focusing on any single data point. Markets rarely move in straight lines, and the interplay between supply recovery, weather, and competing fuel prices will determine the eventual outcome.
Longer-Term Questions for Thermal Coal
Beyond the immediate winter season, this episode raises broader questions. How permanent is the renewed interest in coal? Will utilities maintain higher coal readiness as a hedge against future gas and oil volatility? Or will the current surge prove temporary once supply chains normalize?
Answers will vary by country. Some nations continue investing in renewable capacity and gas infrastructure at pace. Others face slower transition timelines and retain larger coal fleets. The common challenge is managing the gap between long-term goals and near-term reliability needs.
Price signals matter here. If coal remains relatively competitive during periods of stress, the economic case for keeping capacity available strengthens. If cleaner alternatives deliver consistent reliability at comparable cost, the shift away from coal can resume. Right now the market is reminding everyone that reliability still carries a premium.
Practical Considerations for Market Watchers
Anyone following energy markets closely should keep several practical points in mind. First, benchmark prices can move quickly once psychological levels break. Second, physical availability often lags futures price action, creating temporary dislocations. Third, policy responses can appear with little warning, whether in the form of export restrictions, import incentives, or safety-driven production limits.
Diversification remains a useful approach. Relying on a single fuel source leaves systems vulnerable when disruptions hit. The current scramble illustrates that principle in real time. Countries and companies that maintain flexible fuel options generally navigate these periods with less stress.
I also pay attention to the tone of official statements. When authorities begin highlighting energy security more frequently, it often precedes concrete measures that affect markets. Those measures can support prices further or, in some cases, introduce new supply to calm them.
Seasonal Patterns and Historical Context
Winter stockpiling is not new. Asian buyers have followed similar patterns for decades. What feels different this cycle is the combination of upstream refining problems and shipping constraints arriving at the same time. Previous winters featured individual challenges. The simultaneous appearance of several has amplified the response.
Historical price spikes often reverse once the peak demand season ends and inventories rebuild. Yet the starting point matters. When prices begin the season already elevated, the eventual decline can be slower. The current two-year high provides that elevated base. Whether it holds depends on how the next few months unfold.
Looking back at earlier tight markets offers useful perspective. Recoveries in production and milder weather have previously brought relief. At the same time, structural shifts in demand sometimes leave prices at higher plateaus. The resilient demand outlook suggested by recent analysis points in that direction, though confirmation will take time.
Balancing Immediate Needs and Future Goals
The tension between keeping systems running today and building cleaner systems for tomorrow sits at the heart of this story. No one disputes the importance of reducing emissions over the long run. Equally, few dispute the need for reliable power and heat when temperatures fall. The current coal scramble shows how those priorities collide in practice.
Successful navigation requires clear-eyed assessment of risks. Assuming uninterrupted access to preferred fuels can leave systems exposed. Maintaining backup options, even less preferred ones, provides insurance. That insurance carries costs, both financial and environmental. Yet the alternative of shortfalls carries its own set of consequences.
In my view, the most constructive approach acknowledges both realities. Accelerate the deployment of reliable low-carbon capacity while recognizing that transitional fuels will remain relevant for some time. The precise mix will differ by market, but the principle of flexibility applies broadly.
Final Thoughts on the Winter Outlook
Asia’s current push to secure coal reflects a rational response to disrupted energy markets and the approach of winter. Prices have already reached two-year highs, and the possibility of further gains remains if key thresholds hold. Chinese production constraints and the refining squeeze provide fundamental support, while milder weather forecasts offer a potential counterbalance.
The coming months will reveal which forces prove stronger. Utilities will continue building inventories where they can. Traders will watch Chinese mine restarts and temperature trends closely. Policymakers will balance security concerns against longer-term transition goals.
What stands out most is the reminder that energy markets remain interconnected and sensitive to disruption. A problem in one segment quickly spills into others. Coal has stepped into the gap this time. How long it stays there depends on how quickly the broader system stabilizes.
For now, the focus stays practical. Secure fuel. Build stocks. Monitor the weather. Those steps will dominate decision-making until the coldest period passes. After that, attention can return to the larger questions of transition speed and system resilience. The current scramble simply underscores how important those questions remain.
Market conditions can change rapidly. The same factors supporting higher coal prices today could ease tomorrow if production recovers faster or temperatures stay elevated. Conversely, any fresh disruption could extend the tightness. Staying attentive to the full set of signals offers the best chance of understanding the path ahead.
This winter will serve as another test of Asia’s energy flexibility. The region has navigated similar challenges before. The combination of circumstances this year makes the test particularly visible. How participants respond will shape not only prices over the next few months but also perceptions of risk for seasons further out.
Ultimately, the story is less about any single fuel and more about the ongoing need for reliable, affordable energy when conditions tighten. Coal is filling that role at present. Whether that continues will depend on developments still unfolding across mines, refineries, shipping lanes, and weather patterns. The market will keep adjusting as those pieces move.