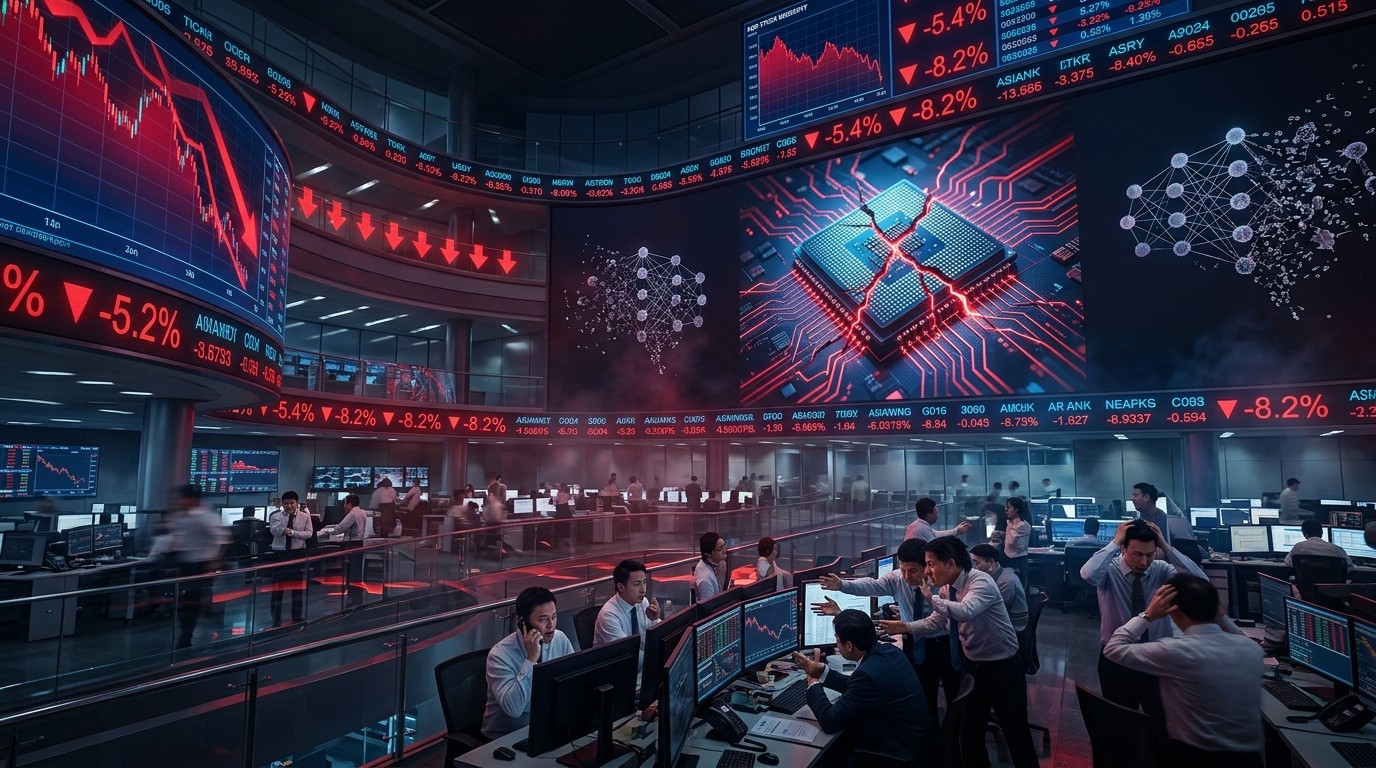

Have you ever watched a market that looked unstoppable suddenly stumble? That is exactly what happened across Asian technology shares this week. One moment investors were celebrating the artificial intelligence boom, the next they were staring at double-digit percentage drops on some of the biggest names in the sector. I found myself checking the numbers more than once because the speed of the move felt almost unreal.
Why Asian Tech Shares Are Suddenly Under Heavy Pressure
The sell-off did not appear out of nowhere. It followed a rough session on Wall Street where technology stocks led the broader market lower after inflation data came in hotter than many expected. That reading raised fresh questions about whether the Federal Reserve might keep interest rates higher for longer or even consider further increases. Higher borrowing costs matter a great deal when companies need to fund enormous data center projects and advanced manufacturing facilities.
In South Korea, the damage was especially clear. SK Hynix shares fell more than 10 percent in a single trading day. Samsung Electronics dropped around 7 percent. Related names such as LG Innotek, Seoul Semiconductor and Samsung SDI also posted steep losses. Across the water in Japan, SoftBank Group tumbled nearly 8 percent while equipment makers Advantest and Tokyo Electron each declined more than 5 percent. Renesas Electronics joined the list of losers as well.
These companies sit at the heart of the current technology cycle. Memory chips, logic processors, testing equipment and investment vehicles all feed into the same story: the massive build-out of artificial intelligence infrastructure. When investors start questioning how that build-out will be financed, the entire ecosystem feels the pressure.
The Real Concern Behind Higher Interest Rates
U.S. Treasury yields climbing above 5 percent changes the math for almost every large capital project. Building AI data centers requires billions of dollars. Expanding semiconductor capacity demands even more. When the cost of borrowing rises, companies and their customers must rethink the pace of spending. Some projects may still move forward, but the risk of delays or scaled-back plans grows.
Chief executives at major chip and networking firms have already flagged financing as a potential headwind. One leader described it as a challenge that could prove larger than shortages of chips or power. That kind of comment does not go unnoticed. Markets tend to price in uncertainty quickly, and that is precisely what we saw this week.
I have watched similar episodes before. When rates move higher, growth stocks often take the first hit because their valuations rest on future cash flows. Discount those cash flows at a higher rate and the present value falls. Simple finance, but painful in practice.
AI Demand Versus AI Financing
Here is where the conversation gets interesting. Demand for AI computing power still looks robust. Hyperscalers continue to talk about long-term needs for more capacity. Cloud providers keep signing large contracts. The technology itself keeps advancing. So the underlying need has not disappeared overnight.
What has changed is the cost of meeting that need. Higher yields raise the expense of financing these builds. Investors are now looking harder at balance sheets, debt levels and the structure of long-term contracts. That scrutiny is healthy, even if it creates short-term volatility.
Higher yields raise the cost of financing these builds, and investors are right to focus on balance sheets and contract structure, but rates are a financing question, not a demand question.
That perspective feels right to me. The distinction between temporary funding pressure and a true collapse in demand matters a lot for anyone trying to decide whether to buy the dip or stay on the sidelines.
What Could Actually Change the Outlook
Analysts who remain constructive on the sector point to a few clear warning signals. Cuts in hyperscaler capital expenditure plans would be one. Canceled contracts would be another. Falling rental prices for high-end GPUs would also raise red flags. Until those signs appear, many still view the current pullback as a financing issue rather than a demand problem.
In my view, the AI infrastructure story remains in its early chapters. The amount of computing power required for training larger models and serving more users continues to grow. Energy constraints and chip supply have been the usual bottlenecks. Financing is simply the newest one to enter the conversation.
How the Losses Spread Across the Region
South Korean chipmakers felt the sharpest moves. Memory producers sit close to the center of AI server demand because high-bandwidth memory and advanced DRAM play critical roles in modern accelerators. When sentiment sours, those names often move first and farthest.
Japanese equipment suppliers also came under pressure. Companies that sell testing tools and wafer fabrication equipment depend on the capital spending plans of chip manufacturers. Any slowdown in those plans translates into softer order outlooks. SoftBank Group, with its broad technology investments, reflected the wider risk-off mood as well.
The pattern is familiar. When global investors reassess risk, Asian technology shares frequently absorb a meaningful share of the selling. Liquidity, valuation levels and the concentration of growth exposure all play a part.
Looking at the Bigger Market Picture
The Nasdaq Composite fell nearly 2 percent in the session that preceded the Asian moves. The S&P 500 declined more than 1 percent. Even the Dow posted a small loss. Technology led the weakness, which is typical when rate concerns intensify. Growth stocks tend to be more sensitive to changes in the discount rate applied to future earnings.
Perhaps the most interesting aspect is how quickly the narrative shifted. Only weeks earlier the conversation centered on whether AI spending would keep accelerating. Now the focus has moved to how that spending will be funded if rates stay elevated. Markets love a clean story, and this one changed almost overnight.
I keep coming back to the same question: does higher financing cost kill the boom, or does it simply slow the pace for a while? History suggests the latter in most cases, especially when the underlying technology remains compelling. Still, each cycle has its own characteristics.
Practical Considerations for Investors Right Now
Volatility like this often creates both risk and opportunity. Buying high-quality names after a sharp drop can work well if the long-term thesis remains intact. At the same time, rushing in without checking balance sheet strength can lead to further pain if conditions worsen.
- Check debt levels and upcoming refinancing needs for any company under consideration
- Review recent commentary on capital expenditure plans from major customers
- Watch for signs that contract structures are becoming more conservative
- Pay attention to GPU rental pricing trends as an early demand indicator
- Consider position sizing carefully while uncertainty remains elevated
These steps sound basic, yet many investors skip them when prices move quickly. The temptation to act on emotion is real. Taking a moment to review the fundamentals usually pays off.
Why Balance Sheets Matter More Than Ever
Companies with strong cash positions and limited near-term debt maturities sit in a better spot. They can continue investing even if capital markets become less friendly. Firms that rely heavily on external financing face tougher choices. They may need to slow projects, raise equity at less attractive valuations, or accept higher interest costs.
Contract structure also deserves attention. Long-term agreements with clear pricing and volume commitments provide more visibility than short-term or flexible arrangements. In an environment of rising rates, visibility becomes a valuable asset.
I have seen investors overlook these details in previous cycles and then express surprise when certain names underperformed. The current environment rewards a closer look at the financial foundation supporting the growth story.
The Role of Inflation Data in the Current Mood
The recent inflation reading that exceeded expectations acted as a catalyst. Markets had been pricing in a relatively smooth path for monetary policy. Hotter numbers forced a reassessment. Traders began to assign higher odds to prolonged higher rates or even additional tightening. That shift in probability alone was enough to pressure growth-oriented sectors.
Technology hardware and semiconductor stocks often trade with an eye on the broader rate environment. Their customers make multi-year investment decisions. When the cost of capital changes, those decisions get revisited. The Asian market reaction simply reflected the global nature of the supply chain.
Separating Temporary Noise from Structural Change
Not every sharp drop signals a fundamental break. Sometimes markets overshoot in both directions. The key is to distinguish between a temporary financing squeeze and a lasting reduction in demand. So far the evidence still points more toward the former.
Demand signals would look different. We would see major cloud providers announcing meaningful cuts to their spending plans. We would hear about delayed data center openings or reduced order volumes for advanced chips. GPU cloud rental rates would soften noticeably. None of those developments have become widespread yet.
That does not mean they cannot appear later. Conditions can change. But basing decisions solely on rate fears without waiting for demand confirmation risks missing the next leg of the cycle.
Historical Context for Rate-Driven Tech Sell-Offs
Previous periods of rising rates have produced similar episodes. Growth stocks underperformed for a time, valuations compressed, and then the strongest companies recovered once the rate path became clearer. The pattern is not guaranteed to repeat, yet it offers a useful reference point.
What feels different this time is the sheer scale of the capital required for AI infrastructure. The numbers involved are larger than many earlier technology build-outs. That scale amplifies the impact of higher financing costs. It also means the eventual winners may emerge even stronger if they can navigate the current environment successfully.
In my experience, the companies that maintain disciplined capital allocation during periods of uncertainty often gain share once conditions stabilize. The ones that overextend tend to face tougher recoveries.
Regional Differences Worth Noting
South Korean memory producers face a different set of dynamics than Japanese equipment makers. Memory pricing can move quickly with supply and demand shifts. Equipment orders tend to reflect longer-term capacity plans. Both groups felt the pressure this week, but the recovery paths may diverge depending on how the financing story evolves.
SoftBank Group represents yet another profile. Its portfolio includes a wide range of technology investments, some more sensitive to rates than others. The sharp decline in its shares reflected the broader risk-off tone rather than any single operational development.
Understanding these differences helps when deciding where to focus attention. Not every name in the sector will move in lockstep once the initial selling pressure eases.
Potential Catalysts That Could Stabilize Sentiment
Several developments could help calm the current anxiety. A cooler inflation reading in the coming weeks would reduce the probability of further rate increases. Clearer guidance from major technology companies on their financing plans would also help. Any sign that hyperscalers remain committed to their spending roadmaps despite higher costs would provide reassurance.
On the company side, strong quarterly results that demonstrate resilient demand would counteract some of the rate-driven concerns. Evidence that gross margins remain healthy even as capital intensity rises would be particularly welcome.
Markets often look for a reason to stop selling once the initial wave of fear has passed. The next few data points and earnings reports will play an important role in shaping that narrative.
Managing Risk While Staying Constructive
No one knows the exact path of interest rates from here. Inflation can surprise in either direction. Policy makers can shift their tone. Geopolitical events can intervene. Building a portfolio that can withstand a range of outcomes remains the sensible approach.
For those who believe the AI infrastructure cycle still has years to run, the current weakness may represent an opportunity to add exposure at more attractive levels. For those more cautious, reducing position sizes or waiting for clearer demand confirmation makes sense. Both approaches can be valid depending on individual risk tolerance and time horizon.
I tend to lean toward selective accumulation of high-quality names during periods of broad selling, provided the balance sheets look solid. That strategy has worked more often than not over longer periods, though it requires patience when volatility stays elevated.
The Broader Implications for Technology Investing
This episode serves as a reminder that even the strongest secular themes face periodic challenges. Artificial intelligence is transforming multiple industries, yet the path of adoption and investment is rarely linear. Financing conditions form one of the variables that can influence the speed of progress.
Investors who treat every dip as a permanent impairment risk missing significant upside. Those who ignore genuine warning signs risk larger losses. Finding the balance requires ongoing attention to both the technology fundamentals and the macro backdrop.
The current focus on financing costs is legitimate. It does not automatically invalidate the longer-term opportunity. Keeping that distinction clear helps avoid both excessive pessimism and unwarranted complacency.
Final Thoughts on Navigating the Current Environment
Asian technology shares delivered a clear message this week. Higher interest rates and concerns about funding the AI build-out can still move prices sharply lower, even when underlying demand appears solid. The magnitude of the declines, particularly in South Korean chipmakers, underscores how sensitive the sector remains to changes in the cost of capital.
At the same time, the absence of clear demand destruction leaves room for recovery once financing worries ease or companies demonstrate they can manage the higher costs. The distinction between a financing question and a demand question continues to matter.
For now, the prudent path involves careful analysis of balance sheets, contract quality and customer spending plans. Volatility is likely to remain elevated until the rate outlook becomes clearer. Those who stay disciplined through the noise often find themselves better positioned when the next positive catalyst arrives.
The AI infrastructure story is far from finished. How companies and investors navigate the current chapter will influence who benefits most from the chapters still to come. Watching the data closely and maintaining a flexible mindset remains the best approach in an environment that can shift quickly.