

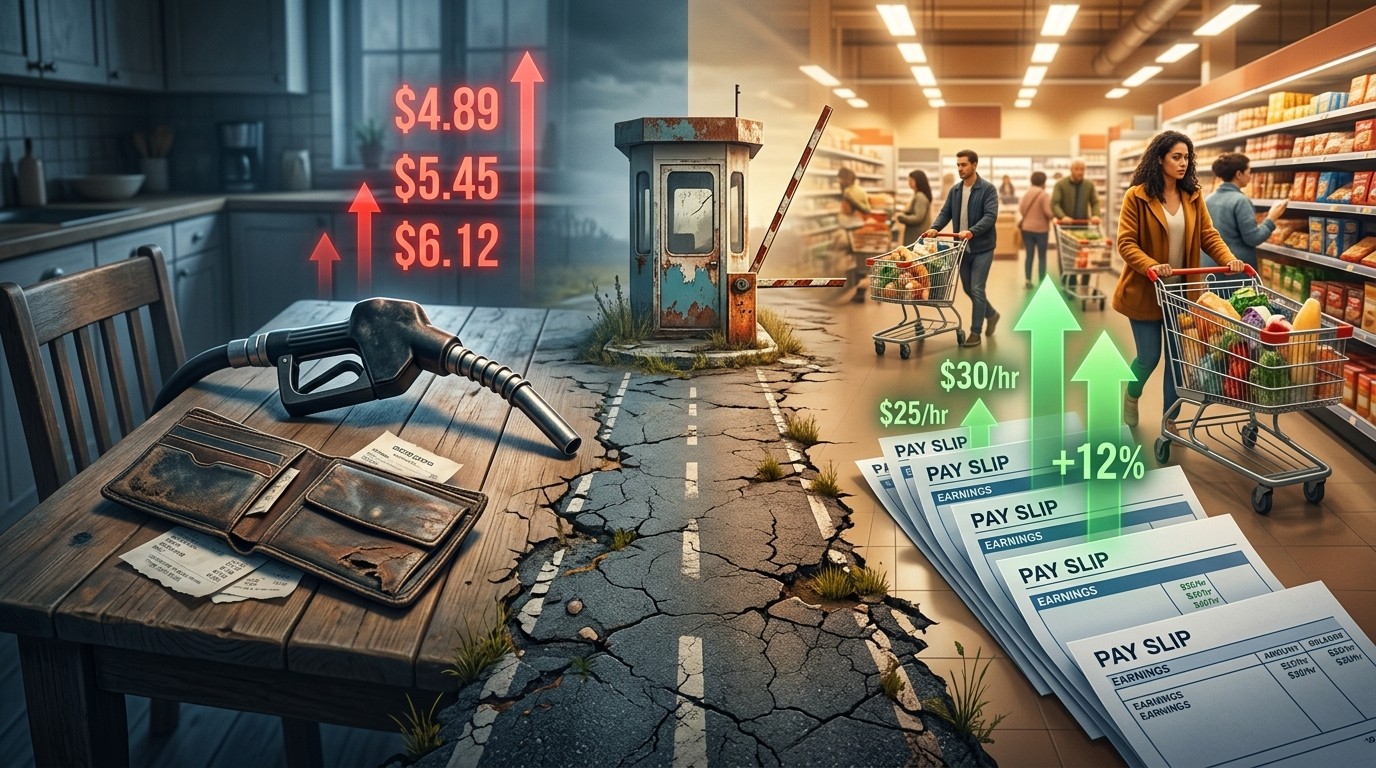

Have you ever watched the price at the pump climb for months and wondered whether this time really is different? I have. Most of us have. The latest numbers show headline inflation running at 3.7 percent while the core measure sits near 2.6 percent. That gap is not random noise. It is almost entirely energy, and energy is telling a story that many commentators prefer to ignore. The real question is not how high the number is. The real question is whether anyone’s paycheck is rising fast enough to keep paying those higher prices. That single distinction separates the kind of inflation that burns itself out from the kind that embeds and stays.
The Critical Difference Between Good And Bad Inflation
Prices can climb for two very different reasons. In the first case, households and businesses are earning more and choosing to spend that extra income. Demand pulls prices higher. Companies enjoy wider margins. Those margins eventually flow into wages. Higher wages then support the higher prices. The loop closes. Economists sometimes call this demand-pull inflation. I simply call it good inflation because every step is financed by real output and real income.
The second case looks similar on the surface and feels identical at the checkout counter. A supply disruption hits. Oil gets more expensive because of geopolitics. A tariff raises the cost of imported goods. A memory-chip shortage pushes up the price of electronics. Costs rise, but incomes do not. Households must cut spending somewhere else to cover the new bill. That is bad inflation. It is a tax. It does not create the income needed to pay for itself. Over time it destroys the very demand that was supporting the higher price level.
I keep coming back to a simple analogy. Imagine a stretch of highway that everyone uses to get to work. The city installs a toll booth and steadily raises the fee. Half the drivers receive regular raises. The other half do not. Both groups feel the squeeze at first. Eventually the group without raises starts finding other routes or working from home more often. Traffic falls. The toll operator has little choice but to cut the fee to win customers back. High prices cured high prices. That is the mechanism at work right now in energy markets and, increasingly, in other supply-constrained areas.
What The Latest Inflation Report Actually Shows
Look past the headlines. September’s report delivered a 3.7 percent year-over-year increase in the overall consumer price index. Core inflation, which excludes food and energy, came in at 2.6 percent. The spread between those two numbers widened. Gasoline alone jumped 9.1 percent in the single month and is up more than 34 percent over the past year. Official data attribute more than half of the entire monthly rise in the all-items index to that one category. Energy overall is higher by roughly 20 percent.
Meanwhile the parts of the index that should light up first if strong demand were the driver remain quiet. Core goods rose only 0.7 percent over twelve months. Shelter edged higher to 3.2 percent. Services excluding energy reached 3.1 percent. One month of small upward ticks is not a trend. Core goods sitting flat is the more important signal. That is where a genuine demand boom usually announces itself earliest, and it has not done so.
A 4 percent headline that is mostly gasoline is simply not the same animal as a 4 percent headline driven by wages, rents, and broad services strength.
I have been making this same observation for several months. The composition has not changed in any meaningful way. What has changed is the accumulating evidence that incomes are not keeping pace.
Labor Markets Are Sending The Clearest Warning Signal
If this were good inflation, workers would be capturing a rising share of the gains. They are not. Real average hourly earnings declined 0.7 percent over the twelve months through September. That is more than double the decline recorded the previous month. Nominal wages rose only 0.1 percent in the latest month while consumer prices jumped 0.6 percent. Purchasing power moved backward at the fastest pace of the year.
Even more striking is the longer-running trend in labor’s share of nonfarm business output. In the second quarter that share fell to 52.8 percent. That is the lowest reading in a series that begins in 1947. Think about that for a moment. Nearly eighty years of data, multiple recessions, wars, technological revolutions, and trade shocks, and we just set a new low. The decline has been underway for roughly a quarter century. The past couple of years simply accelerated it.
A rising price level at the same time labor’s slice of the pie hits an all-time low is the classic signature of cost pass-through rather than demand-pull. Companies are protecting margins. Workers are absorbing the difference. That is not the environment in which inflation becomes self-reinforcing.
Survey data from purchasing managers tell a consistent story. The services index remains in expansion territory, yet the prices-paid component is running hot while the employment component struggles to stay above the neutral line. Respondents repeatedly cite fuel costs as the main driver of input inflation. Steady orders, elevated costs, flat hiring. That combination rarely ends with wages chasing prices higher.
Where The Persistent Inflation Case Still Has Merit
Intellectual honesty requires acknowledging the stronger counter-arguments. The artificial-intelligence investment boom has created genuine scarcity in certain memory chips and related components. Producer prices for storage devices have climbed sharply. Import prices for computers and parts have done the same. Research estimates put the contribution to core inflation in a range of two-tenths to four-tenths of a percentage point. That pressure is real and it is capital-spending driven rather than embargo driven. Still, high prices eventually ration demand. Memory shortages reverse when capacity expands or when customers redesign systems to use less of the scarce input.
Tariffs represent another lasting influence. A tax that remains in place for years produces a higher price level for years. Calling such a change purely temporary stretches the language. At the same time, the current tariff regime rests largely on executive action. Future administrations can reverse much of it relatively quickly. Permanence is not guaranteed.
Energy markets themselves are not perfectly mean-reverting on any fixed schedule. Geopolitics does not run on a calendar convenient for investors. Yet history shows that every major energy spike since the early 1970s has eventually reversed, often within one to two years. The 2008 episode saw a more than 24 percent surge followed by a 25 percent collapse. The 2022 episode produced a 41 percent surge followed by a roughly 17 percent decline the next year. The pattern repeats because demand destruction is arithmetic, not theory. When households and businesses cannot afford the higher price, they consume less. Lower consumption eventually brings the price back down.
All three of the strongest counter-arguments describe supply constraints. None of them generates the additional income required to pay the higher prices. They therefore fail the same basic test that gasoline fails.
How Bad Inflation Historically Resolves Itself
The household budget does not care about academic labels. Pain at the grocery store or the gas pump feels the same whether the underlying cause is demand or supply. The taxonomy matters for how the episode ends, not for how it feels while it is underway. Bad inflation ends through demand destruction. Good inflation does not.
Look at the historical record of energy spikes. After each sharp rise, a meaningful decline follows. The current reading near 20 percent sits comfortably inside the range that has always reverted. The process takes quarters rather than weeks, and it can inflict real damage along the way. Yet the direction of travel is clear once incomes stop supporting the higher price level.
Financial markets that specialize in pricing inflation expectations have remained remarkably calm. The ten-year breakeven inflation rate has held a tight range near 2.3 percent for many months even while headline CPI swung from the mid-two-percent area up to the low-four-percent area and back again. The market that gets paid to be right about future inflation has looked at an 180-basis-point swing in the headline number and barely blinked. That quiet message is easy to overlook when every television panel is debating structural inflation.
Bond yields themselves have moved higher, and some observers treat that rise as confirmation of an inflation problem. Decomposition shows most of the increase has come from real yields and term premium rather than from rising inflation expectations. Expectations have stayed pinned near 2.3 percent. The long end of the curve can reprice for many reasons. Inflation is not automatically the dominant one.
Practical Implications For Portfolio Construction
Will bad inflation resolve itself on a neat calendar date that investors can mark in advance? No. Demand destruction takes time. An energy shock can persist long enough to create genuine hardship before it fades. That timing mismatch is frustrating when clients measure performance in weeks while the underlying process unfolds over quarters. Still, the evidence currently points toward resolution without the central bank needing to engineer a sharp slowdown. That outlook supports a different portfolio posture than the one favored by those who expect inflation to remain structurally elevated for years.
Duration looks more attractive under this framework than under a persistent-inflation narrative. Real-wage data have reinforced that positioning in recent months. Commodity-linked exposures that were purchased purely as an inflation hedge may be positioned for the wrong kind of inflation. Commodities historically hedge the variety that eventually unwinds. Quality companies with pricing power tend to fare better than highly leveraged cyclical businesses that require a sustained nominal boom.
The labor-market data deserve closer attention than the headline CPI print. Labor is where the answer lives. Four indicators would force a change in this view: a clear reacceleration in core services excluding shelter, an upturn in the Employment Cost Index, real hourly earnings moving back above zero, and a rising quits rate. Those four together would signal that the wage-price loop is closing. Until they appear, the weight of evidence continues to favor the self-correcting interpretation.
Perhaps the most interesting aspect is how quietly the adjustment can occur. Markets often price the narrative rather than the mechanism. When the consensus becomes nearly unanimous that inflation is structural and that yields can only move higher, the setup frequently points in the opposite direction. That does not guarantee an immediate reversal. It does suggest that the risk-reward for the persistent-inflation trade has deteriorated.
Why The Distinction Matters More Than The Headline Number
Inflation is never pleasant for households living on fixed or slowly rising incomes. The distinction between good and bad versions is not an attempt to minimize that pain. It is an attempt to understand the path ahead. Good inflation tends to be accompanied by rising real wages and a rising labor share of income. Bad inflation is accompanied by the opposite. The current data set sits firmly in the second camp.
Energy prices will not fall in a straight line. Geopolitical events can produce new spikes at any moment. Tariffs can remain in place longer than expected. Technology shortages can last longer than supply chains initially forecast. None of those possibilities changes the fundamental arithmetic. When prices rise faster than incomes for an extended period, demand eventually contracts. That contraction is the cure.
I find it useful to keep the toll-road image in mind. The drivers without raises do not stage a protest. They simply drive less. Traffic falls. The operator adjusts. The same quiet adjustment is already visible in parts of the consumer economy. Discretionary categories that compete with energy and necessities for household budgets have begun to show softer volumes. That softness is not yet dramatic enough to dominate the headlines. It is the early stage of the self-correction process.
Investors who focus exclusively on the latest monthly CPI print risk missing the larger story. The composition of the print, the behavior of real wages, the path of labor’s share of output, and the message from inflation-linked markets all point in the same direction. Bad inflation is doing what it has always done. It is curing itself, slowly and unevenly, through the only mechanism that ultimately works: reduced demand.
Looking Ahead Without The Drama
The coming months will bring more data and almost certainly more commentary claiming that this time is different. Some of that commentary will prove correct on specific details. Memory prices may stay elevated longer than expected. Certain service categories may prove stickier than the broader core measure. Geopolitical risk can reassert itself without warning. None of those possibilities overturns the central observation that incomes are not financing the current price level.
Portfolio construction under this view remains relatively straightforward. Maintain exposure to quality assets that can protect margins even in a softer demand environment. Favor duration over pure inflation hedges that only work if the inflation is the durable kind. Watch the labor data more closely than the headline inflation number. Be prepared to change the view if real wages turn positive and the wage-price loop begins to close. Until then, the evidence continues to support the older and simpler conclusion: high prices eventually cure high prices when those prices are not supported by rising incomes.
That conclusion is not glamorous. It does not generate the same media attention as forecasts of structural inflation or currency debasement. It does have the advantage of matching the historical record and the current data. In markets, that combination has usually been enough.
The next time someone points to a single inflation print and declares the start of a new era, it is worth asking a quieter question. Who is paying for those higher prices, and with what income? The answer still determines whether the inflation we are experiencing is the kind that lasts or the kind that eventually burns itself out.



