
I’ve lost count of how many times someone has asked me, almost casually, “What does the Bank of England actually do?” Most people know it sets interest rates. A few remember the gold. Almost nobody realises how deeply its decisions reach into weekly shopping bills, mortgage payments, and even the value of the notes in their wallet. The truth is more layered, and frankly more interesting, than the headlines usually suggest.
The Quiet Powerhouse On Threadneedle Street
The Bank of England sits in the middle of the City of London like a stone fortress that has watched centuries of financial storms. Founded in 1694, it began life as a private company created to raise money for a government that needed cash for war. Over time it evolved into the model that almost every modern central bank still follows. That transformation did not happen overnight. It took crises, political battles, and a fair amount of quiet determination.
What started as a commercial bank with a special relationship to the Crown gradually took on responsibilities that no ordinary bank could handle. It became the banker to the government, the guardian of the currency, and later the institution charged with keeping prices stable. In my view, that slow shift from private lender to public institution is one of the more under-appreciated stories in financial history.
How It All Began In 1694
Picture London at the end of the seventeenth century. The country needed funds to fight France. Ordinary taxation was not enough. A group of merchants and financiers stepped forward with a simple idea: create a bank that would lend money to the government in exchange for a permanent interest stream and certain privileges. That deal became the Bank of England.
The original capital came from private subscribers. In return they received notes that circulated as money and a monopoly on joint-stock banking in England. The arrangement worked. The government got its war chest. The subscribers got a reliable income. And Britain gained an institution that would outlast monarchs and empires.
I’ve always found the pragmatism of that founding moment striking. There was no grand philosophical statement about central banking. Just a practical solution to a cash shortage that, almost by accident, created one of the world’s most enduring financial bodies.
From Private Company To Public Institution
For more than two centuries the Bank remained privately owned. Shareholders received dividends. Directors were elected by those shareholders. Yet the Bank’s public role kept expanding. It managed the national debt. It issued banknotes. It acted as lender of last resort when other banks got into trouble.
The big change came in 1946. The post-war government nationalised the Bank. Ownership passed to the state, though day-to-day operations stayed largely independent. That independence was strengthened further in 1997 when the Bank gained full control over interest-rate decisions. The government still sets the inflation target. The Bank decides how to hit it.
That separation of powers still shapes every rate announcement you hear on the news. It is one reason markets watch the Monetary Policy Committee so closely. When those nine people speak, mortgages, savings rates, and the pound all move.
What The Bank Actually Does Day To Day
Most of us only notice the Bank when interest rates change. Behind the scenes the work is constant and far broader. The Bank issues banknotes, manages the UK’s foreign-exchange reserves, oversees payment systems, and regulates major financial firms through its Prudential Regulation Authority.
One of its quieter but vital jobs is maintaining financial stability. When markets freeze, the Bank can step in with emergency liquidity. That role became very visible during the 2008 crisis and again in more recent market stresses. Without a credible lender of last resort, ordinary banking would be far riskier for everyone.
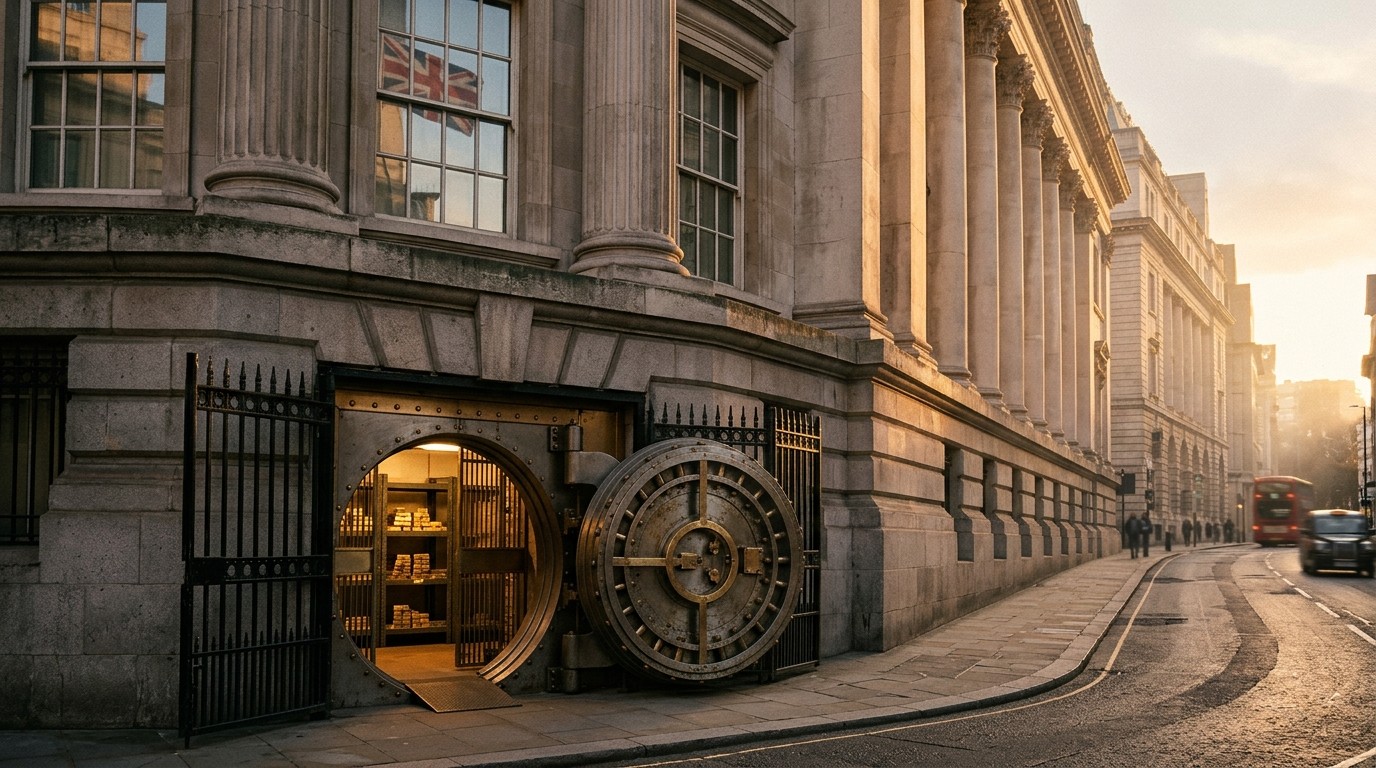
Then there is the famous gold. Deep under the Bank’s headquarters sit vaults holding hundreds of tonnes of the metal, much of it belonging to other countries as well as the UK. The exact figure fluctuates, but the visual is always striking: rows of gold bars stacked in carefully controlled conditions. It is both a practical reserve and a powerful symbol of continuity.
Central banks do not simply react to the economy. Over time they help shape the environment in which households and businesses make decisions.
Interest Rates And The Everyday Impact
When the Bank raises or cuts its base rate, the effects ripple outward quickly. Mortgage borrowers on tracker deals feel it within weeks. Savers see changes in their accounts. Businesses reassess borrowing plans. The transmission is never perfect or instantaneous, but it is real.
I’ve spoken to people who only started paying attention to the Bank after their monthly mortgage payment jumped by hundreds of pounds. That personal jolt often sparks wider curiosity. Suddenly the abstract language of monetary policy becomes concrete. It is no longer “the economy.” It is the difference between eating out and staying in.
The Bank’s current framework aims for 2 percent inflation measured by the Consumer Prices Index. Missing that target for long periods brings political pressure and public frustration. Hitting it too aggressively can slow growth and raise unemployment. Balancing those risks is the permanent tightrope walk of any modern central bank.
The Monetary Policy Committee In Practice
Nine people sit on the Monetary Policy Committee. Four are internal Bank executives. Five are external members appointed for their expertise. They meet regularly, review the latest data, and vote on the Bank Rate. Minutes of those meetings are published, offering a rare window into the debates.
Those minutes are worth reading if you want to understand the thinking behind the numbers. You see disagreements, changing views, and careful weighing of risks. The process is deliberate. Markets sometimes complain it is too slow. Others appreciate the caution. Either way, the transparency is relatively high by historical standards.
In my experience, the most useful insights often come from the accompanying Inflation Report (now the Monetary Policy Report). The charts and scenarios reveal how the Bank itself sees the path ahead. They are not predictions set in stone, but they give a clear sense of the assumptions guiding policy.
Gold, Notes, And Physical Money
Even in a digital age the Bank still prints and issues physical banknotes. The designs change over time, incorporating new security features and public figures. Polymer notes have largely replaced paper, lasting longer and proving harder to counterfeit.
Behind the notes sits the gold. The Bank acts as custodian for a significant portion of the world’s official gold reserves. Tours of the vaults (when available) leave lasting impressions. The sheer weight and quiet presence of the metal remind visitors that some old forms of value still matter.
There are also the high-value notes that most of us never see. The Bank produces special high-denomination notes used only between commercial banks for large settlements. They are practical tools rather than circulating currency, yet they form part of the same system that keeps everyday payments flowing smoothly.
Crises That Tested The Institution
No institution survives more than three centuries without facing severe tests. The Bank has navigated wars, banking panics, currency crises, and the near-collapse of the global financial system in 2008. Each episode forced adaptation.
During the early nineteenth century the Bank suspended gold convertibility for long periods. In the twentieth century it managed exchange controls and the transition away from the gold standard. More recently it pioneered large-scale asset purchases when interest rates hit the lower bound.
These episodes reveal a consistent pattern. The Bank tends to move carefully at first, then expand its toolkit when conventional measures prove insufficient. That pragmatism has preserved confidence even when outcomes were imperfect.
Independence And Accountability
Operational independence is one of the Bank’s most valuable assets. Governments of different colours have largely respected the arrangement because it helps keep inflation expectations anchored. At the same time, the Bank remains accountable to Parliament. Governors appear before select committees. Reports are scrutinised. Public letters explain any sustained deviation from the inflation target.
That balance is delicate. Too much political interference risks short-term thinking. Too little accountability can breed complacency. So far the framework has held, though every major economic shock reopens the debate.
I find the accountability mechanisms particularly interesting because they force clarity. When the Bank has to explain itself in plain language to elected representatives, the technical fog often lifts. Ordinary citizens benefit from that pressure, even if they never read the transcripts.
How Decisions Reach Your Wallet
Consider a typical rate rise. Commercial banks adjust the rates they charge borrowers and pay savers. Mortgage payments climb for those on variable deals. Credit-card interest becomes more expensive. Businesses may delay investment. Over time demand cools, which is precisely the point if inflation is running hot.
The reverse happens when rates fall. Borrowing becomes cheaper. Asset prices often rise. Consumers feel richer and spend more. The challenge is timing. Move too late and inflation embeds itself. Move too early and recovery can stall.
Exchange rates form another channel. Higher rates tend to support the pound, making imports cheaper and helping inflation. Lower rates can weaken the currency, raising the cost of foreign goods. Neither outcome is automatic, but the links are real and closely watched.
- Mortgage and loan costs respond first
- Savings rates follow more slowly
- Business investment decisions shift over quarters
- Exchange-rate effects influence import prices
- Asset markets often react within hours
The Bank’s Broader Stability Role
Interest rates grab headlines, yet financial stability work occupies a large share of the Bank’s energy. Stress tests of major banks, oversight of clearing systems, and monitoring of shadow-banking risks all fall under its umbrella. The goal is simple: prevent problems in one part of the system from cascading into the wider economy.
After 2008 the regulatory architecture was redesigned. The Bank gained new powers and a clearer mandate to act early. That shift remains controversial in some quarters. Critics worry about over-reach. Supporters point to the absence of another full-scale banking collapse on the same scale.
Whatever one’s view, the expanded role reflects a hard-learned lesson. Price stability alone is not enough if the financial system underneath is fragile.
Looking At The Longer Arc
Standing back, the Bank of England’s story is one of gradual institutional evolution. It began as a wartime funding vehicle. It became the guardian of the currency. It absorbed responsibility for systemic stability. Each expansion of mandate responded to practical problems rather than abstract theory.
That evolutionary path helps explain its resilience. Institutions designed on pure ideology often struggle when reality intervenes. Institutions that adapt while preserving core credibility tend to endure. The Bank has managed that balance better than most.
Of course challenges remain. Climate risks, digital currencies, geopolitical tensions, and the long-term effects of large balance-sheet interventions all pose new questions. The answers will shape the next chapter.
Common Misconceptions Worth Clearing Up
One frequent misunderstanding is that the Bank “prints money” in the ordinary sense whenever it wants. In reality the process of creating reserves is carefully controlled and aimed at specific policy goals. Another is the idea that the Bank can fine-tune the economy with surgical precision. The tools are blunt. Lags are long. Uncertainty is constant.
A third misconception concerns gold. The metal still matters as a reserve asset and confidence signal, yet modern monetary systems rest primarily on credibility and policy frameworks rather than fixed convertibility. Understanding that distinction helps cut through a lot of online noise.
Finally, the Bank is not the government. It operates at arm’s length. That distance is intentional and, on balance, valuable. Blurring the lines would risk turning monetary policy into a short-term political tool, with predictable long-term costs.
Why Ordinary People Should Care
It is easy to treat the Bank as distant and technical. Yet its decisions influence the cost of homes, the real value of wages, the returns on savings, and the stability of the banking system that holds most people’s money. Ignoring it is a bit like ignoring the weather forecast before a long journey.
Paying modest attention yields practical benefits. Understanding the direction of rates helps with mortgage timing. Watching inflation data gives context for wage negotiations. Knowing the Bank’s stability role reduces unnecessary panic during market turbulence.
In short, the Bank of England is not just an institution for specialists. It is a central part of the financial environment every household navigates. The more clearly we see its role, the better equipped we are to make our own decisions.
A Few Practical Takeaways
First, follow the Monetary Policy Report summaries rather than isolated headlines. They provide context that single rate decisions lack. Second, remember that the Bank reacts to data. Unexpected inflation or growth numbers can shift the path quickly. Third, financial stability work happens mostly out of public view until something goes wrong. Its quiet success is easy to take for granted.
Perhaps the most useful habit is simply curiosity. When rates move or inflation surprises, ask what the Bank is trying to achieve and why. That small mental step turns abstract announcements into understandable policy choices.
The Bank of England has been part of British economic life for more than three hundred years. Its methods have changed. Its core purpose—protecting the value of money and the stability of the system—remains remarkably constant. Understanding that continuity, and the practical ways it touches daily life, is worth the modest effort required.
The next time you hear a rate decision or see a new banknote design, you might find yourself looking a little deeper. The institution on Threadneedle Street still shapes more of our financial world than most of us realise. And that, in the end, is why its story continues to matter.