
When the numbers first started circulating about the scale of the Binance breach, I honestly expected the DeFi lending markets to seize up. A loss measured in the billions is the kind of event that usually sends everyone racing for the exits. Yet the actual reaction turned out quieter and shorter-lived than almost anyone predicted. The contrast with a much smaller exploit earlier in the year makes the difference even more striking.
Why the Binance Breach Triggered a Smaller DeFi Run
According to detailed market tracking, lending protocols saw roughly $1.59 billion in net outflows during the first full day after the breach became public. That figure represented only about three percent of total lending value locked at the time. More importantly, around sixty percent of those funds returned within three days. Analysts found no evidence of bad debt across the pools they monitored. That combination of limited scale and rapid reversal stands in sharp contrast to what happened after the Kelp incident months earlier.
In the Kelp case a theft of $292 million prompted $10.9 billion to leave lending markets over five days. That amounted to roughly twenty-one percent of lending total value locked. None of those funds returned during the observation window. The withdrawal wave was roughly thirty-seven times larger than the amount actually stolen. The difference in market behavior is not random. It traces directly to where the damaged assets sat and how participants assessed their own exposure.
Location of the Loss Matters More Than the Size
In the Binance event the stolen assets remained largely inside the exchange’s own systems. They were not circulating as collateral across dozens of lending pools. Depositors could look at their positions and conclude that the breach had not directly impaired the tokens they had supplied. The uncertainty stayed contained. With Kelp the compromised asset itself functioned as collateral in multiple markets. Suddenly every depositor had to wonder whether their pool held exposure and whether liquidations would cascade. That uncertainty produced a far larger and more sustained withdrawal wave even though the initial theft was less than five percent the size of the Binance loss.
I have watched enough market stress events to know that fear of unknown contagion usually outweighs the raw size of any single loss. When people cannot map the damage, they simply leave. When they can map it and see that their own positions sit outside the blast radius, many stay put or return quickly once the initial shock fades. That pattern played out almost textbook fashion this time.
Stablecoin Issuers Moved Faster Than Ever Before
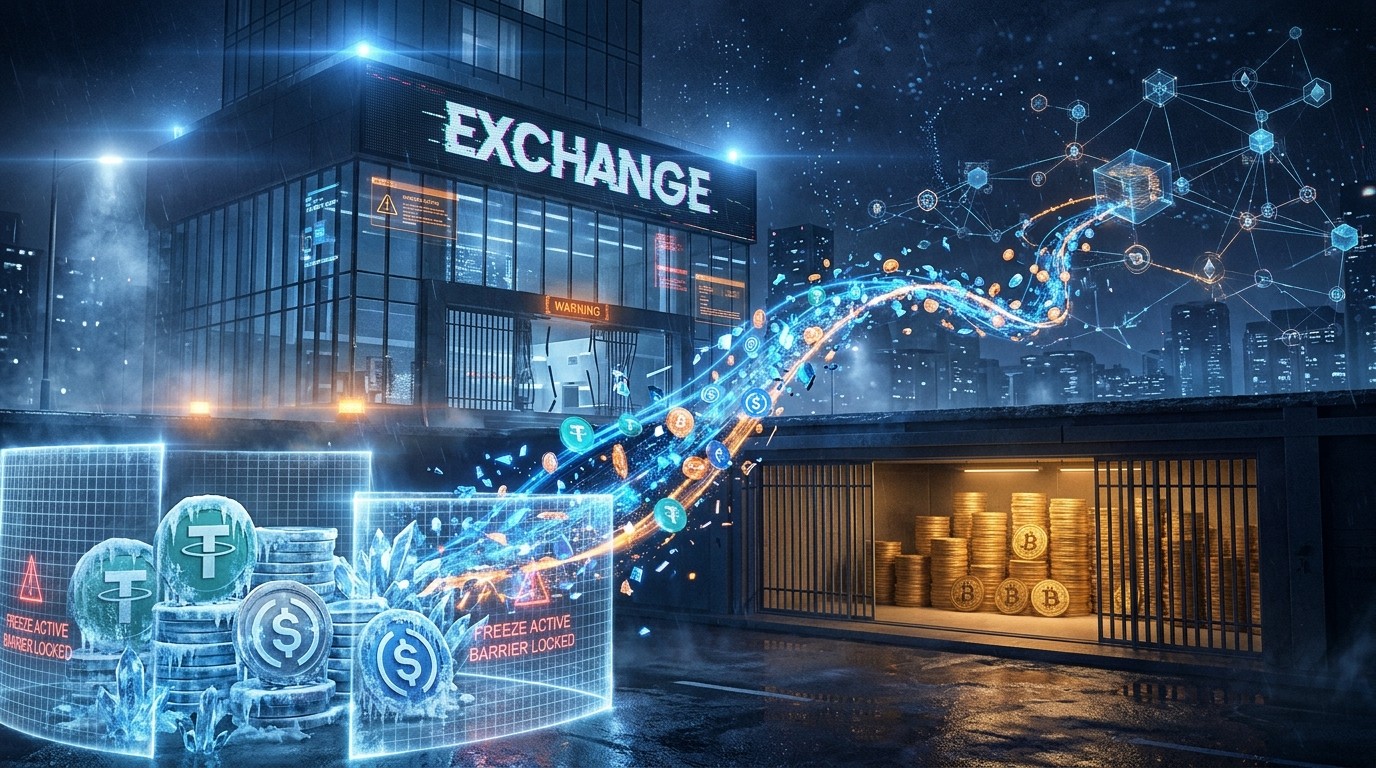
One of the clearest differences in the response came from the major stablecoin issuers. In what observers have called the largest coordinated on-chain asset freeze in DeFi history, Circle blocked 823 million USDC sitting in a single wallet before the attacker could move the funds further. Separate interventions immobilized roughly $40 million in RLUSD and another $27 million in USD1 along with 48 million related tokens. Those freezes removed a substantial portion of the liquid, transferable value from the attacker’s immediate control.
Native Bitcoin and Ethereum, of course, have no issuer that can impose the same kind of blacklist. Tracking data later showed the attacker still held approximately 18,270 BTC and more than 420,000 ETH after the freezes took effect. The ability of stablecoin issuers to act so quickly changed the risk calculation for many market participants. It signaled that at least part of the stolen value would not flood into secondary markets or be used as fresh collateral. That reassurance likely contributed to the relatively contained reaction in lending pools.
When issuers can freeze large blocks of value in real time, the market’s worst-case scenarios shrink overnight. That single capability may have prevented a much deeper and longer withdrawal cycle.
Conversion Activity and the Remaining Holdings
Blockchain intelligence updates continued to track the attacker’s efforts to convert other stolen assets into Bitcoin. By one recent count the amount converted had reached approximately 1,650 BTC, valued at about $124 million. Much of the overnight increase came from XRP routed through a cross-chain liquidity protocol. Around 42 million XRP worth roughly $50 million had already left the holding addresses, while another 192 million XRP valued near $226 million remained. The original 18,270 BTC stayed untouched across nineteen separate addresses.
The scale of the laundering effort itself is notable. Investigators identified more than 20,000 wallets and at least 65,000 transactions spanning sixteen blockchains. Roughly $3.11 billion still sat in addresses linked to the theft, with very little evidence of successful cash-out to traditional financial rails. One privacy-focused service temporarily paused deposits after detecting linked inflows, then resumed the following day without further suspicious activity. These details paint a picture of an attacker still largely boxed in by freezes, monitoring, and the inherent difficulty of moving such large sums without leaving a trail.
Recovery Steps Taken by the Exchange
On the recovery side the exchange moved with unusual speed. Within days it reported that approximately ninety-eight percent of affected user assets had already been replaced using internal resources. The remaining two percent consisted of less liquid tokens still being acquired through market purchases and over-the-counter channels. The company stated it had set aside more than one hundred percent of the funds needed to cover the full loss. That proactive stance almost certainly reduced the incentive for depositors in external lending markets to treat the event as a systemic solvency threat.
Separately, the exchange submitted a formal request to a major layer-two network’s decentralized autonomous organization seeking the return of roughly 8,426 ETH and 74.56 million of the network’s native token. The proposal outlined a discussion and voting timeline of about forty-nine days, with the possibility of longer delays if legal claims arise. It also included indemnification language governed by New York law and assigned disputes to courts in New York County. No new treasury allocation from the DAO was requested. The process illustrates how recovery in a decentralized environment often depends on governance procedures that move far more slowly than the original theft.
How Investigators Characterized the Attack
Public statements from the exchange traced the intrusion to a combination of fake recruitment interviews, malicious software, and compromise of an internal artificial-intelligence tool. Attackers ultimately reached the signing service through employee systems that had been compromised. On the law-enforcement side, federal investigators attributed the theft to a North Korean activity cluster known for targeting cryptocurrency services. They published specific addresses and urged platforms to block related transactions. The combination of technical detail and attribution added another layer of clarity that was missing in some earlier incidents. Markets tend to stabilize faster when the nature of the threat becomes less mysterious.
Lessons About Collateral Concentration and Contagion Risk
Perhaps the most useful takeaway sits in the comparison itself. When a compromised asset is widely used as collateral, even a relatively modest theft can trigger outsized withdrawals because depositors cannot easily determine their indirect exposure. When the loss stays inside a single centralized platform, the same size loss produces a far smaller ripple. That distinction should influence how protocols design collateral lists and how risk teams model contagion. Concentration risk is not only about the total value of any single asset; it is also about how many independent markets treat that asset as high-quality collateral.
In my view the rapid return of most of the $1.59 billion is more significant than the initial outflow. It suggests that once participants could verify that their positions were not directly impaired, confidence returned quickly. The absence of bad debt across monitored markets reinforces the same point. Lending protocols that maintain transparent collateral compositions and conservative loan-to-value ratios appear better positioned to weather external shocks that do not originate inside their own smart contracts.
What the Freezes Reveal About Stablecoin Power
The scale of the freezes also raises longer-term questions about the nature of so-called decentralized finance. When issuers can immobilize hundreds of millions of dollars with a few administrative actions, the system retains a powerful centralized backstop. Many participants welcome that capability in moments of crisis. Others worry that the same power could be used under different circumstances. Both perspectives are understandable. What matters for market structure is that the capability exists and that it was used decisively this time. The net effect on lending markets appears to have been stabilizing.
At the same time, the inability to freeze native Bitcoin and Ethereum highlights a persistent asymmetry. The most liquid and widely held assets remain the hardest to restrict after a theft. Attackers know this. Defenders know this. The market’s relative calm despite large holdings of those two assets suggests that participants currently place more weight on the frozen stablecoin portion and on the exchange’s rapid capital replacement than on the still-unfrozen major cryptocurrencies.
Comparing Observation Windows and Measurement Choices
Any comparison between the two events must note the different observation windows. The Binance outflow figure covers a single day, while the Kelp figure covers five days. The choice is understandable because the bulk of the Binance reaction happened quickly and then reversed. Still, the disparity in windows means the percentages are not perfectly parallel. Even so, the gap is large enough that the qualitative conclusion remains robust. One event produced a sharp but temporary three-percent outflow. The other produced a sustained twenty-one-percent outflow with no rebound in the measured period.
Some observers will inevitably argue that the market has simply become more resilient or that participants have grown desensitized to large losses. There may be some truth to both ideas. Yet the cleanest explanation remains the difference in collateral exposure. When people can see that the damaged asset is not sitting underneath their own deposits, they behave differently. That is less about desensitization and more about information.
Implications for Future Risk Management
Looking ahead, protocols that accept a wide range of collateral will need clearer ways to communicate exposure after an external breach. Real-time dashboards that show the percentage of each pool’s collateral linked to any single issuer or bridge could reduce the kind of uncertainty that drove the Kelp withdrawals. Similarly, exchanges that suffer breaches will find that transparent and rapid capital replacement has measurable effects on external markets. The ninety-eight percent replacement figure was not merely a customer-service achievement; it was a market-stability measure.
I also expect greater attention to the governance processes required for recovering assets on decentralized networks. The roughly seven-week timeline proposed for one major network is not unusual, but it underscores how recovery can lag far behind the speed of the original theft. Markets may begin to price that lag into their assessment of residual risk after future incidents.
The Broader Context of Large-Scale Crypto Thefts
Large exchange breaches are not new, yet each one arrives with its own combination of technical vectors, asset composition, and market conditions. What stands out in this case is how little secondary damage appeared in the lending layer despite the headline size of the loss. That outcome was not automatic. It resulted from a specific set of circumstances: the loss remaining inside the exchange, rapid issuer freezes, swift capital replacement, and relatively clear attribution. Remove any one of those factors and the $1.59 billion outflow might have been larger and longer-lasting.
The comparison with the earlier smaller exploit therefore serves as a useful stress test of market psychology. Size alone does not determine the scale of the reaction. Location of the damaged assets, speed of containment, and the presence or absence of collateral linkages matter more. Participants who understand those distinctions will be better equipped to interpret the next incident when it arrives, as it almost certainly will.
Practical Takeaways for Depositors and Protocol Teams
For individual depositors the episode offers a reminder to examine collateral composition before supplying liquidity. Pools that rely heavily on any single external asset carry a form of contagion risk that only becomes visible after that asset is compromised. Diversification across collateral types and across protocols remains one of the few practical defenses available to users who cannot audit every smart contract in real time.
For protocol teams the data suggest that transparency about collateral sources can itself function as a stability tool. When depositors can quickly verify that their pool has little or no exposure to a compromised asset, the incentive to withdraw declines sharply. Some protocols already publish detailed breakdowns; wider adoption of that practice could reduce the amplitude of future withdrawal waves.
- Monitor the percentage of any single external asset used as collateral across major lending markets
- Track issuer freeze capabilities and historical response times for the stablecoins you hold or accept
- Assess how quickly a platform has replaced customer assets after previous incidents
- Watch governance timelines for recovery of assets held on decentralized networks
- Distinguish between losses that remain inside a centralized platform and losses that impair widely used collateral
Those five points are not exhaustive, yet they capture the variables that most clearly separated the two recent episodes. Markets that internalize the distinction will likely experience milder secondary effects the next time a large centralized platform is breached.
Final Thoughts on Market Resilience
It is tempting to declare that DeFi lending has become more mature simply because the larger breach produced the smaller reaction. Maturity is part of the story, but structure is the larger part. The market behaved differently because the damage was located differently and because containment tools worked faster. Recognizing that distinction is more useful than celebrating resilience in the abstract.
The $1.59 billion that left lending markets and the sixty percent that returned within three days together form one of the cleaner natural experiments the sector has seen in recent years. They show that participants can differentiate between a platform-level loss and a collateral-level loss when the information is available. They also show that coordinated freezes and rapid capital replacement still matter enormously. Those are practical observations rather than optimistic slogans, and they are worth carrying forward.
As tracking of the remaining holdings continues and as the governance processes for recovery play out, the full cost of the breach will become clearer. For now the most important signal is the one already visible in the lending data: a multi-billion-dollar exchange loss does not automatically translate into a multi-billion-dollar DeFi crisis when the damaged assets sit outside the collateral layer and when issuers and the affected platform move quickly. That is a narrower form of progress than some will claim, yet it is real progress all the same.
In the end the episode leaves the sector with a clearer map of its own vulnerabilities. Collateral linkages amplify shocks. Freezes and capital replacement dampen them. Transparent information shortens the duration of fear. Those three forces interacted this time in a way that limited secondary damage. Understanding how they interact will help the next time the numbers are large and the initial reaction is uncertain. And there will be a next time. The only question is whether the market will again be able to tell the difference between a platform breach and a systemic collateral event. On the evidence of the past week, at least some participants already can.