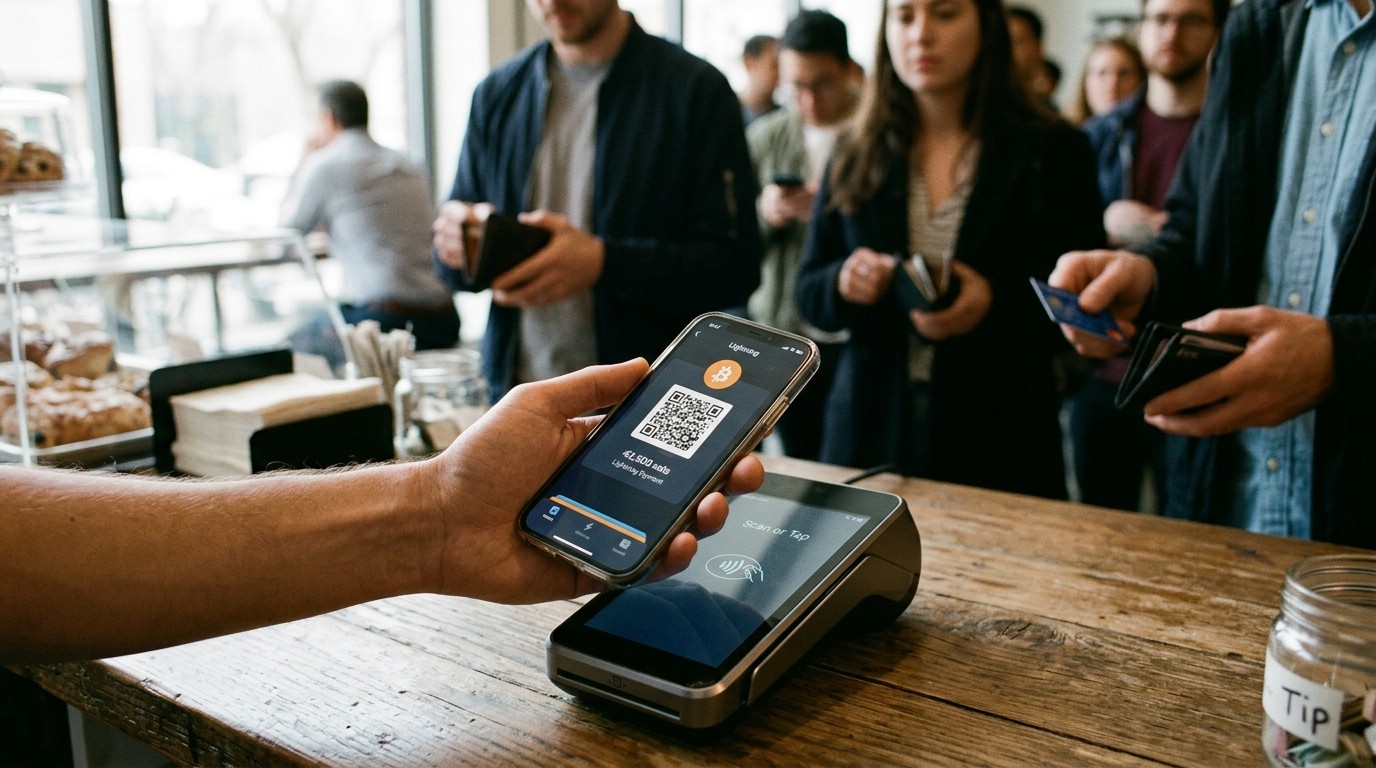

Walk into a coffee shop that proudly displays a Bitcoin option at the register and you might expect to see a steady stream of orange-logo payments. Instead you mostly hear the familiar tap of cards and the quiet approval beep of digital wallets already tied to bank accounts. That quiet mismatch sits at the center of a much bigger story. Bitcoin can now reach more than a million U.S. merchants through a major payments platform, yet the same developers who spent years making Lightning easier admit that everyday spending remains stubbornly scarce.
The Gap Between Reach and Real Use
Availability is not the same as activity. A seller can turn on Bitcoin acceptance, convert every incoming payment into dollars by default, and still finish the day without a single satoshi changing hands. The customer who holds Bitcoin as a long-term position often sees little reason to spend it on lunch when a regular card already draws from the same account used for rent and groceries. The tools improved. The incentive to open the wallet did not.
I keep coming back to that distinction because the industry has spent years treating merchant counts as proof of progress. A million enabled terminals sounds impressive until you realize the number tells you almost nothing about completed sales, repeat buyers, or the share of total checkout volume that actually moves in Bitcoin. Without those denominators the figure remains a distribution statistic, not an adoption one.
What a Million Merchants Really Means
The rollout made Lightning payments available to roughly one million U.S. sellers. Eligible merchants can accept a Bitcoin payment and receive dollars automatically. Conversion happens inside the payment flow so the seller never has to manage volatility or set up separate software. Anyone who prefers to stay with cards alone can simply opt out. That arrangement removes a genuine barrier. A small restaurant no longer needs to source hardware, watch exchange rates, or decide how to handle a volatile receipt.
Yet the same convenience creates ambiguity. Being enabled is not the same as having a visible Bitcoin button, trained staff, or customers who actually choose the option. One million merchants each processing zero Bitcoin sales would still register as one million enabled merchants. At the other extreme, a few hundred highly active shops could account for nearly all the volume. Public data that separates those two realities has not appeared. Until it does, the headline number mainly measures how widely the option was distributed rather than how often it is used.
From the merchant side the product decision makes sense. Adding the option costs relatively little once the infrastructure exists. Keeping the seller in dollars solves the accounting problem for a business whose rent and wages are denominated in fiat. What it does not do is create a Bitcoin economy between customers and suppliers. The useful metric remains the fraction of checkouts actually funded with Bitcoin, not the number of locations capable of displaying the button.
Why Holders Still Reach for Dollars
Bitcoin’s strongest story works against its weakest one. Someone who expects the asset to rise over years has a natural reluctance to spend it on everyday purchases. Replenishing after a sale requires another buy, possible exchange spreads, and extra record-keeping. A simple card tap never forces the buyer to think about the future value of the money just spent on coffee.
Volatility adds another layer. Even when the merchant receives dollars by default, the customer still sees a dollar price converted into a Bitcoin amount at the moment of payment. That rate may have moved since the coins were acquired. Stablecoins avoid this particular friction by keeping the unit of account consistent from start to finish, though they introduce their own set of issuer and redemption risks.
U.S. tax treatment remains an under-discussed obstacle. Spending Bitcoin is treated as a disposition. Any gain between acquisition cost and the value at the moment of purchase can create a taxable event, even on a small transaction. The actual tax owed depends on basis, holding period, and the rest of a person’s situation, but the need to track every small disposal makes the experience feel less like ordinary spending and more like a miniature investment sale. I’ve found that this administrative friction alone is enough to push many people back to the card they already use without thinking.
Payment design cannot erase a legal difference simply by changing the checkout screen.
Fee comparisons often focus only on the merchant side. A lower network charge does not automatically translate into a lower total cost for the buyer. Acquisition costs, conversion spreads when replenishing, and the accounting burden all sit on the customer. A fair comparison would follow the same purchase from funding through settlement rather than isolating the Lightning routing fee against a card processing rate.
Lightning Made the Rails Better, Not the Demand
Lightning has matured. Channels, liquidity, and wallet interfaces have improved enough that many users never see the underlying complexity. Custodial Bitcoin can now be added to an application with effort comparable to integrating a stablecoin. Self-custodial services at scale remain harder, yet the overall developer experience has clearly advanced.
Better tooling removes reasons for a motivated customer to abandon a payment. Clearer amounts, reusable addresses, recovery options, and a single QR flow all matter. Still, technical success does not guarantee return visits. A wallet that handles the first transaction smoothly is necessary for repeat commerce but nowhere near sufficient to create it. Preferences form around what the buyer already holds and what the merchant actually wants to receive.
There is an important distinction between Bitcoin as a rail and Bitcoin as the money being spent. A wallet can convert a dollar balance and settle a Lightning invoice. The infrastructure carried value, yet the customer never chose to draw down Bitcoin savings. Both uses can be valuable. Mixing them into a single “Bitcoin payments” total hides the specific adoption problem under discussion.
The same ambiguity appears when a shop receives dollars by default. The customer spent Bitcoin; the merchant booked a conventional receipt. If the goal is making Bitcoin a common medium of exchange among households, customer-side spending is the relevant measure. If the goal is open settlement infrastructure that can carry different currencies, a dollar payment over Lightning also counts. The two outcomes need separate tracking.
Stablecoins Already Sit in the Checkout Lane
Dollar-backed tokens solve the unit-of-account problem for merchants who price everything in dollars. Major commerce platforms and payment processors have added stablecoin options inside familiar software. A seller does not need to learn a new pricing language. An advertised ten-dollar item stays ten dollars from order to settlement.
That convenience comes with trade-offs. Users depend on reserves, custody arrangements, and redemption rules. Issuers can restrict access under legal or operational pressure. Bitcoin’s self-custody model retains advantages where an individual wants to move value without relying on a dollar-token issuer. The preferred choice therefore varies by location and use case.
The sequencing of integrations matters. Platforms that already handle cards and dollars can add a stablecoin with relatively little friction. A Bitcoin option can be made equally easy for a processor to support, yet the customer still has to prefer it at the point of sale. Once wallets, merchant reports, refunds, and developer tools organize around one accepted asset, switching costs rise. There is no guarantee the first set of rails wins forever, but inertia is real.
Some stablecoin volume reflects cross-border treasury movement rather than retail shopping. Headline comparisons that treat all transfer volume as equivalent “payments” can mislead. The relevant comparison depends on the question being asked: completed merchant purchases in the same region, remittances of similar size, or payments for the same type of digital service. On-chain transfers also include exchange rebalancing and internal movements that never touch a consumer checkout.
Agent Payments and the Next Test Case
Software agents that request an API, receive a price, and pay automatically introduce a different kind of commerce. These purchases need predictable costs and machine-readable flows. Early measurements of one emerging standard showed an overwhelming share of activity moving in dollar stablecoins. A Lightning route was later added to the same standard, giving developers a Bitcoin option. Support in the protocol, however, does not equal widespread use.
Another service now lets developers give agents a Bitcoin wallet without each one running a full Lightning node and managing channels. Early limits remain modest and the product is still in an experimental phase. These developments test the rail and perhaps the currency, provided the two continue to be measured separately.
An agent can pay for data or compute without a human ever seeing the transaction. The open questions are who funds the wallet, which asset the seller prefers, and what controls prevent unbounded spending. Agent commerce could generate large numbers of small payments while human checkout behavior stays largely unchanged. That outcome would still be useful, just different from the everyday retail adoption many people originally imagined.
Incentives Can Buy Trials, Not Habits
Discounts and rewards can overcome a customer’s reluctance to try an unfamiliar payment method once. Their real value as evidence appears after the promotion ends. Does the same buyer return when a card, a stablecoin, and Bitcoin all compete on ordinary terms? Campaigns that report only first-month transaction counts risk measuring subsidy collection rather than lasting preference.
Merchant incentives work differently. Fee benefits or faster access to proceeds may encourage a seller to display the Bitcoin option more prominently and train staff to handle it. The customer still needs a compatible wallet and a reason to choose Bitcoin over the easier alternatives. Whether the combined economics work depends on the full cost of acquiring, transmitting, converting, and accounting for the payment, not the nominal routing fee alone.
Micropayments offer a more distinctive use case than simply replacing a card purchase. Paying a creator by the minute, buying a single data request, or compensating a remote computer for a tiny unit of work can feel awkward under traditional card minimums or subscription models. Bitcoin’s divisibility and Lightning’s small transfers make such experiments feasible. The service itself still has to deliver value, reliable delivery, and protection against accidental repeated charges. Infrastructure moves the money; the product has to earn the right to be paid.
How to Measure Whether the Million Merchants Matter
Start with the time period and the denominator. A monthly count of active Bitcoin-accepting sellers divided by all eligible sellers would say far more than the overall million. The same report should show how many transactions each active seller processed and the share of total checkout value those payments represented. Merchants who made one test sale need to be distinguished from those who see routine purchases.
Next follow the buyer. How many distinct customers paid twice or more within 30 or 90 days? How many continued after any discount expired? Privacy constraints may prevent publishing personally identifiable records, yet aggregate cohorts can answer the question without naming individuals. Growth in payment volume should be broken down by whether it came from one large merchant, a new seller cohort, or repeated everyday use.
Finally state the asset at each end of the transaction. A customer paying Bitcoin while the seller receives dollars is customer-side Bitcoin spending and a conventional receipt for the merchant. A dollar payment carried over Lightning is a use of Bitcoin-linked infrastructure without a necessary customer decision to spend BTC. A stablecoin transfer between exchanges is neither a merchant purchase nor proof of consumer preference at checkout. Separating the flows gives the million-merchant claim a fair test.
One simple illustration shows why the missing denominators matter. If 10,000 of a million enabled merchants took one Bitcoin payment in a month, the active share would be one percent. If 100,000 did, it would be ten percent. Both scenarios are consistent with the same headline number of enabled sellers. Publishing the actual active-seller count would replace speculation with an observed ratio. Adding repeat-buyer and value figures would show whether that ratio reflects meaningful consumer spending.
What Could Shift the Pattern Over Five Years
Tax policy remains one possible lever. Limited proposals have addressed small network fees, yet no general de minimis exemption for everyday Bitcoin purchases currently exists. Any real change would require clear legislative language, a defined threshold, and an effective date. Until then, merchants can simplify their side of the checkout while consumers still face the existing disposition rules.
Geographic differences may matter more than many realize. In places with unstable local currencies or capital controls, self-custody can feel more compelling than it does to a shopper in a stable dollar environment. Evidence would come from repeated holding and spending behavior in those specific markets, not from assuming every person under inflation has identical needs. Remittance, local merchant spending, and pure saving should be counted separately.
The strongest counter-argument remains that everyday spending is simply premature for an asset many still treat as long-term savings. Volatility could decline as markets deepen. Wallets could become simpler still. Users in certain regions might discover stronger reasons to spend. Those possibilities deserve testing with longitudinal data rather than dismissal or celebration.
The available evidence already rules out one convenient explanation. People are not failing to spend Bitcoin merely because no shops can accept it. The distribution barrier for a large set of sellers has been reduced. The remaining work involves why buyers would choose Bitcoin, whether the complete transaction feels convenient, and what a merchant does after accepting it. Clearer public data on active sellers, completed sales, repeat buyers, and the asset used at checkout would turn an interesting claim into something that can actually be evaluated. Until those figures appear, the million-merchant milestone remains a story of expanded possibility rather than proven demand.
Perhaps the most interesting aspect is how honestly the gap is now being discussed. Acknowledging weak everyday use while continuing to improve the rails is more useful than pretending the numbers already prove widespread adoption. The next five years will show whether incentives, better products, shared infrastructure, or changing local conditions finally give holders a reason to open the wallet at the register. For now the tools are ready. The spending habit is still waiting to form.