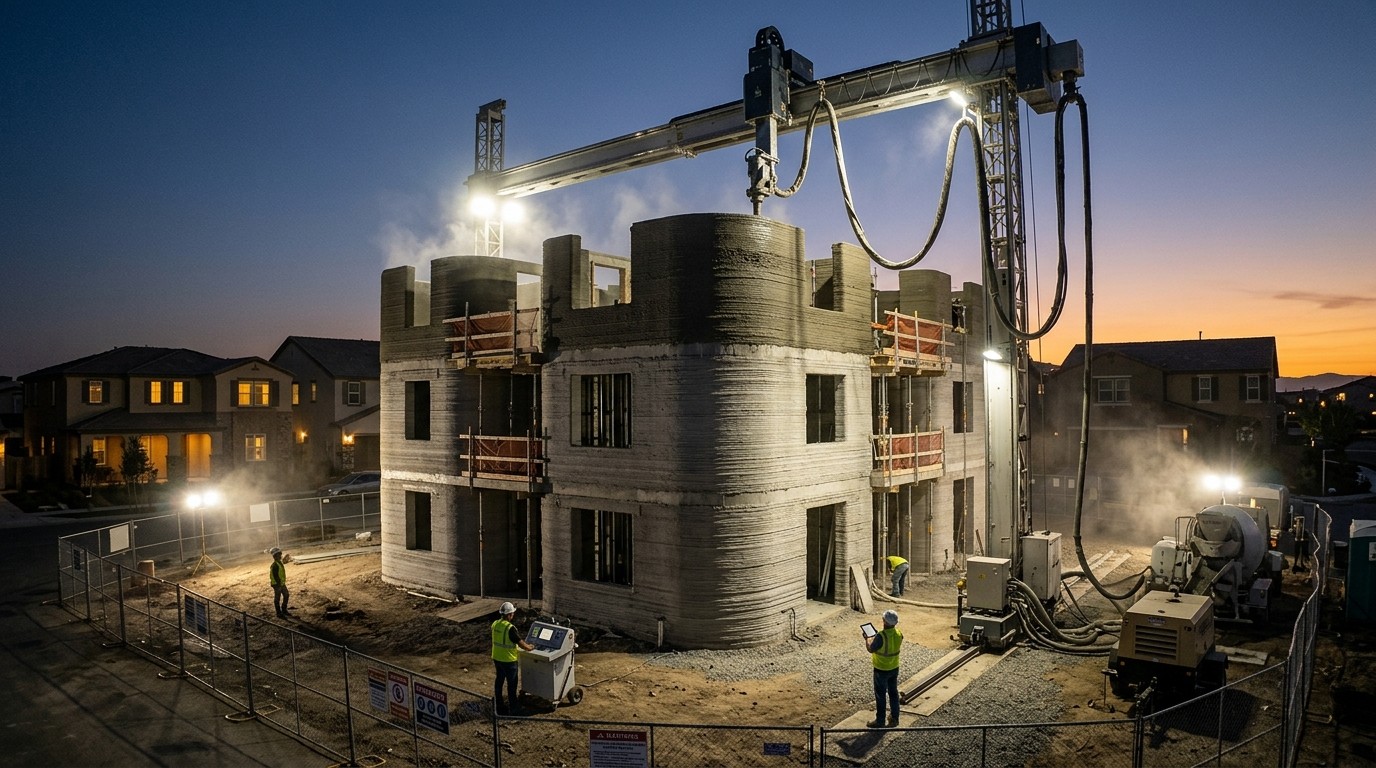

I still remember the first time I saw a concrete house rising layer by layer from a giant robotic arm. It looked more like science fiction than construction. That was several years ago, and the technology could only manage single-story structures. Fast forward to today and the same company just closed a massive funding round that signals something much bigger is underway. BlackRock and Baillie Gifford have joined forces to back Icon with two hundred million dollars, pushing the firm’s total capital raised past seven hundred million and valuing it at one point four billion dollars. The timing feels almost perfect.
Why Major Investors Are Suddenly Betting Heavy On Printed Houses
Traditional homebuilding has been under serious pressure. Higher interest rates, expensive land, scarce skilled labor, and stubborn material costs have squeezed margins and slowed delivery. At the same time the country still needs roughly four million additional homes just to catch up with demand. Into that gap steps a company that claims its newest system can cut average build time by six weeks, reduce the number of workers required on site, and lower overall costs by about forty percent. Those numbers are hard to ignore when you are sitting on large pools of patient capital.
I’ve followed construction technology long enough to know that most “disruptive” ideas never leave the pilot stage. Icon is different. It already has completed communities under its belt and is now shifting from printing homes for its own projects to selling the equipment and process to other builders. That transition is exactly what large investors look for. They want proof that the model can scale beyond the founder’s own balance sheet.
The Titan System Changes The Math Completely
Previous printers were limited to single-story structures. The new Titan multi-story robotic system, launched commercially earlier this year, removes that ceiling. It can handle the vertical complexity that real neighborhoods require. The reduction in labor and the shorter construction window are not marketing slogans. They directly attack the two biggest cost drivers in residential development right now.
Think about a typical production builder trying to deliver fifty homes in a subdivision. Every week of delay multiplies carrying costs on land and construction loans. Cutting six weeks off each house compounds into real money. Fewer workers also means less exposure to the chronic shortage of skilled trades. When you can print the structural shell faster and with fewer people, the remaining trades can move in sooner and finish the job more efficiently.
We were really looking for an investor group who had helped built-world, physical companies move from early startup proof points to scale.
That comment from the company’s chief executive captures the moment perfectly. The firm specifically sought partners experienced with hard-tech companies that had to cross the messy middle between prototype and widespread adoption. Baillie Gifford’s track record with long-horizon technology bets and BlackRock’s deep real-estate expertise form a natural combination for this stage of growth.
From In-House Projects To Selling The Machine
Until recently Icon used its printers mainly on its own developments. One well-known community outside Austin demonstrated what a fully printed neighborhood could look like. Now the strategy has flipped. The company is placing systems into the hands of other builders, both large publicly traded firms and smaller private ones. Demand has already surprised the internal forecasts. Reservations with money down are running roughly ten times higher than the volume the team thought it would need for the coming year.
Special financing arrangements help smooth the adoption curve. One major lender is offering incentives both to the builders purchasing the systems and to the homebuyers who ultimately live in the printed houses. That kind of ecosystem support matters. New technology rarely succeeds on technical merit alone. It needs capital structures that make the first few projects less risky for the early adopters.
In my view this commercial pivot is the single most important development of the past twelve months. Printing a few show homes is interesting. Selling the capability to the broader industry is how you actually change construction norms. The current funding will accelerate that transition by expanding the footprint beyond Texas, Florida, and the Washington D.C. area into additional markets across the country.
Revenue Growth And The Path Toward Public Markets
Management reports the business is on track for four times revenue growth this year. Looking at the current pipeline they expect at least to double that rate again next year. Those are aggressive numbers, yet the combination of equipment sales, project participation, and potential service contracts makes the trajectory plausible if execution stays disciplined.
Talk of a future public listing has begun to surface. An IPO is never guaranteed, of course, and market conditions can shift quickly. Still, a company that can demonstrate repeated revenue doubling while solving a structural housing problem would attract significant attention from both institutional and retail investors. The valuation already places Icon in rare company among construction-technology firms.
Beyond Earthly Neighborhoods
Perhaps the most intriguing part of the story sits far outside typical real-estate discussions. The same core technology is being adapted for military readiness projects and for NASA’s longer-term lunar ambitions. Contracts exceeding three hundred seventy million dollars support development of systems that could one day help construct infrastructure on the Moon. The company remains closely aligned with those programs and anticipates further announcements later this year.
I find the dual-use aspect fascinating. Techniques refined under the extreme constraints of space eventually find their way back into terrestrial applications. Materials that must survive harsh environments, autonomous operation with minimal human oversight, and extreme reliability all translate into more robust systems for everyday homebuilding. The cross-pollination could accelerate improvements that pure residential development might never have funded on its own.
What The Housing Shortage Actually Looks Like On The Ground
Four million missing homes is an abstract figure until you dig into the local numbers. In many metro areas the shortage shows up as bidding wars for older inventory, adult children remaining in parental homes longer than previous generations, and entire cohorts of potential buyers locked out by price. New supply has simply not kept pace with household formation for more than a decade.
Conventional builders face structural headwinds. Zoning and permitting timelines stretch measured in years rather than months in many jurisdictions. Skilled labor remains scarce even as wages rise. Material price volatility continues. Against that backdrop a method that compresses the vertical construction phase and reduces headcount dependence starts to look less like a novelty and more like a necessary adaptation.
Of course 3D printing will not solve every bottleneck. Land entitlement, utility connections, and interior finishing still require traditional processes. Yet attacking the structural shell—the part that currently absorbs the most time and weather risk—creates breathing room for the rest of the schedule. That incremental advantage compounds across a large portfolio of homes.
Cost Structure And The Forty Percent Claim
Lowering total project cost by roughly forty percent is an ambitious target. Achieving it depends on more than the printer itself. It requires redesigning floor plans for efficient layering, optimizing the concrete mix for rapid curing, and integrating the printed structure with conventional framing and finishes. Early projects have already demonstrated meaningful savings; the next challenge is proving those savings hold when the systems are operated by third-party builders rather than the technology’s inventors.
I’ve spoken with enough developers to know that skepticism remains healthy. Many have watched previous modular or panelized approaches promise dramatic savings only to encounter hidden costs or quality issues. Icon’s advantage is the growing body of completed work that can be inspected, measured, and lived in. Performance data on energy efficiency, durability, and maintenance costs will matter more than any single funding announcement.
- Shorter construction schedules reduce financing carrying costs
- Lower on-site labor requirements ease recruitment pressure
- Material efficiency from precise extrusion can cut waste
- Consistent quality reduces callbacks and warranty claims
- Faster cycle times allow more homes per year on the same land
Each of those factors contributes to the overall economic case. None of them is revolutionary in isolation. Together they form a different operating model for an industry that has changed remarkably little in decades.
Investor Logic Behind The Round
Baillie Gifford tends to favor companies with multi-decade growth runways and strong competitive positioning. BlackRock brings both capital and deep knowledge of the real-estate asset class. Together they provide more than money. They offer relationships, credibility with other institutional players, and long-term capital that does not demand immediate exits.
The construction technology sector has seen waves of enthusiasm before. Many startups raised capital during previous housing cycles only to struggle when the cycle turned. What distinguishes the current moment is the simultaneous pressure of high costs and chronic undersupply. When both the incentive and the necessity align, adoption curves can steepen faster than historical precedent suggests.
From an investor perspective the risk profile has also improved. Earlier funding rounds financed technology development and proof-of-concept projects. This latest round primarily supports commercial scaling and geographic expansion. The shift from pure research risk to execution risk is meaningful. Execution risk remains substantial, of course, but it is a different and often more manageable category of uncertainty.
Geographic Expansion And Local Adaptation
Texas and Florida have provided natural early markets. Favorable regulatory climates, strong population growth, and familiarity with innovative construction methods helped. Expanding into additional states will test how well the systems adapt to different climate zones, seismic requirements, and local building codes. The technology itself is flexible, yet each new jurisdiction brings its own approval processes and inspection regimes.
I expect the company will prioritize markets that combine housing shortages with relatively progressive permitting attitudes. Coastal cities with high land costs may prove especially attractive because the relative savings from faster, lower-labor construction become more valuable when the underlying dirt is expensive. Inland growth corridors with rapid household formation offer volume opportunities.
Local labor dynamics will also influence uptake. Regions facing acute shortages of framers and concrete crews have stronger economic reasons to experiment. Areas with abundant traditional labor may adopt more slowly. Over time the competitive pressure from lower-cost printed homes could force broader change even in resistant markets.
Sustainability Angle That Actually Matters
Much of the sustainability conversation around construction focuses on operational energy use after the home is occupied. Embodied carbon in materials and construction processes has received less attention until recently. Precise extrusion of concrete can reduce waste compared with traditional formwork. Optimized structural designs can use less material overall. Faster construction also shortens the period of site disruption and equipment emissions.
Whether these advantages prove decisive will depend on measurement and verification. Third-party life-cycle assessments and transparent reporting will be essential if the industry is to treat printed homes as a genuine environmental improvement rather than marketing greenwash. Early indicators look promising, yet the full picture will emerge only after thousands of homes have been monitored over multiple years.
The Human Side Of Robotic Construction
Any technology that reduces labor requirements raises questions about employment. In practice the picture is more nuanced. The most physically demanding and injury-prone tasks can be automated, while higher-skill roles in system operation, quality control, and finishing expand. Training programs that help traditional trades workers transition into these new positions will determine whether the technology is perceived as threat or opportunity by the existing workforce.
I’ve watched similar transitions in manufacturing. The plants that invested early in retraining often ended up with more stable, higher-paid workforces even as overall headcount per unit of output declined. Construction will likely follow a parallel path, though the decentralized nature of job sites makes coordination harder than in a factory setting.
What Success Would Actually Look Like
Success is not a single printed neighborhood that wins design awards. Real success means production builders routinely choosing the systems because the economics are simply better. It means lenders treating printed homes as standard collateral rather than experimental assets. It means local governments updating codes and inspection protocols to accommodate the new methods without creating unnecessary delays.
On the consumer side, success means buyers choosing printed homes because they are more affordable, more durable, or available sooner—not because they are novel. When the technology becomes invisible and the benefits are taken for granted, the industry will have truly changed.
We are still years away from that point. The current funding round buys time and resources to close the gap. The next twenty-four months will reveal whether the impressive pilot results can be replicated at commercial scale across multiple markets and under the control of third-party operators.
Risks That Still Need Watching
No growth story is without risk. Regulatory friction in new jurisdictions could slow expansion. Quality issues at scale would damage reputation quickly. Competition from other printing technologies or advanced modular approaches could intensify. Capital markets could turn less friendly if broader economic conditions deteriorate. Execution on the ambitious revenue targets will require disciplined hiring, supply-chain management, and customer support.
Perhaps the largest unknown is the pace of cultural acceptance within the conservative construction industry. Builders have seen many promising ideas fail to deliver. Trust is earned project by project. The early commercial customers who place money-down reservations are taking calculated risks. Their experience will shape the next wave of adoption more than any investor presentation.
Looking Further Ahead
If the technology continues to mature, the implications extend beyond single-family housing. Multi-family structures, accessory dwelling units, and even certain commercial applications become feasible. The same systems adapted for lunar construction could eventually influence extreme-environment building on Earth—disaster recovery, remote industrial sites, or climate-resilient communities.
I remain cautiously optimistic. The combination of urgent market need, credible technology progress, and sophisticated long-term capital creates conditions that earlier generations of construction innovators never enjoyed. Whether Icon becomes the defining company of this wave or simply proves the concept for others to scale remains to be seen. Either outcome would still represent meaningful progress against a housing shortage that has resisted conventional solutions for years.
The next chapter will be written in the subdivisions and permitting offices of cities across the country rather than in investor decks. That is exactly where it should be written. Real change in how we build homes has always been measured in completed foundations and families moving in, not in funding announcements. The two hundred million dollars just committed simply makes those foundations more likely to appear faster and in greater numbers than before.
For anyone who has watched the housing market struggle under the weight of its own inefficiencies, the arrival of serious institutional backing for multi-story robotic construction feels like a genuine turning point. The printers are no longer experimental curiosities. They are becoming tools that established builders want to own. And that shift may ultimately matter more than any single valuation milestone.
The story is still early. Execution will decide everything. Yet for the first time in a long while the tools, the capital, and the market necessity appear to be aligning in the same direction. That alignment alone makes the coming years worth watching closely.