
Have you ever watched a stock rip higher and felt that mix of excitement and suspicion at the same time? That is exactly the mood around Bloom Energy stock right now. The company sits in the middle of one of the loudest themes in markets: AI data centers that need more electricity than the grid can deliver on time. The run has been enormous. The temptation to jump in is obvious. And yet the more useful question is not whether the story is real. It is whether the price already assumes too much of that story too soon.
Why Bloom Energy Became The AI Power Trade
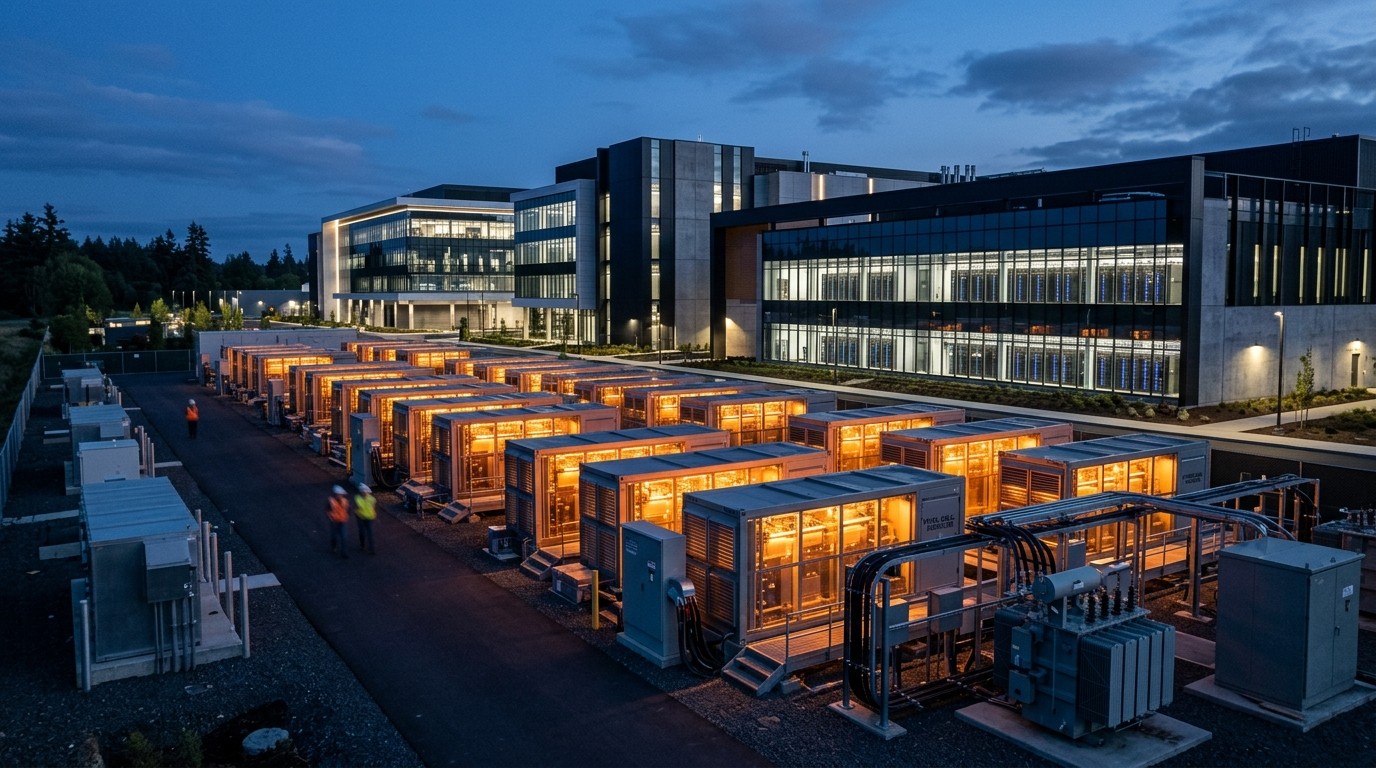
Behind-the-meter power used to sound like a niche industrial idea. Then AI clusters started arriving faster than substations, transmission lines, and utility approvals. Data center developers suddenly needed electricity that did not depend on a multi-year interconnection queue. That is where Bloom Energy entered the conversation with modular fuel-cell systems that can sit on site, scale in blocks, and start producing power far sooner than a traditional grid hookup.
I have found that the market loves a simple bottleneck. AI models get the headlines. Chips get the prestige. Power is the unglamorous constraint that decides how many racks can actually turn on. If energy is the limiting factor, then any company that can deliver usable megawatts without waiting on the public grid becomes more than a hardware vendor. It becomes a capacity unlock.
Bloom’s systems convert fuel into electricity without combustion. That matters for operators who want dense, relatively clean, and fairly compact generation next to a facility rather than a giant thermal plant miles away. The units are designed as scalable modules. In theory, a developer can add capacity as a campus grows instead of betting the entire project on one distant interconnection date.
If you want exposure to the electricity powering the AI build-out, this remains one of the cleanest ways to play it. Long term, the stock can still go much higher over the next few years.
That is the bull case in one breath. The caution sits in the next breath. After a year like this, popularity and price often travel together. A popular narrative can be correct and still be expensive.
The Speed Advantage That Changed The Conversation
Grid delays are not a rumor. Anyone following data center development has heard the same complaint: land is available, capital is available, chips are ordered, and then the project waits on power. Years, not months. Bloom’s pitch is that onsite generation can compress that timeline. Management has pointed to a delivery window measured in weeks for at least one major customer campus. Whether every future site looks that fast is another question. The signal still matters. Speed is a product feature now.
Think about how developers measure a facility. They talk in gigawatts of continuous power because energy sets the ceiling. A campus that cannot secure electrons cannot fill halls with accelerators. That is why “behind the meter” stopped sounding like an engineering footnote and started sounding like a growth market.
In my experience, investors underestimate how much time risk is worth. A slightly higher cost of power can still look attractive if it brings a site online a year earlier. Lost revenue from an idle building is not theoretical. It is the entire point of the AI race.
What The Recent Results Actually Showed
Demand has already shown up in the numbers, not just in conference-call poetry. Second-quarter revenue jumped to about $1.07 billion, a 166% increase, and cleared estimates by a wide margin. Adjusted earnings of 78 cents a share nearly doubled what the Street had modeled. Guidance moved with the print. Full-year revenue was lifted to a range of $3.9 billion to $4.2 billion. The midpoint implies the business can roughly double sales in a single year.
That is not a rounding error. That is an operating company being pulled forward by a customer set that used to move more slowly. The next report is due in late October. Markets will look for proof that the acceleration is still intact, not just a one-quarter spike from a handful of large deployments.
Perhaps the most interesting aspect is the customer mix. Management has talked about buy-in from major hyperscalers, more than a dozen neoclouds, and AI labs. That is a broader tent than a single logo. Diversification does not remove concentration risk entirely. It does reduce the chance that one delayed campus kills the whole thesis.
| Signal | What It Suggests | Investor Risk |
| Revenue doubling trajectory | AI power demand is converting into orders | Can growth stay this hot after an easy compare? |
| Fast onsite deployment | Speed is a real product advantage | Not every site will match the best-case timeline |
| Hyperscaler and neocloud interest | The technology is getting commercial validation | Large buyers can still squeeze pricing later |
| Premium valuation | The market already believes the story | A miss or a pause can hit the stock hard |
Why The Stock Ran So Far, So Fast
Shares have surged about 219% this year, including a 34% burst this month alone. They have nearly doubled since the name last became a loud market conversation in February. That kind of move changes the homework. You are no longer asking whether Bloom belongs in the AI power debate. You are asking what is left in the price.
Valuation is the cold shower. The stock trades around 108 times this year’s expected earnings and about 59 times next year’s estimates. Those are not “show me” multiples. Those are “keep showing me, every quarter, without a wobble” multiples. Growth stocks can live there for a while. They rarely live there comfortably through a disappointment.
I do not think expensive automatically means wrong. I do think expensive means fragile. A company can execute well and still give investors a rough ride if the starting point already prices perfection.
Behind-The-Meter Power Is Bigger Than One Ticker
Bloom is not the only answer to stranded data center demand. Large industrial turbines, onsite generation packages, and hybrid setups all compete for the same scarce commodity: time-to-power. Some investors prefer the scale of giant turbine makers. Others like the modular profile of fuel cells. The market does not need a single winner for the theme to work. It does need more electrons, faster.
That competition is healthy and a little inconvenient. If turbines become easier to site, or if utilities suddenly clear interconnection backlogs, the urgency premium fades. If fuel remains costly or policy around onsite generation tightens, the economic case gets messier. The AI power shortage is real. The exact vendor stack is still being negotiated in public.
I’ve found that theme investing works best when you separate the bottleneck from the brand. The bottleneck is electricity. The brand is whichever company can deliver it with acceptable cost, acceptable emissions, and acceptable speed. Bloom currently looks like one of the more direct public expressions of that bottleneck. Direct is not the same as cheap.
How Data Centers Actually Think About Power
Operators do not fall in love with generation technology for its own sake. They care about four practical things: how fast it can be installed, how reliable it stays under load, how the economics look over a multi-year contract, and whether the setup complicates permitting. Fuel cells can win on speed and modularity. They still have to win on uptime and total cost.
- Time-to-power can outweigh a modest cost disadvantage.
- Modular blocks help campuses expand without redesigning the whole plant.
- Primary power and backup power can sit in the same conversation.
- Customer concentration still matters even when the logo list looks impressive.
- Fuel supply, maintenance, and site constraints can slow a beautiful slide deck.
That last point is easy to skip. A factory-ready module is not the same thing as a fully commissioned energy system next to a live facility. Permits, fuel logistics, interconnection for any leftover grid support, and service capacity all sit between an order and a megawatt that actually bills.
Still, the commercial validation is hard to dismiss. When large cloud builders and AI labs start treating onsite fuel cells as more than a pilot, the technology graduates. Graduation usually brings volume. Volume usually brings scrutiny on margins.
The Case For Waiting Instead Of Chasing
A well-known market commentator put it bluntly this week: Bloom remains a favorite way to gain exposure to behind-the-meter electricity for the AI build-out, but the stock should not be chased after this kind of sprint. Wait for a pullback. Treat the dip as a gift for long-term holders rather than proof that the story broke.
That stance is less dramatic than it sounds. It is just old-fashioned respect for entry price. If the long-term path can still run higher over several years, then paying 10% or 20% less on a shakeout may matter more than catching the exact week the next contract leaks into the press.
Wait for a pullback, because one is coming, and it will likely be another opening for patient investors rather than a funeral for the thesis.
Why assume a pullback arrives? Because crowded trades breathe. After a 200%-plus year, positioning gets one-sided. Momentum funds lean in. Shorts get squeezed and then look for a reason to return. A slightly softer quarter, a delayed installation, or a broader risk-off day in high-multiple growth names can do the job. None of that has to invalidate the AI power shortage.
I’ve watched this pattern enough times to stay a little stubborn about it. The first question is quality of business. The second question is quality of price. Too many people stop after the first question when a story is fashionable.
Valuation Is Not A Vibe. It Is A Constraint
At roughly 108 times current-year earnings and 59 times next-year earnings, Bloom is priced like a company that will keep compounding at an elite rate. Maybe it will. The raised revenue range suggests management sees a thicker pipeline than the market modeled a few months ago. The danger is mathematical. When a multiple is this rich, growth has to stay surprising just to keep the stock flat.
There is a simple way to think about it. If sales double and the multiple compresses by a third, the stock may not do much. If sales double and the multiple holds, the stock can still work. If sales merely grow fast instead of spectacularly, the multiple can do more damage than the income statement can repair in a quarter or two.
Rough investor checklist:
  Business quality: improving
  Theme strength: very high
  Customer proof: expanding
  Valuation cushion: thin
  Best tactic after a melt-up: patience
None of this is a short thesis. It is a timing thesis. Those two things get mixed up constantly. A stock can be a strong multi-year holding and a poor next-month purchase at the same time. That sentence should be taped to more trading screens.
What Could Keep The Bull Case Alive
The optimistic path is straightforward. AI campuses keep slipping on utility timelines. Bloom keeps converting interest into installed systems. Revenue stays on a doubling-type trajectory for longer than skeptics expect. Service revenue becomes a larger slice of the model. Manufacturing scale improves unit economics. The stock’s multiple compresses a bit, but earnings grow fast enough that shareholders still come out ahead.
There is also a strategic angle. If onsite generation becomes a standard design choice rather than an emergency workaround, Bloom stops being a spike-cycle vendor and starts looking like infrastructure. Infrastructure gets valued differently. Not always cheaper. Often more durable.
Customer quality helps that transition. Hyperscalers do not adopt a power architecture lightly. Once a design wins a campus standard, follow-on buildings can arrive with less educational selling. That is how a lumpy equipment business begins to look more repeatable.
- Watch whether new logos turn into multi-site programs.
- Watch whether installations stay close to promised timelines.
- Watch gross margin as volume rises, not just top-line growth.
- Watch how much of the backlog is concentrated in a few campuses.
- Watch the next earnings print for guidance quality, not just a beat.
What Could Break The Spell
Every hot industrial-growth story has the same failure modes. Execution slips. A key customer delays. A cheaper alternative becomes good enough. Policy or fuel costs move the wrong way. The market decides that “AI power” was a one-year scarcity trade instead of a decade-long build.
Competition deserves more respect than slide decks usually give it. Large turbine platforms have scale, service networks, and brand trust with industrial buyers. If those machines can be delivered faster than people assume, Bloom’s speed premium shrinks. If hybrid sites mix technologies, Bloom may win pieces of a campus rather than the whole power envelope.
Financing conditions matter too. Data center development is capital intensive. A tighter credit market or a reassessment of AI return on investment can slow groundbreakings. Power vendors feel that with a lag, then all at once.
And then there is simple market structure. A stock that has already multiplied can become a source of funds when portfolio managers rebalance. No scandal required. Just math and human nature.
How I Would Frame The Position Size Question
This is where a little plain talk helps. If you already own Bloom from lower levels, the debate is about whether to add, trim, or sit. Adding into vertical strength is a choice, not a duty. Trimming a slice into strength can fund a later re-entry without forcing you to abandon a theme you still like. Sitting is underrated. Doing nothing is also a decision.
If you do not own it, the burden of proof is higher. You need a reason to pay today’s multiple rather than wait for the market to offer a better sticker price. That reason might be a belief that estimates are still too low. Fair enough. Just be honest that you are underwriting continued estimate revisions, not a neglected asset.
Personally, I would rather be slightly late on a high-quality compounder than early on a crowded melt-up. That bias has cost me upside before. It has also saved me from owning air. Both outcomes are real. The second one stings longer.
Reading The Next Earnings Report The Right Way
The late-October print will attract a lot of noise. A beat alone will not settle the debate. The useful details will sit underneath the headline.
Look at the mix between product and service. Look at comments on delivery timelines. Look at whether the raised full-year range still has room or whether management is already hugging the top. Look at any language around fuel costs, manufacturing bottlenecks, and customer concentration. Look at order timing. A strong quarter funded by pulling work forward can leave a softer setup behind it.
Guidance quality often matters more than the quarter just reported. Markets can forgive a messy print if the future looks bigger. They are less kind when a beautiful print arrives with cautious words about the next two quarters.
The Broader AI Electricity Problem Is Not Going Away
Zoom out and the backdrop still favors onsite solutions. Model training and inference keep getting hungrier. Utilities cannot conjure transmission overnight. Communities push back on giant new plants. Permitting remains slow. That combination supports a multi-year need for generation that can be placed closer to load.
Does that guarantee one equity wins? Of course not. Themes create a pond. Stocks are fish. Some grow. Some get eaten. Some look huge in a small tank and then face the open water of competition and valuation.
Even so, the structural shortage of timely power is one of the cleaner observations in this whole AI cycle. Compute without electricity is sculpture. Pretty, expensive, and inert.
A Practical Way To Stay In The Theme Without Forcing The Entry
There is no rule that says exposure to AI electricity has to happen through a single high-multiple name on its hottest day. Some investors will prefer a basket of power-equipment, utility, and infrastructure names. Others will wait for Bloom specifically because the product map is cleaner. Both approaches can be rational.
A staged plan is usually saner than a heroic all-in. Define the price zone where the story becomes attractive again. Decide the maximum weight the name can occupy in a growth sleeve. Write down what would falsify the thesis. Then let the market work. That sounds dull because it is dull. Dull process is how people survive exciting stocks.
If a pullback never comes and the business keeps exploding higher, you will feel smart for missing a dip that never existed and a little annoyed about the upside you did not capture. That is an acceptable discomfort. The unacceptable discomfort is buying a crowded favorite solely because the chart looks unstoppable.
The Human Side Of A Momentum Story
Let’s be honest. Part of the attraction is social. Friends mention the ticker. Feeds fill with the same chart. The narrative is easy to repeat at dinner. AI needs power. This company makes onsite power. Therefore the stock must keep going. The logic is not fake. It is incomplete.
Incomplete logic is how good companies become bad purchases. I have done it. Most people who stay in markets long enough have done it. The correction is not to become cynical about every growth story. The correction is to keep a separate ledger for business quality and starting valuation.
Bloom’s business quality looks better than it did when the company was still fighting for broader commercial proof. That progress is the bullish part. The starting valuation is the adult supervision.
What “Favorite Way To Play It” Really Means
Calling a stock the favorite expression of a theme is not the same as pounding the table to buy it before the close. It means the product maps cleanly onto the bottleneck. It means the customer set is getting more credible. It means the revenue line is no longer a hope chart.
It also means the easy work is done. Identifying the theme was last year’s edge. Living with the multiple is this year’s job. That shift happens in every fashionable group, from cloud software to electric vehicles to anything with “AI” in the sentence. The names that last are the ones that keep converting narrative into cash while investors argue about the price.
So yes, Bloom Energy stock still belongs on a serious watchlist for anyone trying to invest in AI data center power. The technology is timely. The demand signal is no longer theoretical. The financial run-rate has changed. The missing piece is a less heroic entry.
A Clearer Bottom Line For Long-Term Investors
The market is not crazy for caring about Bloom. Data centers need power they cannot wait years to receive. Modular fuel cells offer a way around that queue. Results have started to match the pitch. That combination is rare and valuable.
What looks less wise is treating a 219% year-to-date winner as if it were still undiscovered. At more than 100 times this year’s earnings, the stock is asking investors to believe that the next few years will stay unusually kind. Maybe they will. I would rather let a pullback do some of the work.
If the thesis is truly multi-year, then a weaker tape should be useful. If a weaker tape destroys the thesis, then the thesis was never as durable as the slogan suggested. That is a fair test. Good stories survive it. Crowded trades sometimes do not.
For now, the disciplined stance is simple to say and harder to live with: respect the business, respect the theme, and respect the price. Bloom Energy can still be a powerful way to invest in behind-the-meter electricity for the AI build-out. The next gift may arrive when the crowd is a little less sure of itself.