

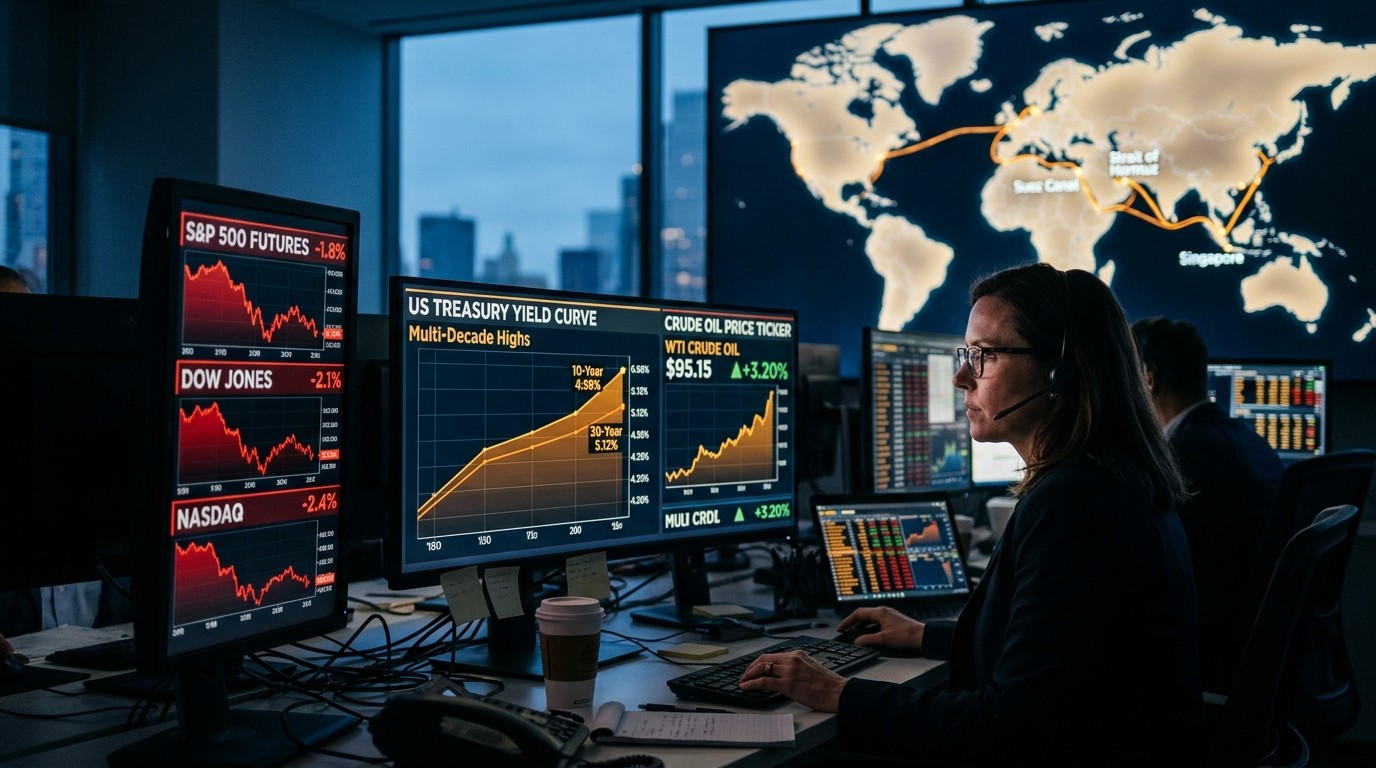

Ever watch a market open and feel the floor tilt before the cash session even starts? That is the mood this morning. Stock futures are lower, long-term borrowing costs are punching levels not seen in a generation, and crude is climbing again as traders cut back on hopes for a quick calm in energy supply. I have covered plenty of risk-off tapes, and this one has a familiar bite: few hiding places, a bid dollar, and a bond market that is doing most of the talking.
Why Futures Are Lower While Yields Keep Climbing
As of early New York hours, S&P futures were off about 0.6 percent and Nasdaq futures were down closer to 1 percent. Tech is carrying the pain again. Semiconductors and memory names are lagging for a second session. Software is holding up a little better, which is a relative comment only. Defensives and energy are doing more of the heavy lifting among cyclicals. That split tells you the tape is not about growth collapsing. It is about the cost of money and the price of fuel.
The yield curve is bear steepening. Front-end rates have given back a slice of Wednesday’s damage, while the long end has added to it. The 10-year yield has traded around 5.14 percent. The 30-year has printed its highest mark since 2004, near 5.44 percent depending on the print you catch. Those are not trivia numbers. They change discount rates on every long-duration asset, from growth stocks to data-center buildouts to household mortgages.
Higher bond yields are becoming a more meaningful headwind for equities. A calmer energy backdrop could ease some pressure, but the bigger story is the structural rise in global borrowing needs.
That is the quiet point I keep coming back to. Oil can whip around on headlines. Fiscal supply does not. When governments need to fund more for longer, the back end of the curve becomes a referendum on credibility, not just next month’s inflation print.
What Wednesday Set In Motion
The overnight slump did not appear from nowhere. Wednesday brought a stack of inflationary signals, a softish Treasury auction, and a rebound in energy prices. Stocks in Asia and Europe already paid the bill. Then the selling in government paper traveled east. Yields in Japan, Australia, and New Zealand jumped by more than 10 basis points on Thursday. Japan’s 10-year has been mentioned near levels last associated with the mid-1990s. That is the kind of sentence that still startles me when I type it.
The dollar remains bid. The broad dollar index is sitting less than 40 basis points from a 52-week high. Precious metals are softer, gold lagging after the currency and real-yield squeeze. Bitcoin is down nearly 1 percent on the same tape. When cash yields look this generous and risk premia are widening, speculative corners usually blink first.
Premarket Winners And Losers You Should Actually Notice
Single-name action is messy, which is honest. The so-called Magnificent Seven are mostly red: Alphabet off about 0.7 percent, Amazon 0.9 percent, Microsoft 0.6 percent, Tesla 1 percent, Nvidia 1.1 percent, Meta 2 percent. Apple is roughly flat, which in this tape almost looks like outperformance.
- A restaurant operator dropped about 5 percent after first-quarter sales missed the bar.
- A file-storage software name fell 5 percent after a bank cut it to sell and questioned how early the AI story was being priced.
- An online marketplace slipped 2 percent on valuation and growth concerns.
- A data-storage firm jumped 7 percent after a 2028 revenue outlook beat the Street.
- A casino group sank 9 percent after a would-be buyer walked away from taking the rest of the company.
- An online styling platform plunged 19 percent on a weaker 2027 earnings outlook.
- A biotech that had ripped higher on weight-loss data sold off 12 percent after launching a large equity-and-convert raise.
Away from the tape, a consortium tied to large asset managers is said to be close to a roughly $25 billion purchase of Asia-Pacific data centers. That is the other side of the same coin: long-duration capex still wants to get done, even while the market argues about who pays for it. There is also an awkward banking story about a leaked internal deal list that one firm is trying to contain. Markets hate sloppiness when spreads are already twitching.
Oil Is Back In The Driver’s Seat
Energy and agricultural contracts resumed leadership as traders reduced optimism for an imminent political solution. Brent has been higher by around 2.5 percent at points and has recovered nearly 10 percent from the week-to-date low. WTI has added about 1.4 percent off the highs. Comments from an Iranian official about a possible widening of conflict toward the Indian Ocean if attacks resume were enough to yank the bid back into crude. Hostile rhetoric and fading deal hopes will do that.
There is a second, more domestic wrinkle. Energy officials have told industry leaders to prepare for possible limits on diesel exports. I am not in the camp that a blanket ban is the base case. Even talk matters. If refiners cannot ship diesel freely, tanks fill, runs get cut, and gasoline can rise for the least intuitive reason: less crude going through the system. One large bank has sketched a scenario where runs drop by around 2 million barrels a day and gasoline supply shrinks by roughly 650,000 barrels a day. That is the sort of second-order math that bond traders notice even if equity screens stay glued to mega-cap names.
Saudi flows have also been in the mix. Reports of nearly 100 million barrels sold to Asian buyers since mid last week helped ease talk of an immediate regional crunch. That cargo still has to travel. Shipping rates through chokepoints and even the Panama Canal have been eye-watering, with some large vessels paying millions for a single transit. Logistics premia are inflation by another name.
The Policy Calendar Is Crowded On Purpose
Today’s watch list starts with the current-account balance and weekly jobless claims at 8:30 a.m. Eastern, August new-home sales at 10 a.m., and Kansas City factory activity at 11 a.m. Fed speakers are stacked too: Richmond, Cleveland, and Philadelphia voices through the morning after an overnight comment that more work is needed to get inflation down. Swaps have been fully reflecting three quarter-point hikes over the next year, with hedging for a fourth. That is a heavy load if growth stays firm and oil stays loud.
The political overlay is the meeting between the U.S. and Chinese leaders. A two-month extension of the trade truce, running to January 10, landed as a disappointment for anyone who wanted a longer runway. Markets often treat short extensions as a shrug rather than a hug. Rare earths, tech limits, and Taiwan remain live issues. “Super intelligence” was floated as a discussion topic. Fine. Traders will still want to know whether tariffs move, whether LNG faces a friendlier Chinese levy, and whether any language on technology actually changes cash flows.
Investors are flying a bit blind on energy diplomacy. Oil remains the key swing factor until talks produce something firmer than a calendar date.
Europe And Asia Are Not Bystanders
The Stoxx 600 has been down about 0.4 percent, with tech and autos at the bottom and energy at the top. Average European yields have also printed levels not seen in almost two decades. The French-German 10-year spread has widened toward 111 basis points, a zone that still makes old euro-crisis hands sit up. Higher energy costs hit European sentiment faster because the region imports so much of what it burns.
Company-level color in Europe was mixed in the usual way. A pub group rose after like-for-like sales improved. A Greek refiner gained on a higher target tied to diesel cracks. A Swedish health-additives name jumped on a reiterated buy call. A microcomputer maker surged more than 20 percent after first-half revenue nearly doubled. Fashion and housing names were weaker where guidance or tariff accounting failed to impress. That is a market picking winners by cash flow, not slogans.
Asia sold off for a second day. The regional benchmark dropped about 0.9 percent, with China among the weakest. Indian shares saw their sharpest drop in over two months after proposed insurance-commission caps hit financials. Japan was mixed after a long holiday. South Korea was closed. The People’s Bank signaled ample holiday liquidity, including large overnight operations. Liquidity can soothe funding. It does not rewrite a global term-premium story by itself.
Central Banks Are Talking Tighter, Not Softer
Two European decisions added to the inflation chorus. Switzerland held rates at zero but raised its inflation path and softened the language around currency intervention. The franc slipped on that tweak. Norway hiked 25 basis points to 4.50 percent and left the door open to more if prices stay sticky. Sweden held at 1.75 percent but its forecasts leaned hawkish, with hikes showing up later in the projected path. The krona eventually liked that tone.
Elsewhere, policymakers keep repeating a simple line: energy shocks look more persistent than hoped, second-round effects are not a closed case, and restrictive policy may need to stay restrictive or even tighten if fuel prices do not roll over. I have found that markets still want to treat every dip in crude as the start of disinflation. Lately, the dips have been pauses.
Rates, Auctions, And The Shape Of Stress
Treasuries were mixed early, curve steeper around a little-changed seven-year sector. Two-year yields were down about 3 basis points while long yields were up a similar amount. Bunds lagged a touch in the 10-year sector; gilts outperformed slightly. A $44 billion seven-year sale is on the calendar after a five-year auction that tailed by more than 3 basis points. When when-issued yields sit dozens of basis points cheap to last month, you know the bid is asking for a bigger concession.
Investment-grade dollar issuance has been thin so far today after five borrowers printed a combined $5.2 billion Wednesday with modest concessions and decent coverage. Weekly volume is still short of dealer forecasts. That matters if the calendar stays heavy and real money is already stuffed with duration.
| Market | Near-term pulse | Why it matters |
| U.S. 10-year | Near 5.13%–5.15% | Sets equity discount rates and mortgage math |
| U.S. 30-year | Highest since 2004 area | Flags term premium and fiscal supply worry |
| Brent crude | Back above $100 at times | Feeds inflation expectations and rate pricing |
| Dollar index | Close to 52-week high | Pressures metals, emerging assets, and earnings translation |
| Equity futures | S&P -0.6%, Nasdaq -1.0% | Shows duration and growth-stock sensitivity |
Credit Spreads Are Whispering About The AI Build
One of the more uncomfortable subplots is credit. Protection costs on large tech balance sheets have been pushing toward yearly wides. Circular financing talk around chip and cloud spending is no longer a niche chat. Before year-end, some strategists argue, markets may have to choose between living with firmer inflation or slowing a debt-funded capital-expenditure boom. Main Street has already absorbed years of higher prices. There is only so much household budget left to squeeze if energy and rates rise together.
Perhaps the most interesting aspect is how quickly the conversation flipped from “AI will pay for itself” to “who funds the power, the chips, and the interest expense if yields stay here.” That is not anti-technology. It is arithmetic. Long projects hate rising real rates.
Housing, Cards, And The Main Street Read
Mortgage rates near 7 percent are leaving fingerprints. Nearly one in five listings saw a price cut in August in one widely watched dataset, and a large share of sales included seller concessions. That is how markets clear when buyers cannot stretch the payment. Card spending is still growing year on year, but higher gasoline prices have opened a gap between higher-income and lower-income baskets once you strip out fuel. Soft landing stories look different depending on which checkout line you stand in.
New-home sales later this morning will not settle the debate. One print never does. Watch the mix: cancellations, incentives, and whether builders are buying down rates again. If claims stay contained while home demand fades, you get the awkward combo of a tight labor market and a strained rate-sensitive sector. The Fed has lived that puzzle before.
How I Would Read The Next 24 Hours
Start with claims. A clean number will not cap long yields if oil keeps ripping. A hot number plus firmer crude would likely extend the bear steepener. Then watch the seven-year auction. Poor demand after yesterday’s tail would advertise that real money wants more yield, not more duration. The leadership meeting is theater until the readout. Two extra months of a truce is not nothing. It is also not a structural deal on technology or energy trade.
- Map your duration. Long bonds and long-duration growth stocks are trading the same risk in different clothes.
- Separate crude beta from refiners. Export-rule talk can flip the diesel-gasoline relationship in a hurry.
- Treat dollar strength as a tax on metals and on overseas earnings translations.
- Do not assume one diplomatic dinner resets term premium. Fiscal supply is the slow variable.
- Keep some dry powder. Wide overnight ranges punish people who need liquidity at the worst print.
In my experience, the tapes that hurt most are the ones where several small stories rhyme. Strong activity data. A sloppy auction. A hostile energy headline. A short trade-truce extension. Hawkish tweaks from smaller central banks. None of those alone would have defined the week. Together they pulled the 30-year to a two-decade high and knocked the shine off records in large-cap tech.
A Longer View On Borrowing Needs
Zoom out and the structural piece is blunt. Aging populations, defense outlays, industrial policy, and grid spending for compute all want capital at the same time. Private AI capex is being compared, not unfairly, with historic U.S. infrastructure waves. Those earlier waves were financed in very different rate regimes. If inflation stays above target for years, as several officials keep reminding anyone who will listen, the market will charge a higher term premium. That is not a moral judgment. It is a clearing price.
Could a genuine de-escalation in the Middle East knock oil down and give bonds a breather? Yes. Would that erase the need for heavy issuance? No. I would rather be early in respecting supply than late in explaining why 5 percent on the 10-year was not a ceiling after all.
Currencies And Commodities Around The Edges
G10 currencies are mostly softer against the dollar, with the Norwegian krone leading after the hike and the Swiss franc lagging after the intervention-language change. Dollar-yen has pushed through its 200-day average for the first time since early September, a technical tell that often brings more official verbal intervention talk even if action stays on the sidelines. Gold has been offered toward the lower end of a multi-day range, with the 100-day average sitting just overhead as resistance. Silver is similarly heavy. Copper is mixed after a mine interruption in Chile, which would have mattered more on a risk-on day.
Natural gas in Europe firmed with the broader energy complex. Retail fuel prices in China were raised in the latest bi-monthly adjustment. Those are the small gears that keep inflation sticky even when headline indices take a month off.
What Would Change My Mind
I would get less defensive on duration if three things showed up together: a decisive drop in front-month crude that sticks, an auction that stops through rather than tails, and claims or housing data that clearly cool demand without a disorderly growth scare. One of those is a headline. Two is a session. Three is a regime shift, and we are not there yet.
Until then, the working title for this market remains the same. Futures tumble as yields hit multi-decade highs and oil surges. It is not poetry. It is the price action. And if tonight’s diplomacy is thin, tomorrow’s open may rhyme with this one.
Stay nimble. The bond market is speaking in a loud voice. Equities are still deciding whether to listen.



