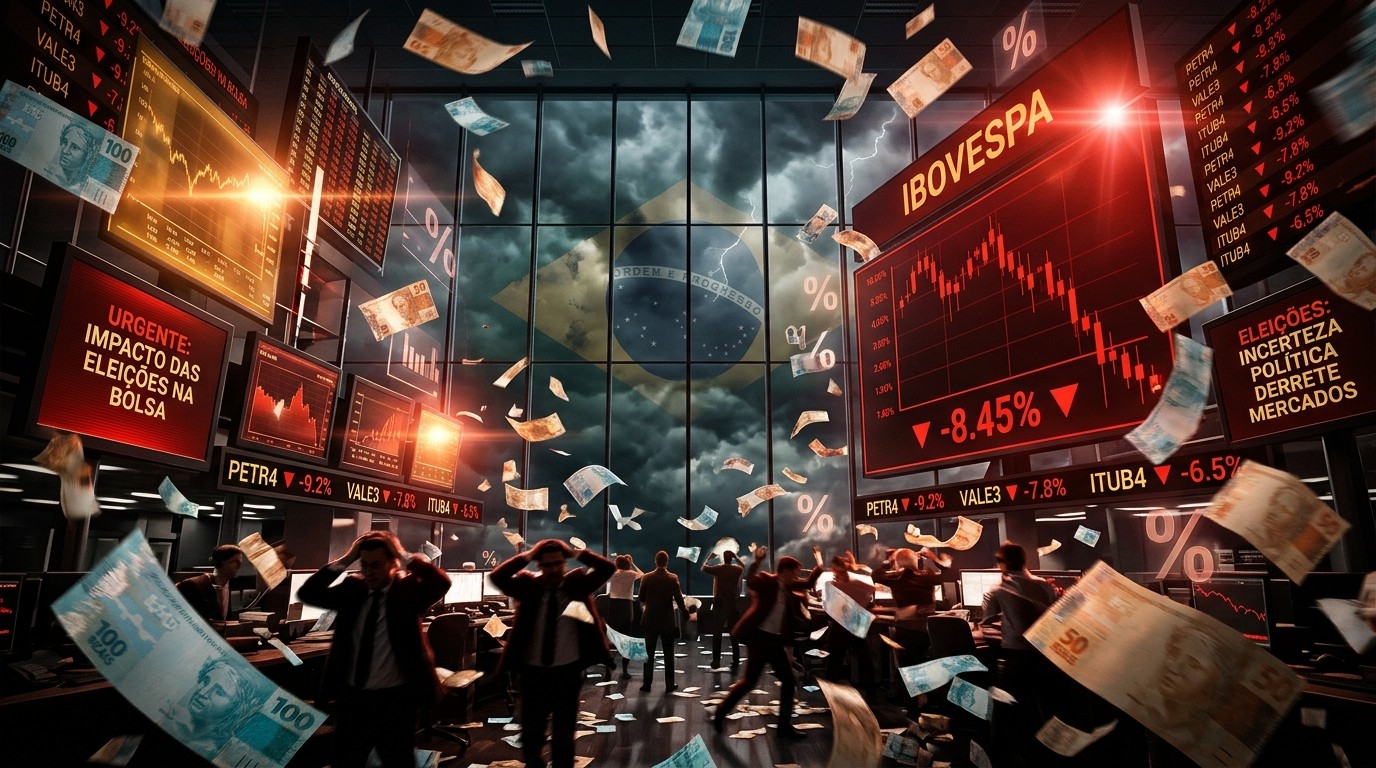

Have you ever watched a market that seemed rock solid one day turn into pure chaos the next? That is exactly what hit Brazilian investors this week. Shares tanked hard, the currency took a beating, and the overall mood shifted from cautious optimism to outright panic almost overnight. The trigger? A political outcome few in the financial community saw coming with this level of force.
What Sparked The Sudden Market Meltdown
Markets hate surprises. They especially hate surprises that arrive after months of positioning for the opposite result. When the final tallies confirmed Luiz Inácio Lula da Silva had secured another term, the reaction was swift and brutal. The main share index dropped nearly fourteen percent in a single session. The real currency lost roughly eight percent against the dollar. Put those two moves together and the dollar-denominated version of the market sank close to twenty-five percent. Numbers like that do not appear every day. In fact, some observers immediately reached for the same language used after the famous 1987 crash on Wall Street.
I have followed emerging markets long enough to know that political shifts often produce sharp moves. Still, the scale here felt extreme. Traders had largely priced in a win for the right-wing challenger. Polls showed a tight race, yet the pricing told a different story. When reality arrived, the adjustment was violent. Positions built on one assumption had to be unwound at any price. Liquidity dried up in places. Stops got triggered. The feedback loop took over.
Why Investors Had Bet The Other Way
Going into the second round, the veteran left-wing candidate entered as something of an underdog. He had finished second in the first round. History since the return to democracy suggested that trailing candidates rarely close the gap. Many professional desks treated a right-wing victory as close to certain. That conviction showed up in asset prices. Bond spreads tightened. Equity valuations held firm. The currency traded with a mild bias toward strength. All of that positioning created fuel for the subsequent fire.
In my experience, markets in Latin America carry a long memory of fiscal stress under left-leaning administrations. Whether those memories are always fair is another debate. What matters for price action is that the bias exists. When the unexpected winner emerged, those old fears flooded back into the pricing mechanism. The sell-off became self-reinforcing. Local funds cut exposure. Foreign investors reduced risk. The moves fed on each other.
The Policy Promises That Spooked Capital
Campaign platforms matter less for day-to-day trading than for the direction of medium-term risk premiums. This time the platform contained several items that immediately raised eyebrows among bond and equity holders. A fifteen percent increase in family benefits sat near the top of the list. A temporary federal fuel tax holiday followed. New monthly stipends for low-income university students appeared. Free public transport on weekends and a cut in the maximum working week from forty-four to forty hours without any reduction in pay rounded out the package.
None of these measures look radical in isolation. Taken together they signal a clear preference for expansionary fiscal policy at a moment when public finances already look stretched. Gross public debt sits near eighty-three percent of output. The fiscal deficit approaches ten percent of GDP. Interest payments alone consume roughly thirty-five percent of current government revenue. Those figures leave limited room for error. Markets noticed.
Interest costs eat a large share of revenue in Brazil, leaving policymakers with fewer options when they want to expand spending.
Perhaps the most interesting aspect is how quickly the narrative shifted from growth potential to fiscal sustainability. The same market that had been willing to overlook high interest rates as a sign of policy credibility suddenly viewed those rates as a burden. Real yields remain among the highest in the emerging world. That fact used to attract capital. Overnight it became a vulnerability.
Historical Context Offers A Different Lens
Panic rarely lasts forever. History in this market shows repeated episodes of overreaction followed by recovery. During earlier terms the economy expanded at more than four percent annually for extended stretches. Commodity cycles helped, of course. Yet policy pragmatism also played a role. The current leadership has already demonstrated a willingness to work within institutional constraints once in office.
Since the return to power in early 2023 the main equity benchmark is still up more than fifty percent even after the latest drop. That longer-term performance sits awkwardly next to the short-term fear. Congress leans right. Many spending plans will face resistance. The practical outcome may prove far less expansionary than the campaign trail suggested. Investors who can look past the immediate noise often find the subsequent periods offer better entry points than the euphoric moments.
Commodity prices remain supportive. Brazil sits on substantial energy and agricultural resources. Trade balances have been swinging toward surplus. In an environment of elevated global inflation for food and energy, those export strengths provide a natural buffer. Currency weakness, painful as it feels in the short run, also helps exporters compete. The adjustment mechanism is already at work even while the headlines scream crisis.
How The Currency Move Amplifies Everything
An eight percent drop in the real against the dollar ranks among the larger single-day moves in the modern floating-rate era. The last time something similar occurred stretched back more than two decades. Currency depreciation feeds directly into inflation expectations. It raises the local currency cost of dollar-denominated debt. It can force the central bank into a tighter stance even when growth concerns exist. The feedback into equity valuations arrives quickly because so many large companies carry dollar costs or compete in global markets.
Yet depreciation also improves the competitive position of exporters. Agriculture and mining companies often see their local earnings rise when the currency falls. That offset is rarely perfect or immediate. Still, it prevents the equity market from collapsing entirely. The dispersion between sectors becomes extreme. Domestic-focused names get hit hardest. Export-oriented names hold up better or even advance once the dust settles. Smart money watches those relative moves carefully.
Investor Positioning Before The Vote
Looking back at the weeks leading into the second round, positioning data told a clear story. Foreign ownership of local bonds and equities had climbed. Hedge funds ran short volatility strategies. Local pension funds increased equity allocations. The consensus view treated a right-wing win as the base case. Risk models calibrated around that assumption. When the result arrived, those models broke. Forced selling followed. The speed of the move created its own liquidity problems.
I find it useful to remember that emerging market liquidity is always thinner than it appears in calm periods. A few large sellers can move prices a long way when buyers step aside. That is what happened here. The initial reaction overshot any reasonable reassessment of fundamentals. Opportunity often hides inside that overshoot. The question becomes timing and patience.
Fiscal Arithmetic And Market Math
Public debt at eighty-three percent of GDP is high for an emerging economy. Interest rates that remain elevated make the debt service burden heavier still. When a new administration signals additional spending without clear offsetting revenue measures, the arithmetic looks challenging. Markets respond by demanding higher risk premiums. Equity multiples compress. Bond yields rise. The currency weakens. All three of those moves happened simultaneously this week.
Still, the institutional framework contains checks. A right-leaning Congress can block or dilute large spending packages. Independent central bank policy remains intact for now. Past experience shows that once the political heat of the campaign fades, more moderate voices often gain influence inside the government. The gap between rhetoric and reality can be wide. Investors who treat the campaign platform as a precise policy blueprint usually end up surprised in the other direction.
- High real interest rates already constrain fiscal space
- Debt service consumes a large share of revenue
- Commodity export strength provides an external buffer
- Congressional composition limits unilateral spending
- Historical growth performance under similar leadership was solid
Sector-Level Impact Across The Market
Not every stock moved the same way. Banks and domestic retailers absorbed the heaviest hits. Rate-sensitive names suffered as yields climbed and growth expectations softened. Utility companies faced questions about future tariff policy. On the other side, major exporters in agriculture and energy held up relatively well. Some even posted gains once the initial panic eased. That dispersion creates both risk and opportunity for active managers.
In my view the financial sector remains the clearest barometer of domestic confidence. Loan growth expectations, net interest margins, and asset quality all respond to the broader macro outlook. A weaker currency and higher rates can pressure non-performing loans over time. At the same time, higher rates support margins if deposit costs lag. The net effect depends on the path of policy from here. Clarity will take weeks or months rather than days.
Global Emerging Market Spillover Risks
Large moves in one of the biggest emerging equity markets rarely stay contained. Risk appetite across the asset class often shifts. Funds that run dedicated Latin America strategies face redemptions. Broader emerging market indices feel the weight of the Brazilian component. Currency correlations rise. The same investors who fled Brazilian assets sometimes reduce exposure to other high-yielding markets as a portfolio hedge. Contagion is never mechanical, yet it remains a live risk when volatility spikes this hard.
Commodity markets also register the noise. Brazil is a major producer of iron ore, soybeans, oil, and coffee. Any perception of policy uncertainty can affect production plans or export taxes over longer horizons. For now the physical markets look calm. The financial markets have done the reacting. That separation often proves temporary.
Practical Considerations For Portfolio Managers
Anyone running money through this episode faces familiar questions. Do you treat the move as a buying opportunity or the start of a larger derating? How much weight do you place on campaign promises versus institutional constraints? Is the currency cheap enough to attract longer-term capital once the political noise fades? These questions do not have clean answers on day one.
I have found that the most successful approaches combine patience with selective risk-taking. Broad index exposure often underperforms in the immediate aftermath of political shocks. Stock selection that favors companies with hard-currency revenues or pricing power tends to fare better. Currency hedges can protect capital during the volatile window. Position sizing remains critical. Liquidity can disappear when you need it most.
| Market Segment | Immediate Reaction | Medium-Term Sensitivity |
| Domestic Retail | Sharp sell-off | High to growth outlook |
| Export Commodities | Relative resilience | Linked to global prices |
| Financials | Heavy pressure | Tied to rates and credit |
| Utilities | Policy uncertainty | Regulatory risk |
The Role Of Commodity Cycles Going Forward
Brazil’s economy still leans heavily on natural resources. Rising global demand for food and energy supports the trade balance even when domestic policy looks less orthodox. That external cushion has rescued the country more than once. It will likely matter again. Higher commodity prices feed directly into government revenues through royalties and taxes. They also support the currency over time. The political cycle and the commodity cycle do not always move together. When they diverge, the commodity side often proves more powerful for asset prices.
Perhaps the most interesting aspect sits in the agricultural sector. Brazil has become a powerhouse in soybeans, corn, and beef. Climate and productivity gains continue. Any sustained rise in global food prices flows straight into the local economy. That structural strength does not disappear because of one election result. Markets tend to rediscover it after the initial shock fades.
Lessons From Previous Political Transitions
Earlier transitions produced similar patterns. Markets sold first and asked questions later. Valuations reached extremes. Then a combination of pragmatism, external support, and time restored confidence. The same sequence may unfold again. The difference this time is the starting level of public debt and the global interest rate environment. Higher rates everywhere make fiscal space more precious. That constraint could force earlier compromises than in previous cycles.
Still, the track record of growth during previous periods under similar leadership remains relevant. Expansion above four percent was achieved. Poverty rates fell. The middle class expanded. Those outcomes required both favorable external conditions and workable domestic policy. The external conditions look supportive again. The domestic policy path will reveal itself over the coming quarters rather than the coming days.
Volatility As A Feature Not A Bug
Emerging equity markets deliver higher returns over long horizons partly because they deliver higher volatility along the way. Political shocks form part of that volatility package. Investors who cannot tolerate sharp drawdowns should maintain lower allocations. Those who can stomach the swings often harvest better long-term results. The current episode fits the historical pattern of overreaction followed by partial recovery. Timing the exact bottom remains difficult. Building exposure gradually as clarity improves has worked better than heroic single-day bets in most past cases.
Currency volatility adds another layer. Hedging costs rise when implied volatility spikes. Leaving exposures unhedged can produce large swings in dollar returns. The right approach depends on the investor’s base currency, risk tolerance, and time horizon. There is no universal answer. What matters is conscious choice rather than accidental exposure.
Looking Ahead To The Next Phase
The immediate shock has already occurred. The next phase will revolve around cabinet appointments, early policy signals, and the reaction of Congress. Markets will parse every statement for clues about the true fiscal path. Any sign of moderation could trigger a relief rally. Continued emphasis on large spending increases without offsets would keep risk premiums elevated. The range of possible outcomes remains wide.
Central bank policy will also matter. Inflation remains a live concern. Currency weakness feeds into prices with a lag. The monetary authority may need to keep rates higher for longer even if growth softens. That combination of tight money and looser fiscal policy creates classic tensions. How those tensions resolve will shape the investment landscape for the next year or more.
In the end the Brazilian market has delivered both spectacular gains and gut-wrenching losses over the decades. The latest chapter continues that tradition. Investors who understand the structural strengths of the economy, the institutional checks that still exist, and the tendency of markets to overshoot political news often navigate these episodes more successfully than those who react only to the headlines. The sun still shines on large parts of the economy even when the financial weather turns stormy.
The coming weeks will test that view. Clarity on the actual policy mix will arrive gradually. Until then volatility is likely to remain elevated. That environment rewards preparation, selective risk-taking, and a clear understanding of what has already been priced. The Black Monday label may stick in the short-term memory. Whether it marks the start of a lasting derating or simply another overdone reaction remains the central question for anyone with capital at stake.