
I still remember the last time oil prices spiked this sharply and how quickly the mood shifted across trading floors. Watching Brent crude hover near the $109 mark this weekend brought that same uneasy feeling right back. Traders are once again balancing two separate flashpoints at once, and neither looks ready to fade quietly.
Why Oil Markets Are Holding Firm Near Recent Highs
Brent crude futures settled around $108.82 a barrel after shedding just over a dollar, while the U.S. benchmark slipped a modest 26 cents to $101.15. Those numbers may look like a mild pullback on paper. In reality they still sit close to multi-month peaks and reflect a market that refuses to look away from fresh supply threats.
What stands out most is the combination of events. On one side, Ukrainian forces resumed large-scale drone operations against Russian energy infrastructure after a short pause. On the other, two separate tanker incidents in the Persian Gulf added another layer of anxiety. Together they create the kind of overlapping risk that keeps prices elevated even when some traders prefer to take profits.
In my view the real story is not the exact price print on any given Sunday. It is the persistent sense that physical barrels could become harder to move if either situation deteriorates further. Markets hate uncertainty, yet they have grown almost accustomed to living with it in the energy space.
Ukraine Resumes Targeted Energy Infrastructure Attacks
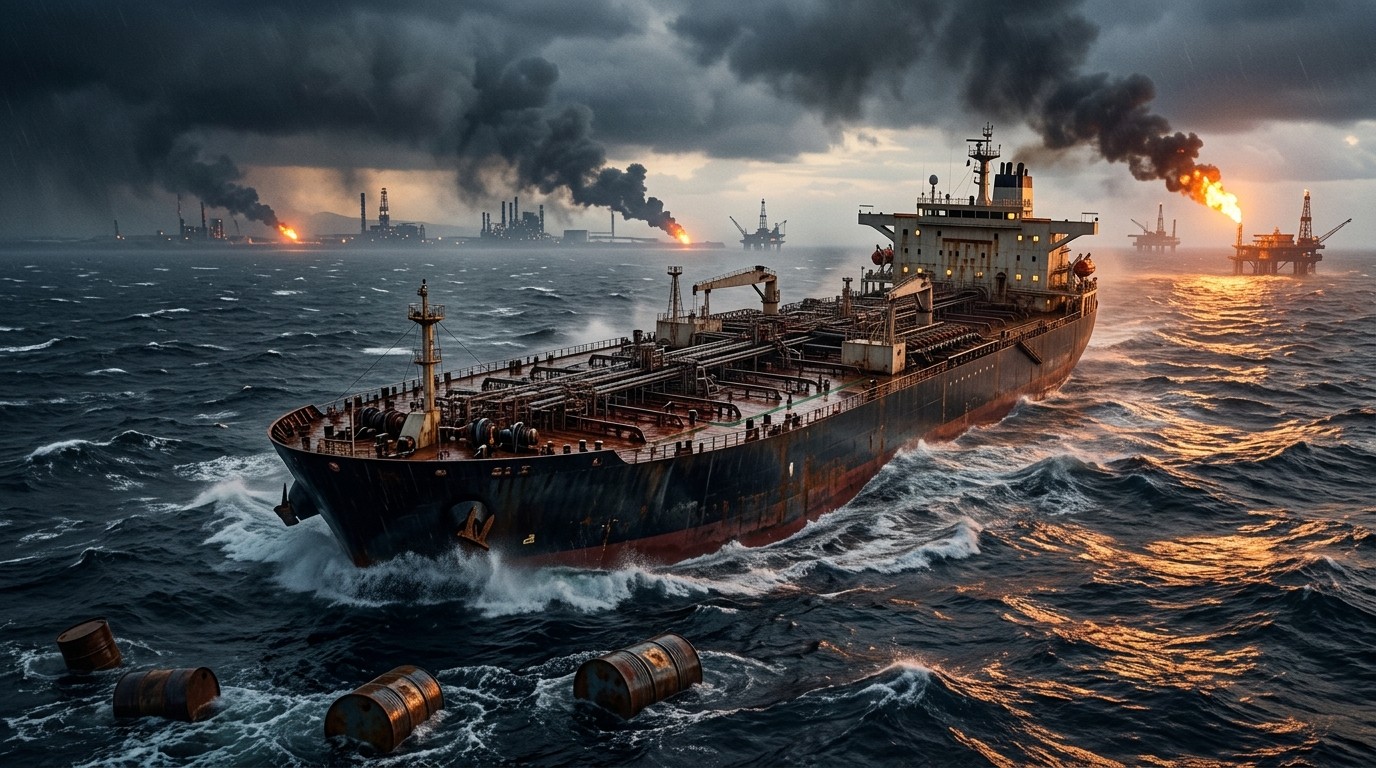
After a brief lull following earlier diplomatic comments, Ukrainian operators launched a significant wave of drones toward facilities in the St. Petersburg area. Local authorities confirmed fires at both an oil terminal and a nearby depot. Smoke was clearly visible across parts of the city.
The terminal in question typically handles roughly 120,000 barrels per day of refined products, mainly fuel oil. That volume is not enormous compared with Russia’s overall export capacity, yet every disruption adds friction. At this stage the full extent of the damage remains unclear. Still, the mere fact that operations were interrupted is enough to keep traders on edge.
What makes this round of strikes noteworthy is the timing. Ukraine had largely paused similar operations for several days after public statements suggested a temporary understanding. When Russian forces continued their own attacks on Ukrainian energy sites, Kyiv signaled it would respond in kind. The latest action appears to be exactly that response.
Supply disruptions, even temporary ones, tend to tighten the global balance faster than most models predict.
I’ve found that markets often under-estimate how long it takes to restore full throughput after a successful strike. Repairs can drag on, insurance costs rise, and shipping schedules get reshuffled. All of those secondary effects matter just as much as the initial explosion.
Tanker Incidents Add Fresh Tension in the Persian Gulf
While attention focused on the Black Sea region, two separate attacks on tankers occurred off the Saudi coast. One vessel came under rocket-propelled grenade fire from a small boat roughly 78 nautical miles northeast of Al Jubayl. Another ship, identified as the ST3, was struck by an unknown projectile.
These incidents fit a broader pattern of rising harassment in the Persian Gulf, the Strait of Hormuz, and the Gulf of Oman. The goal appears to be disruption of crude flows out of the region rather than outright destruction of every vessel. Even so, the psychological impact on ship owners and charterers is real.
Insurance premiums have already climbed in recent months. Crews grow more cautious. Some operators quietly reroute or delay voyages. None of those adjustments shows up neatly in daily price charts, yet they steadily reduce the effective supply available to the market.
Perhaps the most interesting aspect is how these two theaters interact. Traders now have to monitor both European refined-product flows and Middle Eastern crude exports at the same time. That dual pressure rarely ends with calm trading sessions.
How Traders Are Weighing the Immediate Price Reaction
Sunday’s modest decline in futures prices might look like relief. I read it differently. After a strong run higher, a one-dollar drop in Brent feels more like a pause than a reversal. Volume tends to be thinner on weekends, so the real test will come when full liquidity returns mid-week.
Many desks are still long the complex. They see limited downside as long as physical threats remain active. At the same time, some profit-taking is natural after prices pushed close to recent highs. The net result is a market that refuses to collapse yet also struggles to make a clean break higher.
- Brent remains anchored near the upper end of its recent range
- WTI continues to track the international benchmark with a modest discount
- Refined product cracks show mixed signals depending on the region
- Freight rates for certain routes have begun to firm again
One subtle shift I’ve noticed is the growing attention paid to fuel oil and middle distillates. When a terminal that specializes in those grades is hit, the impact can show up first in regional product markets before it fully registers in crude benchmarks.
Broader Implications for Global Energy Flows
Every successful strike on export infrastructure forces a redistribution of barrels. Russian product that cannot leave the Baltic has to find other routes or sit in storage. Middle Eastern crude that faces higher security costs becomes less attractive to some buyers. The global system adjusts, but the adjustment is rarely smooth.
Refineries in Europe and Asia watch these developments closely. A sudden loss of Russian fuel oil, for example, can tighten the bunker market or push more demand toward alternative grades. Those secondary ripples often last longer than the initial headline.
In my experience the market tends to price the worst-case scenario for a few sessions and then gradually dial it back if no further escalation occurs. The danger this time is that both flashpoints remain live. Ukraine has made clear it will continue responding, and the pattern of tanker harassment shows no sign of ending overnight.
What History Suggests About Similar Episodes
Looking back at previous periods of concentrated attacks on energy assets, prices usually stay elevated until clear evidence of de-escalation appears. Temporary truces have been announced before. They have rarely lasted when one side continues strikes on the other’s critical infrastructure.
The same logic applies to maritime security. Once a pattern of attacks becomes established, ship owners demand higher compensation and governments increase naval presence. Those measures help, yet they also raise the overall cost of moving oil. Higher costs eventually feed into the price of the barrel itself.
I keep returning to a simple observation. Physical markets care less about diplomatic statements and more about whether tankers sail on schedule and terminals load without interruption. Right now both of those conditions face fresh questions.
Key Variables Traders Will Watch This Week
Several practical indicators will matter more than the next set of political comments. First is any updated assessment of damage at the St. Petersburg facilities. Second is whether further tanker incidents occur in the coming days. Third is the reaction of major Asian and European refiners to any change in available grades.
- Confirm the operational status of the affected Russian terminal
- Track new maritime security reports from the region
- Monitor product crack spreads for signs of tightening
- Watch inventory data for unexpected draws
- Assess any shift in freight rates on key routes
None of these items is glamorous. All of them feed directly into the supply-demand balance that ultimately sets the price. I’ve learned to pay more attention to the boring operational details than to the loudest headlines.
Possible Paths for Prices in the Near Term
If the current level of disruption persists without major escalation, Brent could continue to consolidate in a relatively high range. A fresh round of successful strikes or another high-profile tanker attack would likely push the market higher again. Conversely, clear evidence that both sides are stepping back could open the door to a deeper correction.
The range of outcomes remains wide. That is precisely why volatility has stayed elevated. Options markets already price a meaningful chance of larger moves in either direction. Cash traders, meanwhile, focus on securing physical barrels while the window remains open.
One personal observation: the longer these twin risks remain active, the more the market begins to treat elevated prices as the new baseline rather than a temporary spike. That psychological shift can be powerful once it takes hold.
The Human Element Behind the Numbers
It is easy to discuss oil prices in purely abstract terms. Behind every disrupted terminal and every threatened tanker sit real people. Workers at the facilities, crews on the ships, and communities that depend on stable energy flows all feel the consequences.
When a terminal catches fire, local authorities must manage both the immediate safety response and the longer economic fallout. When a tanker is attacked, the crew faces genuine danger even if the vessel itself survives. Those human costs rarely appear in futures settlement prices, yet they shape the decisions that keep supply moving or bring it to a halt.
I find it useful to remember that energy markets are ultimately about physical molecules and the people who produce, move, and consume them. The financial layer sits on top of that reality. When the physical layer comes under pressure, the financial layer eventually adjusts.
Why This Episode Feels Different
Previous spikes often centered on a single region or a single type of risk. This time the market is juggling simultaneous pressure on Russian product exports and Middle Eastern crude routes. The geographic separation makes coordinated de-escalation harder.
Another difference is the demonstrated ability of relatively low-cost drones to reach significant targets. That capability changes the calculus for both defense and offense. Facilities that once seemed relatively secure now require heavier protection, which itself carries costs.
In the maritime domain the use of small boats and projectiles against large tankers creates an asymmetric challenge. Traditional naval escorts can deter some threats, yet they cannot eliminate every risk in a crowded waterway.
These structural changes suggest that periods of elevated risk premium may last longer than in earlier cycles. Markets that once expected quick returns to normal may need to adjust their assumptions.
Practical Considerations for Market Participants
For producers the current environment offers higher realized prices but also greater operational uncertainty. For refiners the picture is more mixed. Some benefit from strong product cracks while others face difficulty securing preferred crude grades at predictable costs.
Consumers, whether industrial or retail, eventually feel the impact through higher energy bills or increased costs of goods. The lag between futures prices and pump prices varies by region, yet the direction of travel is rarely in doubt when crude stays elevated for an extended period.
Portfolio managers who treat energy as a tactical allocation must decide how much risk premium they are willing to hold. Those with longer-term mandates may view the current levels as an opportunity to lock in higher cash flows, provided they can manage the associated volatility.
| Market Participant | Primary Concern | Potential Response |
| Producers | Operational continuity | Increase security and storage |
| Refiners | Feedstock availability | Diversify supply sources |
| Traders | Volatility and liquidity | Adjust position sizing |
| Consumers | End-user prices | Seek efficiency gains |
No single strategy fits every participant. The common thread is the need for greater flexibility than many had planned for only a few months ago.
Looking Beyond the Immediate Headlines
It is tempting to treat every new strike or tanker incident as an isolated event. The more useful approach is to view them as part of a longer contest over energy leverage. Both sides understand that reliable energy flows translate into economic and political strength.
As long as that contest continues, the market will keep assigning a risk premium to the barrel. The size of the premium will fluctuate with the intensity of the latest developments, yet the premium itself is unlikely to disappear completely in the near term.
I’ve come to expect that energy markets will remain more event-driven than they were in quieter periods. That does not mean prices will only move higher. It does mean that sudden swings in either direction should no longer surprise anyone who follows the sector closely.
The coming days will bring more data on actual damage, more shipping reports, and almost certainly more political statements. Through all of that noise the core question stays the same: can physical barrels continue to move freely enough to meet demand without further interruption? Until the answer becomes clearer, prices near recent highs look more like a reflection of reality than an over-reaction.
For now the market is doing what it does best under uncertainty. It is waiting, watching, and refusing to give back too much ground. That posture may frustrate those hoping for a quick resolution. It is also the posture that has kept Brent hovering near $109 even after a modest weekend decline.
The next meaningful move will likely arrive when one of the two flashpoints either escalates further or shows genuine signs of cooling. Until then the path of least resistance remains a choppy but elevated trading range. Traders who respect that reality are better positioned than those who insist on forcing a decisive directional call too early.
Energy markets have taught the same lesson many times. When supply faces simultaneous threats in different regions, the adjustment process is rarely neat or rapid. The current episode is simply the latest chapter in that ongoing story.