
Have you noticed how the cheapest ticket on a flight now comes with a catch, while the same carrier quietly teases a roomier seat a few rows up? That tension sits at the center of a surprising shift. The investor who spent decades proving that travelers would pay extra for bags, seats, and almost everything else is now arguing that a modest first-class option belongs on U.S. budget flights. Not a palace in the sky. An option. And that distinction matters more than the headlines suggest.
Why The Ultra Cheap Playbook Is Being Rewritten
For a long stretch, the formula looked almost boring in its reliability. Keep the aircraft dense. Keep the fare low. Charge for anything that is not the seat itself. Grow fast enough that unit costs stay under control. Bill Franke built a career, and a network of carriers, on that idea. He is 89, still chairman at Frontier, still a major shareholder, and still talking about new airline concepts as if they arrive on his desk every month. In my view, that last detail is the tell. People who are done with the industry do not keep scanning for startups.
What changed is not a sudden love of champagne. Costs jumped. Pilot pay reset after the pandemic. Maintenance and day-to-day operating expenses climbed. Fuel has been jumpy. At the same time, a chunk of U.S. demand drifted toward comfort. Larger network carriers copied the unbundled cheap ticket, then pushed premium cabins harder. The discounter’s old monopoly on “no frills, low price” got crowded from both sides.
We are not trying to have a flagship first class. What we are trying to do is give the consumer an option.
– Bill Franke, in conversation about Frontier’s cabin plans
That line is doing a lot of work. It is a concession and a defense at once. Upscale, he says, but still competitive. Roomier seats on an Airbus fleet next year. Satellite Wi-Fi joining the list of extras that used to feel like a luxury reserved for someone else’s airplane. The point is not to become a boutique carrier. The point is to stop leaving money on the table when a passenger would rather pay up than sit in the tightest row.
Price Still Wins, Just Not For Everyone
Franke started flying as a kid because his father worked abroad. He talks about travelers as if they have grown up with him. Consumers are sharper now, he says. They compare. They use tools, including artificial intelligence, that make fare shopping less of a scavenger hunt. Airlines are not fully sure how that changes the booking moment. Fair enough. Nobody is.
Even so, he keeps coming back to two boring words: price and schedule. For plenty of people, the gap between $125 and $200 is not the whole story. For a lot of middle-class and younger flyers, it still is. I have found that this split is easy to miss if you only listen to frequent business travelers. They live in a different market. A spring-break student and a consultant on a same-day turn do not share a utility function, even when they board the same aircraft.
That is why the new cabin plan is an option, not a conversion. The core product can stay lean. A slice of the cabin can sell comfort. If you have ever watched a family debate whether the extra inches are “worth it” at the gate, you already know the product exists in people’s heads. The airline is just putting a price tag on a feeling they already have.
How The Old Rules Got Copied And Then Stretched
There is a bit of irony here, and it is hard not to smile at it. Years ago, Franke was blunt about customers who wanted low fares and free extras. He compared some of that expectation to teenage entitlement. Harsh? Maybe. Accurate about the economics? Often yes. A seat at $49 cannot also include two bags, a prime row, and a hot meal unless someone else is subsidizing the fantasy.
Then the big carriers learned the trick. Basic economy showed up. Fees multiplied. This year, even premium cabins started wearing restrictions that used to live only in the cheap rows. Free seat selection is no longer automatic just because the ticket says first class. The discounter did not lose the argument. The industry absorbed it and applied it upstairs.
Once that happens, a pure ultra-low-cost carrier in a mature market has a branding problem. If the giant next door sells a stripped fare and a plush cabin on the same flight, the specialist has to decide whether density alone is still a personality. Frontier’s answer, at least in the United States, is to keep the low base and add a paid step-up. Allegiant has talked about a first-class row on single-cabin jets. JetBlue is adding a domestic first product. The large groups keep expanding premium real estate. Nobody wants to be the last cabin that looks like 2014.
Spirit’s Collapse Changed The Competitive Map
Franke ran Spirit until 2013, then moved into the Frontier chair later that year. A merger attempt in 2022 failed when shareholders took another cash offer. That other deal later died in court on antitrust grounds. Spirit, left to fight alone, ran out of room and collapsed in May. It was the largest U.S. airline failure in a long time. Frontier became the biggest remaining discounter in the country almost by default.
That is not the same as winning. Frontier has been profitable in only one year since 2019. JetBlue has not posted a profit since that same year. Leadership at Frontier changed in December, with Jimmy Dempsey taking over after nearly a decade under the previous chief. On a late-July earnings call he declined to forecast the next year and still said the path toward lasting profit looks real. Cautious optimism is the grown-up version of a victory lap.
Fares have been climbing industry-wide as carriers try to cover higher costs. August ticket prices were up more than 23 percent from a year earlier in federal data released in mid-September. Higher fares help the P&L. They also test the old promise that the discounter is always the escape hatch when money is tight. If the cheap carrier is no longer cheap enough, the whole identity wobbles.
The U.S. Market Is Mature. Other Markets Are Not.
Here is where Franke sounds least like a convert and most like a portfolio manager. In the United States you have huge incumbents that refresh interiors on a cycle. Competing with that product, he argues, may require a low-cost airline to tweak the model. That does not mean you copy the tweak in Hungary or Peru. Emerging markets can still run the classic machine: high utilization, tight seating, relentless focus on cost per seat.
I think that geographic split is the most useful idea in the whole conversation. Too many industry debates treat “the passenger” as one person. A commuter in Phoenix and a first-time flyer in an expanding secondary city do not want the same bundle. Pretending they do is how carriers end up with cabins that please nobody and cost too much.
- In mature U.S. flying, roomier paid seats can defend share against network brands.
- In faster-growing markets, density and schedule frequency still do most of the work.
- Ancillary fees remain the quiet engine either way.
- Wi-Fi and seat comfort are now table stakes for a slice of domestic demand.
Efficiency does not retire. It just stops being the only story you tell in every geography. That is a more adult version of the ultra-low-cost idea than a full retreat into pillows and amenity kits.
A Career That Still Casts A Long Shadow
Franke came to airlines from law. In the early 1990s Arizona’s governor asked him to help pull America West out of bankruptcy. He became chief executive in 1993. From that Tempe base grew a surprising alumni network. The current chiefs at American and United spent formative years in his orbit. So did other senior operators who still talk about him the way people talk about a tough coach they would not trade.
One former colleague described regular football bets and a rule that fast payment keeps friendships intact. Winnings arrived as foreign cash clipped to a card or coins taped to a page marked paid in full. Another recalled a newspaper profile that Franke claimed ruined his morning coffee. The same executive still called him a mentor, then added the unofficial title: hard-ass mentor. Franke says he did not yell. Memory is a slippery thing in this business.
All of us, our formative years were working for Bill. He should take more credit for that.
Steve Johnson, now a top strategist at American and an Indigo alum from the Spirit years, has compared him to a second father. The story that sticks is summer 2008, when jet fuel spiked above $147 a barrel, well over $200 in today’s money. Spirit was burning cash but held a stack of fuel hedges. Johnson was headed to a plane when Franke called and told him to sell. They did. Roughly $30 million came in. Oil later crashed. The timing, Johnson said, was exactly what the airline needed.
That vignette explains more than the cabin news. The man now warming to first-class rows is the same operator who would rather monetize a hedge than romance a narrative. Premium seats, in that light, are not a midlife style change. They are another instrument.
What “First Class” Actually Means On A Discounter
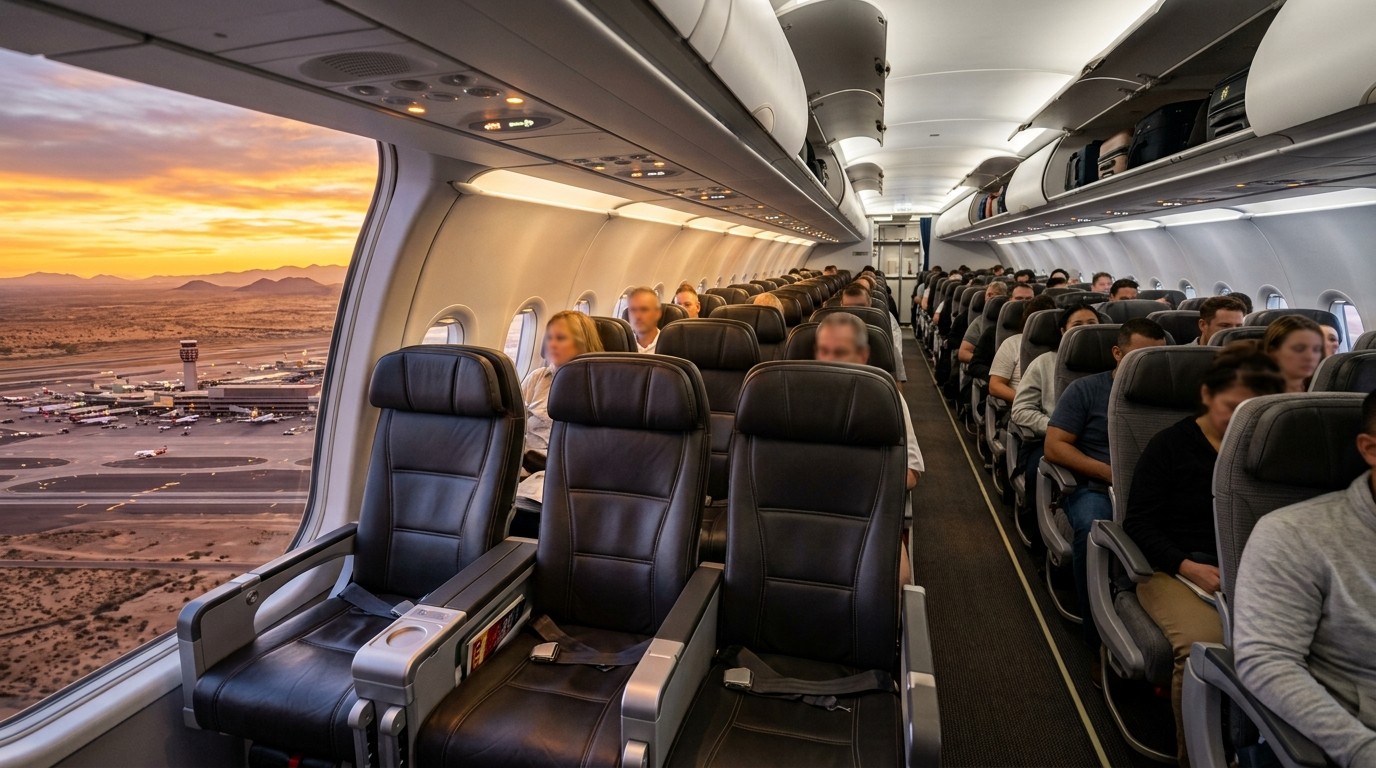
Let’s be plain. A first-class seat on a high-density Airbus flying short and medium U.S. routes will not look like a suite on a flagship long-haul. Wider cushion. More pitch. Maybe a bit of ceremony in boarding. A chance to sell a higher fare without pretending the rest of the jet has changed religion. If you expect slippers and canapés, you will be disappointed. If you expect a seat that does not punish your knees for three hours, you might buy it.
Starlink-style connectivity fits the same logic. Connectivity used to be a differentiator. Now it is closer to a utility, especially for younger travelers who treat a dead connection like a broken tray table. Adding it does not make Frontier a luxury brand. Leaving it off makes the cheap ticket feel older than it is.
| Choice | What The Flyer Gets | What The Airline Protects |
| Base fare | A seat and a schedule | The low headline price |
| Paid extras | Bags, seats, flexibility | Ancillary margin |
| Premium row | Space and a little status | Mix of revenue per departure |
| Connected cabin | Usable Wi-Fi | Perceived modernity |
Notice what is missing from that grid: a promise that everything is included. The model still hates giving things away. It is simply willing to sell a nicer thing. That is a small sentence with large consequences for how investors should think about unit revenue.
Costs, Growth, And The Myth Of Endless Density
The ultra-low-cost story needed two conditions that got harder after 2020. Costs had to stay suppressed. Growth had to stay fast enough to spread those costs. Labor markets tightened. Aircraft availability got messy. Airports and air traffic systems did not magically add capacity because a spreadsheet wanted 15 percent more departures. You can only shrink the seat pitch so far before the product becomes a dare.
Higher fuel after geopolitical shocks did not help. When the cost stack rises, a carrier that lives on thin margins has fewer places to hide. Raising fares works until demand blinks. Cutting capacity works until growth, the other sacred pillar, looks like a broken promise. Adding a premium row is a third move: change the mix instead of only changing the volume.
Is that enough? Nobody should pretend a few extra inches fix a structural cost problem. I have sat through too many cabin-redesign briefings that sounded like strategy and were really furniture. The furniture can still matter if it lets you keep a price-sensitive customer in the back and capture a comfort-sensitive customer up front on the same wave of flying.
Consumers Are Not Spoiled. They Are Segmented.
The old jab about spoiled travelers was half right and half lazy. Some people do want a $79 fare and a free suitcase because that is how marketing trained them. Others will pay for space if you stop making them feel foolish for wanting it. The interesting shift is not moral. It is commercial. Network carriers taught the mass market that “basic” is a product, not an insult. Discounters are now teaching the same market that “a bit more room” can live on a yellow-tail airline without a personality crisis.
Perhaps the most interesting aspect is how little this depends on brand poetry. It depends on whether the extra seat can be sold often enough to justify the lost density. If the row flies empty, you have donated margin to a brochure. If it sells on peak days and sits cold on Tuesdays, you have a scheduling puzzle, not a brand epiphany.
- Keep the base fare visible and simple.
- Price the extra space like an ancillary, not like a new airline.
- Protect turn times so the nicer seat does not slow the machine.
- Use connectivity as a reason to open the wallet, not as a freebie.
- Leave emerging-market fleets denser until local demand says otherwise.
The Mentorship Economy Inside U.S. Aviation
It is easy to treat airline strategy as a set of slides. It is harder to admit how much of the modern U.S. industry still runs on relationships formed in Tempe thirty years ago. People who got yelled at, or who remember not getting yelled at, now run the largest groups. They still take his calls. They still flinch, joke, and pay their football debts.
That human layer explains why this premium-seat news travels farther than a routine product update. When Franke moves, a lot of people who learned cost discipline from him have to decide whether the move is heresy or homework. My read is homework. The discipline stays. The product menu gets one more line.
He says he is far from done. Startup ideas still show up. That restlessness is useful even if most of those ideas never leave a napkin. Markets change. Labor contracts change. Passengers age into different preferences. A model that cannot bend becomes a museum piece, and museums do not cover fuel hedges.
What Travelers Should Watch Next
If you fly the discounters for price, do not assume the cheap seat disappears. The commercial logic still needs that customer. Watch instead for how clearly the step-up is sold. Buried fees create rage. A visible extra-legroom product creates a choice. Rage does not fill a cabin. Choice sometimes does.
Watch load factors in those forward rows after they appear. Watch whether bag fees stay aggressive. Watch whether schedule reliability holds when the cabin mix gets a little more complicated. A pretty seat on a late aircraft is still a late aircraft. Reliability remains the unglamorous feature that makes every other feature usable.
And watch emerging-market affiliates and investments for contrast. If those operations stay dense while U.S. flying gets a few wider chairs, the thesis is coherent. If every market suddenly sprouts the same “premium” language, you are looking at fashion, not segmentation.
A Practical Reading For Anyone Who Cares About The Stocks
This is not investment advice. It is a way to read the story without swallowing the press language whole. A discounter adding first-class seats is trying to raise revenue per departure without pretending cost per seat will fall back to 2015. Success looks like a stable low-fare core, a paid comfort layer that actually sells, and a cost culture that does not go soft because the front row has nicer leather.
Failure looks familiar. Empty premium rows. Slower turns. A brand that confuses “option” with “we are becoming someone else.” Spirit already showed what happens when the model is stressed and the balance sheet has little slack. Frontier does not need to repeat the ending to respect the warning.
Simple filter for the next four quarters:
  Does the cheap ticket still exist in volume?
  Do paid extras keep growing?
  Do the new seats book or sit dark?
  Do costs per available seat stay honest?
If those four answers stay clean, the warmer tone toward comfort is just product design. If they smear, the industry will call it a strategy shift and mean a problem.
The Quiet Point Everyone Skips
Airlines love talking about what passengers “deserve.” That word is mush. Passengers deserve a ticket that matches the contract and an aircraft that arrives. Everything else is a negotiation. Franke’s newer stance is simply a new price list for that negotiation in one market. Keep the list short in places where income and alternatives look different. Lengthen it where rivals already sell theater in the front cabin.
I keep coming back to the model-airplane office in Scottsdale. A room full of tiny jets is a funny place to announce that real jets need bigger chairs. Then again, people who live among models tend to think in variants. Same fuselage. Different interior. Different mission. That is a healthier metaphor than rebirth.
So no, the budget-airline king did not suddenly fall in love with luxury. He noticed that in the United States the fight is no longer only about who can cram the most seats into a tube. It is also about who can sell two or three versions of the same departure without wrecking the cost base. That is a narrower, tougher, more interesting problem. It is also the one that will decide whether the remaining U.S. discounter looks like a survivor or a footnote.
The rest of us will vote the only way passengers ever vote. We will click the fare that feels least foolish on the morning we have to be somewhere. Sometimes that fare will be the old tight seat. Sometimes it will be the extra inches. The airlines that make both clicks feel intentional, rather than accidental, will be the ones still talking about growth when the next cost spike arrives. That, more than any cabin rendering, is the story underneath the story.