


I’ve been watching the numbers roll in for months now, and something about this latest forecast feels different. China’s exports are expected to climb by a solid 25.5 percent in September compared with the same period last year. That’s not just another strong reading. It’s a clear signal that global appetite for certain Chinese goods remains surprisingly robust even while the country’s own consumers stay cautious. The figure edges higher than August’s result, and the timing could hardly be more interesting.
What the September Forecast Really Tells Us
According to a recent survey of economists, imports are projected to ease a bit to 24.5 percent year-on-year growth, down from the previous month’s 28.2 percent. Both sides of the trade ledger have already posted their strongest advances in five years earlier in 2026. Yet the story behind these percentages is far more layered than a simple rebound.
Global demand for components that power artificial intelligence data centers has become one of the most powerful drivers. Think specialized servers, high-end chips, and the supporting hardware that keeps large language models running. At the same time, a modest easing of tensions with the United States, still China’s single largest trading partner, has removed some of the earlier uncertainty that weighed on orders.
In my view, the combination is almost textbook. When external demand surges and political noise quiets even slightly, Chinese factories respond with remarkable speed. The result is another month of double-digit export growth that few would have predicted at the start of the year.
AI Hardware Keeps Shipping Lines Busy
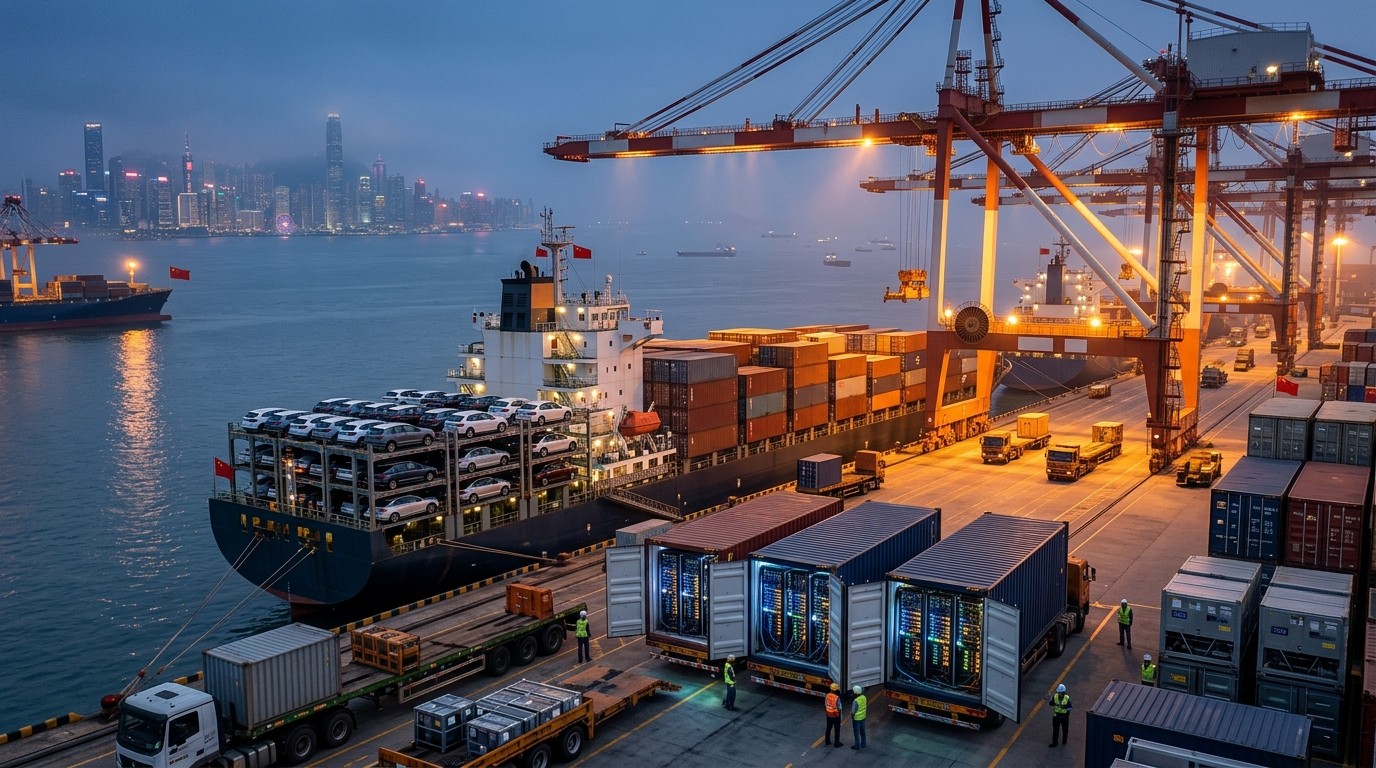
Walk through any major Chinese port these days and the evidence is hard to miss. Specialized vehicle racks loaded with new cars sit ready for loading, but the real volume growth sits in the high-tech crates. AI-related parts have become a quiet powerhouse. Data centers around the world need more capacity, and Chinese manufacturers have stepped up to fill that gap with surprising consistency.
Prices for some of those core products have also risen, which helps explain why import figures stay elevated even as growth moderates slightly. The same factories that export finished servers often import the advanced materials and intermediate goods required to build them. It’s a virtuous circle for the moment, though one that remains vulnerable to any sudden shift in global technology spending.
I’ve spoken with several logistics managers who describe the current pace as “busy but manageable.” Containers move, ships leave on schedule, and the order books for next quarter still look healthy. That doesn’t mean everything is smooth. Domestic demand inside China continues to lag, which leaves exporters more dependent on overseas buyers than many policymakers would prefer.
Trade Tensions Ease, But Scrutiny Remains High
Last month the United States and China announced plans to roll back tariffs on roughly thirty billion dollars of goods in each direction and to extend a broader trade truce through January. The move was modest in scale yet symbolically important. It reduced the risk of sudden new barriers just as Chinese exporters were ramping up shipments of AI components and electric vehicles.
Across the Atlantic the picture looks more complicated. The European Union recently secured an agreement under which China will halve its exports of hybrid-powered cars to the bloc. High-level talks in Beijing produced that concession after months of concern over market share and local industry pressure. European policymakers have grown increasingly vocal about the economic impact of China’s export surge, especially in sectors where domestic producers feel squeezed.
When one of the world’s largest manufacturing bases keeps expanding shipments while its home market stays soft, trading partners inevitably start asking harder questions about long-term balance.
That scrutiny is unlikely to disappear anytime soon. Governments from Asia to Europe are watching Chinese trade data more closely than ever. Some are considering targeted measures, others are simply accelerating their own industrial policies. The September numbers, if they match the forecast, will only intensify those conversations.
Domestic Demand Still the Weak Link
Here’s the part that keeps many analysts up at night. China’s second-largest economy status comes with an uncomfortable reality: household consumption and private investment have struggled to regain consistent momentum. Factories can keep running at high capacity as long as foreign orders arrive, but that model carries risks. Any sharp slowdown in global growth or a renewed trade dispute could leave those same factories with excess inventory and thinner margins.
I’ve found that the gap between export strength and domestic softness creates a kind of policy tension. Authorities want to support manufacturing employment and maintain global market share, yet they also need stronger local demand to make growth more sustainable. Stimulus measures have helped at the margin, but consumer confidence remains fragile. Young people worry about jobs, property values have cooled, and many households prefer to save rather than spend.
Perhaps the most interesting aspect is how AI-related demand has temporarily papered over some of those cracks. Higher prices for key components boost import values and give exporters better revenue. Yet that support is concentrated in a relatively narrow set of industries. Broader manufacturing still faces uneven conditions.
Cars on the Move and What They Signal
Recent images from the Taicang Port area of Suzhou show rows of Chinese-made cars lined up in specialized racks, waiting to be loaded onto ships. The visual is striking. Electric and hybrid vehicles have become one of the fastest-growing export categories in recent years. Chinese brands have gained market share across Southeast Asia, Latin America, and parts of Europe, often competing aggressively on price and technology features.
The European decision to limit hybrid car shipments illustrates the political sensitivity that now surrounds these products. Local manufacturers argue that rapid Chinese expansion threatens jobs and investment plans. Chinese producers counter that they simply deliver better value and more advanced features at competitive prices. Both sides have valid points, which is why the talks in Beijing produced a compromise rather than a full confrontation.
In practical terms, the agreement means Chinese exporters will need to adjust volumes and perhaps shift more production to local joint ventures or other markets. That adjustment will take time, and the September data may still capture some of the earlier momentum before the new limits fully kick in.
How the Numbers Fit Into the Bigger Picture
Looking back across 2026, both exports and imports posted their strongest growth rates in half a decade during the earlier months. The rebound was broad-based at first, then increasingly concentrated in technology-related goods. Stabilization of relations with the United States removed one major source of volatility. At the same time, rising prices for core products helped keep import values elevated even as volumes fluctuated.
Global demand for AI infrastructure shows little sign of slowing. Companies continue to invest heavily in data centers, and Chinese suppliers remain competitive on cost and delivery speed. That structural tailwind could support export figures for several more quarters. The risk, of course, is that any sudden pullback in technology capital spending would hit Chinese shipments harder than the broader numbers currently suggest.
- AI-related components have become a primary growth engine for Chinese exports
- Trade truce extensions with the United States reduce near-term uncertainty
- European limits on hybrid cars introduce new constraints on one high-profile category
- Domestic demand weakness leaves the economy more exposed to external shifts
- Import growth remains solid but is moderating from recent peaks
These points capture the essence of the current moment. Strong external demand meets cautious domestic conditions, while policymakers on all sides try to manage the resulting imbalances without triggering broader disruptions.
What Investors and Businesses Should Watch Next
The official data release is expected this week, and most observers expect the numbers to come in close to the 25.5 percent export forecast. Any meaningful surprise, either higher or lower, would move markets quickly. Beyond the headline figures, the details matter more. Breakdowns by product category will reveal how much of the growth still comes from AI-related goods versus traditional manufactured items. Geographic splits will show whether demand remains broad or has narrowed to a few key markets.
I’ve learned over the years that trade data often contains early clues about broader economic shifts. A sustained period of double-digit export growth can support industrial production and employment, yet it also raises the likelihood of further trade measures from partners who feel the pressure. Businesses that rely on Chinese supply chains need to monitor both the volume trends and the political responses carefully.
For companies selling into China, the import moderation is worth noting. Growth is still strong in absolute terms, but the slowdown from August’s pace suggests some cooling in certain categories. Price effects have helped keep the values elevated, so volume trends may tell a slightly different story once the full data arrives.
The Longer-Term Balance Question
China’s ability to keep expanding exports while domestic demand lags creates a structural imbalance that cannot last indefinitely. Either local consumption and investment need to strengthen, or external partners will continue to push back with tariffs, quotas, or other barriers. The recent agreements with the United States and the European Union represent attempts to manage that tension rather than resolve it completely.
Some observers argue that the AI boom simply accelerates an existing trend. China has spent years building capacity in advanced manufacturing, and global technology needs have arrived at the perfect moment. Others worry that over-reliance on a few high-growth sectors leaves the broader economy vulnerable. Both perspectives contain truth. The real test will come when the current technology investment cycle matures or when another external shock hits.
In the meantime, the September forecast offers a snapshot of an economy that remains deeply integrated into global supply chains. Factories keep producing, ships keep sailing, and buyers around the world keep placing orders for the goods they need. The question is how long that pattern can continue without deeper adjustments at home and abroad.
Practical Implications for Supply Chains
Companies that source components or finished products from China are watching these numbers closely. Strong export growth usually means tighter capacity and potentially longer lead times in the busiest sectors. AI-related hardware is already seeing elevated demand, which can push prices higher and strain logistics networks. At the same time, the modest easing of tariff tensions reduces one source of cost uncertainty for goods heading to the United States.
European buyers of Chinese hybrid vehicles will need to plan around the new volume limits. Some may accelerate orders before restrictions tighten further, while others explore alternative suppliers or local production options. The adjustment process will take months, and the September shipment data may still reflect the pre-agreement pace.
I’ve noticed that many firms are already diversifying their sourcing strategies, adding capacity in Southeast Asia or other regions as a hedge. The latest Chinese trade figures do not change that long-term direction, but they do underscore how competitive Chinese manufacturers remain in key categories. Diversification is prudent, yet complete decoupling remains expensive and slow.
Reading Between the Lines of the Forecast
Economists polled ahead of the data release expect export growth of 25.5 percent and import growth of 24.5 percent. Those are still impressive rates by historical standards, especially after the strong performance earlier in the year. The modest pickup in exports and the slight cooling in imports together paint a picture of continued external strength paired with some normalization on the import side.
What stands out to me is the resilience. Despite years of discussion about supply-chain shifts and geopolitical risk, Chinese exporters continue to find buyers. The AI demand surge has clearly helped, but so has the ability of Chinese firms to adapt product offerings and pricing strategies quickly. That flexibility remains a competitive advantage that is easy to underestimate.
At the same time, the persistent weakness in domestic demand serves as a reminder that export success alone cannot deliver the balanced growth that policymakers seek. Stimulus efforts continue, yet household confidence recovers slowly. Until that changes, the economy will keep leaning on external demand more heavily than is ideal.
Looking Ahead to the Rest of the Year
If the September data matches the forecast, attention will quickly turn to the final quarter. Seasonal patterns, holiday demand in Western markets, and the trajectory of technology spending will all influence the numbers. The extended trade truce with the United States buys time through January, which reduces the risk of sudden new barriers in the near term. European restrictions on hybrid cars will begin to show more clearly in later months.
Global growth prospects remain a key variable. Softer demand in major economies could eventually slow Chinese shipments, while any acceleration would provide further support. The AI infrastructure build-out looks set to continue, but the pace could vary depending on corporate capital expenditure plans and interest-rate environments around the world.
For now, the story is one of surprising strength. Double-digit export growth in September would mark another chapter in a year that has already surprised many observers. The underlying drivers—AI demand, partial trade de-escalation, and competitive manufacturing—remain in place. Whether they can continue to offset domestic softness is the larger question that will shape the outlook for 2027 and beyond.
The data release this week will give us a clearer view. Until then, the forecast itself offers enough insight to keep businesses, investors, and policymakers focused on the same central theme: China’s factories are still busy, the world is still buying, and the balance between external strength and internal caution remains delicate.
That balance will determine not only the next set of trade numbers but also the longer path of the world’s second-largest economy. For anyone watching global markets, the September figures are more than a monthly update. They are a window into how trade, technology, and geopolitics continue to intersect in real time.



