
Have you ever stopped to wonder what happens when the country that builds most of the world’s solar panels suddenly decides those advanced blueprints are too sensitive to share? That is exactly the situation unfolding right now. Beijing has quietly tightened its grip on a whole set of solar technologies, and the ripple effects could reach far beyond factory floors in Asia. In my view, this latest move feels less like routine regulation and more like a calculated reminder of who still holds the technological high ground in the renewable energy race.
China’s Latest Export Controls On Solar Technology
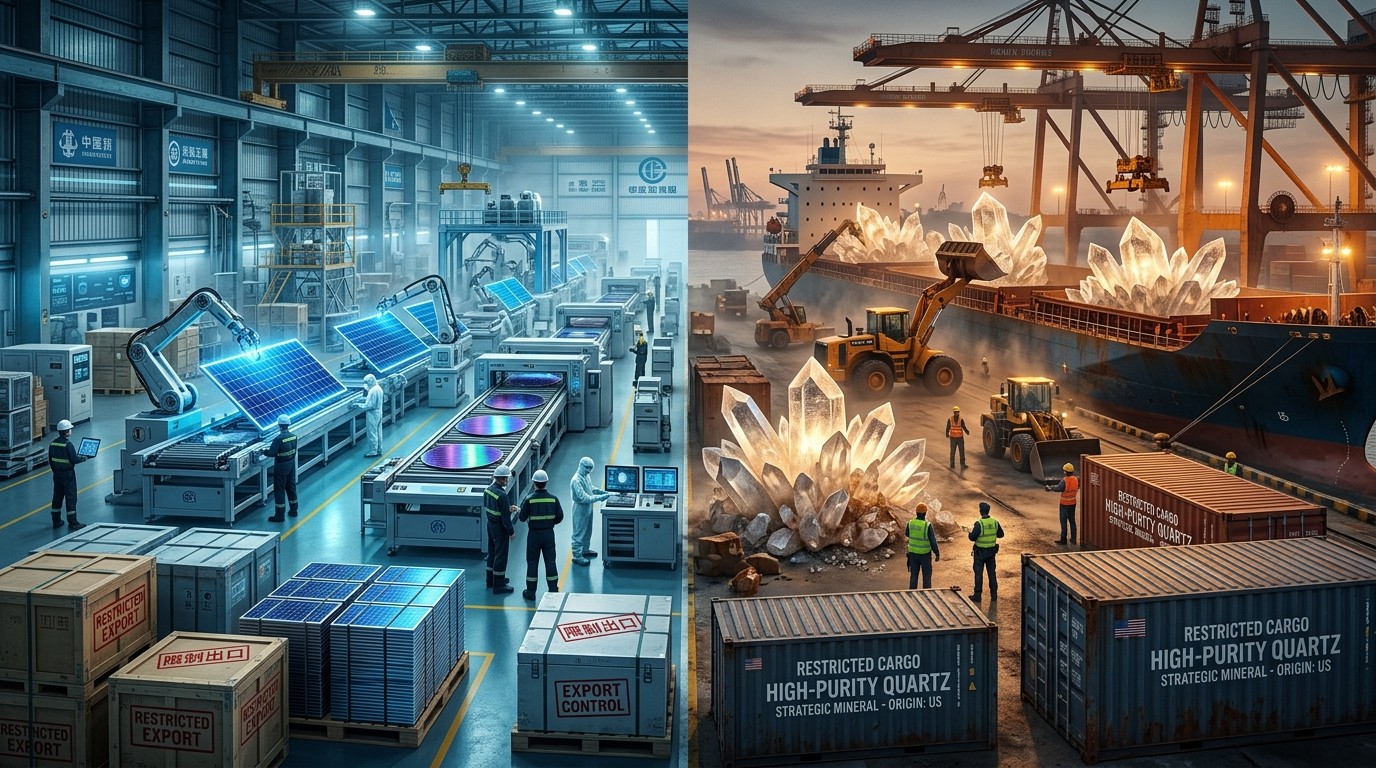
Earlier this week the Chinese Ministry of Commerce released a statement that sent a clear signal across global markets. Twelve solar-related technologies and pieces of core equipment were added to the export-control list. The official reason given was national security. Officials pointed out that solar technology is increasingly used in aerospace, national defense, unmanned systems, and high-security infrastructure. Because of that expanding role, they argued, the risks of unrestricted exports have grown too large to ignore.
The new rules form part of a wider revision that covers roughly forty technologies in total, including areas such as artificial intelligence and biopharmaceuticals. For the solar sector the restrictions hit especially hard. Production technology for perovskite solar cells and advanced modules is now off-limits for export. Certain techniques used to manufacture polysilicon, the key raw material for most conventional panels, also fall under tighter supervision. These are not fringe products. They represent some of the highest-efficiency pathways currently available and hold real promise for future applications like space-based solar power.
I’ve found that announcements like this rarely appear in isolation. They tend to arrive after months of quiet assessment and at moments when geopolitical temperatures are already elevated. The recent high-level meeting between American and Chinese leaders in Washington apparently did little to cool the underlying trade frictions. Instead of easing pressure, Beijing appears to have chosen to protect its technological edge while the United States and India push harder to build their own domestic solar manufacturing capacity.
Why Perovskite And Polysilicon Matter So Much
Let’s talk about the technologies themselves for a moment. Perovskite solar cells have generated genuine excitement among researchers because they can achieve higher conversion efficiencies than many traditional silicon panels while potentially costing less to produce. They also open doors to lightweight, flexible applications that conventional rigid panels simply cannot match. Restricting the know-how needed to manufacture these cells at scale is therefore a meaningful barrier for any country hoping to catch up quickly.
Polysilicon sits at the foundation of the entire industry. Without high-quality polysilicon, most of the panels installed on rooftops and in utility-scale farms would not exist. China has spent years building an overwhelming advantage in this material. By placing controls on the specialized production technologies, Beijing makes it harder for outsiders to replicate that advantage at home. Analysts who track the sector note that manufacturers in the United States and India still rely on Chinese equipment, materials, and process knowledge for critical steps. The new controls could slow diversification efforts just when those efforts were gaining momentum.
Perhaps the most interesting aspect is how openly the Chinese statement links solar technology to national security domains. Once a technology moves from purely commercial status into dual-use territory, governments tend to treat it very differently. Export licenses become harder to obtain. Technology transfer agreements face extra scrutiny. In practical terms, the world just received a reminder that the energy transition is not only about climate goals. It is also about strategic industrial power.
The Broader Pattern Of Critical Material Controls
This solar announcement does not stand alone. Over the past couple of years Beijing has already placed export controls on several critical materials that matter to advanced manufacturing. Tungsten, germanium, gallium, and antimony have all faced tighter restrictions. Each of those materials plays a role in electronics, defense systems, or energy technologies. The cumulative effect is a steady tightening of the supply chains that the rest of the world has grown accustomed to treating as reliable.
In my experience watching these developments, the pattern is consistent. When a country perceives that others are trying to reduce dependence on its products, it often responds by making that dependence more expensive or more complicated to unwind. The solar controls fit neatly into that approach. They preserve China’s technological lead while raising the cost and timeline for competitors who want to build independent capacity.
Some observers argue that such measures could eventually backfire by accelerating the very diversification they aim to slow. Others counter that the short-to-medium term disruption is large enough to matter. Either way, the move reinforces ongoing concerns about concentration risk in critical materials and clean-energy technologies. Companies and governments that had hoped for smooth supply chains now face fresh uncertainty.
America’s Quiet Advantage In High-Purity Quartz
Here is where the story takes an interesting turn. While China dominates many stages of solar manufacturing, it still depends on a key upstream input that the United States controls in significant quantity: high-purity quartz. This specialized material is essential for producing the crucibles and other equipment used in polysilicon refining and crystal growth. Without consistent access to high-purity quartz of the right grade, the entire production chain faces bottlenecks.
Trade officials in the current American administration have a potential lever sitting right in front of them. They could restrict exports of US high-purity quartz to China through export controls and licensing requirements. Such a step would not be simple, and it would carry its own economic costs. Yet the leverage exists. China’s solar dominance remains vulnerable on this specific point, and that vulnerability has not gone unnoticed in Washington.
I’ve spoken with people who follow the materials markets closely, and they tend to agree on one thing. High-purity quartz is not a commodity that can be replaced overnight. Deposits of the necessary quality are limited. Processing the material to the exacting standards required for solar applications takes specialized knowledge and infrastructure. The United States holds a meaningful share of that capacity. Using it as a bargaining chip would mark a clear escalation, but it would also demonstrate that leverage in the energy sector runs in more than one direction.
How The Trump Administration Might Respond
The question many market participants are asking is straightforward: will the administration choose to play the quartz card? At this stage no formal decision has been announced. Still, the logic is easy to follow. If Beijing is prepared to restrict advanced solar technologies on national-security grounds, Washington could respond in kind with controls on a critical input material. The symmetry is obvious even if the practical effects would differ.
Any such move would need careful calibration. American companies that supply high-purity quartz would face reduced export volumes. Downstream users outside China might also feel secondary effects if global prices rise or availability tightens. At the same time, the signal sent to Beijing would be unambiguous. Supply-chain interdependence cuts both ways. Restricting technology flows invites scrutiny of the materials that make those technologies possible.
In my own assessment, the administration is likely weighing several factors right now. Domestic political pressure to rebuild American manufacturing capacity remains strong. National-security arguments around energy independence carry weight. Yet pure economic retaliation always risks broader market disruption. The decision will probably hinge on how much further Beijing pushes and whether quieter diplomatic channels produce any flexibility on the new export rules.
Implications For Global Solar Manufacturing
What does all of this mean for companies trying to expand solar production outside China? The short answer is greater complexity and longer timelines. Manufacturers in the United States and India have already been working to localize more of the supply chain. The latest Chinese controls make that process more difficult by limiting access to certain process technologies and specialized equipment. Firms that previously counted on importing proven Chinese know-how now face the harder task of developing alternatives from scratch or sourcing them from other countries that may not yet possess equivalent capability.
Cost pressures are likely to increase as well. Building new capacity without the benefit of mature Chinese process technology usually means higher capital expenditure and a steeper learning curve. Some projects may face delays. Others may proceed with lower efficiency or higher production costs in the early years. Over time the industry can adapt, but the transition period could prove bumpy.
There is also a broader strategic question. Governments that have set ambitious renewable-energy targets now confront the reality that technology access is not guaranteed. Energy security and manufacturing security are becoming more tightly linked. Countries that want large domestic solar industries may need to invest more heavily in research, specialized materials, and process innovation rather than relying on technology transfer from the current market leader.
- Higher barriers to technology transfer slow capacity expansion outside China
- Polysilicon and perovskite process knowledge becomes harder to obtain
- Supply-chain diversification efforts face longer timelines and higher costs
- National-security framing elevates solar technology into strategic domain
- Potential for reciprocal controls on high-purity quartz raises uncertainty
The Energy Transition Meets Geopolitical Reality
For years the dominant narrative around solar power focused on falling costs and rapid deployment. That story remains important. Yet the latest export controls underline a parallel truth: the energy transition is unfolding inside a contested geopolitical environment. Critical technologies and materials are no longer treated as purely commercial goods. They are viewed through the lens of national advantage and strategic vulnerability.
This shift has practical consequences for investors, policymakers, and corporate planners. Assumptions about frictionless global supply chains look less reliable. Scenario planning now has to include the possibility of further export restrictions, licensing delays, and reciprocal measures. Companies that build resilience through diversified sourcing and domestic process capability will be better positioned than those that continue to rely on a single dominant supplier for critical know-how.
I keep coming back to one observation. The world still needs massive amounts of new solar capacity if climate goals are to remain within reach. At the same time, no major economy wants to leave itself exposed on technologies that matter for both energy and security. Balancing those two pressures will shape industrial policy for years to come. The Chinese announcement and the potential American response are early chapters in what is likely to be a longer story.
What High-Purity Quartz Really Represents
It is worth pausing on the material itself. High-purity quartz is not glamorous. Most people never hear of it. Yet without it the production of high-quality silicon crystals becomes far more difficult. The quartz is processed into crucibles that can withstand the extreme temperatures and purity requirements of the crystal-growing process. Contamination at that stage ruins the material. Consistency and quality are therefore non-negotiable.
The United States possesses significant deposits and processing capacity for the grades required by the solar industry. That position creates a rare point of leverage in a supply chain that otherwise tilts heavily toward China. Whether policymakers choose to use that leverage remains an open question. The mere existence of the option, however, changes the negotiation dynamics. Beijing knows the vulnerability exists. Washington knows it too. That mutual awareness alone can influence behavior even before any formal controls are announced.
Some industry voices caution against overplaying the card. They note that China has been working for years to reduce reliance on foreign inputs wherever possible. Alternative sources of quartz or alternative process routes may eventually reduce the American advantage. Still, building those alternatives takes time and capital. In the near term the leverage is real.
Possible Paths Forward For Policymakers
Several paths are available. One is quiet diplomacy aimed at clarifying the scope of the new Chinese controls and seeking exemptions or licenses for non-sensitive commercial applications. Another is the reciprocal route: matching technology restrictions with material restrictions. A third approach focuses less on immediate retaliation and more on accelerating domestic investment in the full solar value chain, from materials through advanced cell architectures.
Each path carries trade-offs. Diplomacy may produce limited results if Beijing views the controls as essential to national security. Reciprocal measures risk further escalation and market volatility. Pure domestic investment takes years to bear fruit and requires sustained political and financial commitment. In practice a combination of all three is the most likely outcome. Governments rarely rely on a single tool when strategic industries are involved.
From my perspective the healthiest long-term response is the one that reduces overall concentration risk. That means supporting research into alternative materials and processes, encouraging multiple geographic sources of critical inputs, and building manufacturing capacity that can operate without constant technology transfers from any single country. The current episode simply makes the urgency of that work more visible.
Market Reactions And Investor Considerations
Markets have already begun to digest the news. Shares of companies heavily exposed to Chinese solar equipment or technology licensing have faced pressure in some sessions. Firms positioned to benefit from Western localization efforts have drawn more attention. The reaction remains measured so far, in part because the full practical impact of the controls will take months to become clear. Licensing procedures, enforcement details, and possible exceptions all still need to be worked out.
Investors watching the sector should keep several variables in mind. First, the speed and strictness of Chinese implementation. Second, any signals from Washington about potential quartz-related measures. Third, the pace at which non-Chinese manufacturers can develop independent process capability. Fourth, broader trade and tariff developments that could either amplify or dampen the effect of technology controls.
Volatility is likely to remain elevated while these questions stay unresolved. At the same time, the underlying demand for solar capacity continues to grow. The tension between strong end-market demand and constrained technology access creates both risks and opportunities. Companies that can navigate the new constraints successfully may emerge with stronger competitive positions.
The national security risks that may be caused by the export of solar technology have been constantly rising. It is necessary to implement timely and appropriate supervision.
That official language captures the tone of the moment. Governments are increasingly willing to prioritize security and technological autonomy over pure commercial openness. Whether one views that shift as necessary realism or unfortunate fragmentation, it is becoming a defining feature of the clean-energy landscape.
Looking Further Ahead
Five or ten years from now the solar industry may look quite different. Multiple regions could possess meaningful manufacturing capacity across more stages of the value chain. Technology leadership might be more evenly distributed. Or the current concentration could persist if alternative pathways prove too slow or too expensive to scale. The decisions taken in the next couple of years will influence which of those futures materializes.
High-purity quartz is only one piece of a much larger puzzle. Similar chokepoints exist in other materials and process steps. The broader lesson is that supply-chain resilience requires constant attention. Relying on a single dominant supplier for critical technologies carries risks that become visible only when geopolitical tensions rise. The latest Chinese controls have made those risks harder to ignore.
I remain cautiously optimistic that the industry will adapt. Innovation has a way of finding work-arounds when the commercial and political incentives are strong enough. New cell architectures, alternative materials, and more efficient processes are already under development in laboratories around the world. The challenge is turning laboratory progress into large-scale manufacturing capability under tighter technology-transfer constraints.
In the meantime the immediate story remains one of strategic positioning. Beijing has chosen to protect advanced solar know-how. Washington holds a potential counter in high-purity quartz. How each side plays its cards will shape costs, timelines, and competitive dynamics across the global solar market for years to come. For anyone involved in energy, manufacturing, or trade policy, this is a development worth watching closely.
The coming months will reveal whether the new controls stay narrowly focused or expand further. They will also show whether the United States decides to test the quartz lever or pursue other forms of pressure. Either way, the era of assuming frictionless access to the most advanced solar technologies appears to be ending. What replaces it will depend on policy choices, industrial investment, and the willingness of multiple countries to build genuine technological independence. That process will not be quick or painless, but it may ultimately produce a more resilient global energy system. For now, the tension is real and the stakes are rising.