
Have you watched a price tag on a new family car in Europe lately and felt that quiet sting? I have. The number looks lower than it should, until you notice who built the thing. Cheap Chinese cars are no longer a rumor at the edge of the lot. They are sitting in the middle of it, polished, warrantied, and priced to make a local badge look stubborn.
What Record Market Share Really Means On The Ground
In August, Chinese brands took nearly twelve percent of new-car sales across Europe. That is not a rounding error. That is a foothold. Hybrids did most of the heavy lifting. About one in four cars sold that month carried some form of hybrid power. Plug-in hybrids ran even hotter, close to one in three in that slice of the mix. Electric and hybrid volume jumped twenty-seven percent, which more than covered the slump in pure combustion models and still left the overall market up about four and a half percent.
I’ve found that market-share numbers sound abstract until you stand in a showroom. A salesperson starts with a domestic compact, then quietly slides a brochure for an imported hybrid across the desk. The monthly payment is kinder. The equipment list is longer. The buyer who walked in loyal walks out calculating.
Why Hybrids Became The Perfect Wedge
Extra duties aimed at imported battery-electric models left a gap. Hybrids walk through that gap. They still look green enough for shoppers who worry about city stickers and future bans. They still feel familiar to drivers who do not want range anxiety on a winter motorway. On an energy-strained continent, that combination is almost unfair.
Perhaps the most interesting aspect is how cleanly the product mix maps onto policy. Rules designed to punish one powertrain invited another. Brands that already scale batteries, motors, and electronics at home can retune a hybrid for Europe faster than a traditional maker can redesign a whole plant. Speed is the real product.
When regulation taxes one door and leaves the next one unlocked, capital walks through the unlocked door. Shoppers follow the price.
That is not a moral judgment. It is how trade works when incentives are lopsided. In my experience, executives talk about brand heritage until the invoice hits purchasing. Then heritage becomes a line item.
Domestic Brands Are Not Imagining The Squeeze
Germany’s auto complex has been in a long, ugly grind. One major group recently cut its operating-margin outlook after writing down a sports-car stake and facing softer demand in China, of all places. Layoffs and line slowdowns are no longer whispers. They are calendar items.
In Italy, a historic plant planned to pause electric and hybrid city-car output for the last two weeks of October. Annual volume could land near sixty thousand units against an earlier hope of about one hundred thousand. That is not a blip. That is a factory breathing differently.
- Margin guidance is being revised downward at household names.
- Production calendars now include idle weeks that used to be unthinkable.
- Dealer lots mix more imported badges beside the old hometown metal.
- Workers hear about “flexibility” and translate it as fewer shifts.
None of this means European engineering suddenly forgot how to build a car. It means cost structures, energy bills, and compliance stacks piled up while a rival arrived with a simpler offer: similar tech, lower sticker, faster refresh cycle.
The Chart That Makes Boardrooms Quiet
Bank research circulated among clients has been drawing a steep line for Chinese penetration inside Europe. You do not need the slide deck to feel the slope. Twelve percent in a single month, with hybrids leading, is the kind of print that changes next year’s budget meeting. Procurement teams start asking whether steel, chips, and software should be dual-sourced. Politicians start asking whether “open market” still sounds like a virtue.
I’ve sat through enough of those meetings, in spirit if not in the room, to know the sequence. First comes denial dressed as quality talk. Then comes a special edition with extra speakers. Then comes a plea for tariffs that somehow will not raise prices for voters. It is a familiar play.
Energy Costs, Duties, And The Odd Shape Of Competition
Europe did not lose this fight in a single quarter. High industrial power prices made every weld and every paint booth more expensive. Carbon rules added paperwork and capital. Meanwhile, Chinese groups built scale in a home market that rewards volume first and polish second. They learned batteries the hard way. They learned software because their buyers live on phones. Then they exported the result.
Duties on imported electrics were supposed to level the field. They leveled one strip of it. Hybrids became the workaround, and shoppers treated the workaround as a feature. Who can blame them? A family that needs a car next month does not wait for a five-year industrial strategy.
Germany is now floating economic-security ideas that could stretch tariffs toward those hybrids. That debate will be loud. Protect the plants, and buyers pay more. Leave the door open, and more lines go quiet. There is no tidy slogan that covers both outcomes.
Political Weather Around The Factory Gate
Analysts have warned that an eighteen-month election stretch could turn this into a campaign issue. Shifts already visible in recent German voting suggest voters are impatient with lectures about transition timelines while shift patterns shrink. I do not pretend that every ballot is about cars. I do think cars are a visible proxy for control. People see who still makes things nearby.
Call it populism if you like. Call it self-interest if you are being honest. A town that lived on transmissions does not care that a spreadsheet says global allocation is efficient. The spreadsheet does not coach the local football side.
Industrial identity is not a branding exercise. It is payroll, apprenticeships, and the quiet pride of a badge that used to mean the region.
Leaders who spent years praising open supply chains now discover those chains have a preferred direction. Components still flow. Finished cars flow faster. The finished car is what voters photograph in the supermarket parking lot.
Wartime Readiness Is The Uncomfortable Sidebar
There is a harder point that rarely fits a sales brochure. Civilian auto plants are, in a pinch, convertible capacity. Tooling, skilled labor, and supplier parks can be redirected when governments decide they need different metal. The United States has been talking more openly about that conversion path. Europe looks thinner on that score while its car base thins out.
This is not a call to militarize every assembly hall. It is a reminder that industrial depth is dual-use whether planners admit it or not. If you hollow the civilian base, you do not get a secret second base in a drawer. You get a speech.
In my view, that is the part of the story that should keep defense ministries awake even if trade ministries stay polite. You cannot requisition a capability you allowed to migrate.
How The Sales Mix Shifted In Plain Sight
Combustion-only models slipped. Electrified models rose. That headline is old. The twist is who captured the rise. Chinese groups did not need to win every luxury buyer. They needed volume in the bands where households actually shop: small crossovers, compact hatchbacks, and midsize hybrids with a long options list at a short price.
| Segment signal | What buyers notice | Pressure on locals |
| Hybrids | Lower running anxiety, friendlier monthly cost | High |
| Plug-in hybrids | Official green credentials without full charging dependence | High |
| Pure electrics | Duties raise the imported sticker, still competitive in places | Medium-High |
| Combustion only | Familiar, but volume is drifting | Medium |
Look at that table twice. The heat sits where policy tried to be clever. The heat does not sit where heritage speeches are given.
Scale, Software, And The Unromantic Cost Stack
A modern car is a rolling computer with tires. The groups that treat software as a core product iterate faster. Over-the-air updates, cabin screens, driver aids: none of this is magic. It is headcount and iteration speed. When your home market buys millions of similar platforms, you amortize the code. When your home market is fragmented across languages, unions, and legacy platforms, you amortize speeches.
Batteries follow the same logic. Cell cost falls with volume. Pack design improves with crashes you would rather not advertise. Europe has talent. It has been slower to accept that talent needs brutal scale, not another pilot plant with a ribbon.
- Win volume at home until unit costs collapse.
- Export a good-enough hybrid that dodges the latest duty design.
- Spend on dealer networks only after the price has already done the talking.
- Refresh the fascia every year so last season looks dated on purpose.
That sequence is blunt. It works. Local brands can copy pieces of it. Copying the whole stack means arguing with their own cost history.
What Shoppers Actually Optimize
People pretend they buy on patriotism. Receipts say they buy on payment, warranty, and whether the kids’ seats click in without a fight. A five-year warranty on a cheaper hybrid beats a speech about a founding year stamped on a grille. I say that as someone who still likes a well-made European interior. Taste is not a strategy.
Dealers know this. They will sell what turns. If the imported hybrid turns, the floorplan follows. If the floorplan follows, the used-car values two years later will tell you whether the experiment stuck. Watch residuals. They are the unfiltered review.
Policy Choices That Do Not Come Free
Tariffs on hybrids would slow the surge. They would also raise prices for households already paying more for energy and food. Subsidies for local plants would please unions and scare finance ministries. Local-content rules would invite retaliation in a market where European groups still need to sell abroad, including in China, where demand has already softened for some of them. Every lever yanks another wire.
I’ve found that the honest brief is short. You can protect capacity or you can protect consumer prices. You can lecture about climate timelines or you can admit that the cheapest compliant car will win the driveway. Doing all four at once is a press conference, not a plan.
Rough policy triangle:
  Protect plants
  Keep sticker prices tolerable
  Hit official emissions targets
Pick two. Pretend you picked three.
That little sketch is cynical. It is also closer to how cabinets actually bargain than the white papers they publish.
Suppliers Feel It Before The Badge Does
Tier-two machine shops do not hold press days. They hold purchase orders. When a platform is delayed or a plant takes two dark weeks, those shops cut overtime first. Tooling houses delay new fixtures. Logistics firms reroute empty trucks. By the time a headline mentions a famous marque, the pain has already traveled fifty kilometers down the road.
This is why market share is not a vanity metric. It is a map of who still gets to place the next order for stampings. Lose enough share and the supplier park thins. Once it thins, restarting is slower than any minister promises.
China Demand Cuts Both Ways
Here is a twist that still surprises people. Some European groups are hurting in China at the same time Chinese groups are advancing in Europe. Soft demand in the world’s largest car market knocks profits just as home turf gets contested. That is a two-front problem. You cannot price premium in Shanghai and discount in Stuttgart forever without the brand story fraying.
Joint ventures that once felt like a bridge now feel like a classroom. Local partners learned. They kept learning. The student showed up in Antwerp with a ship full of hybrids and a smile.
What “Flood” Actually Looks Like In Logistics
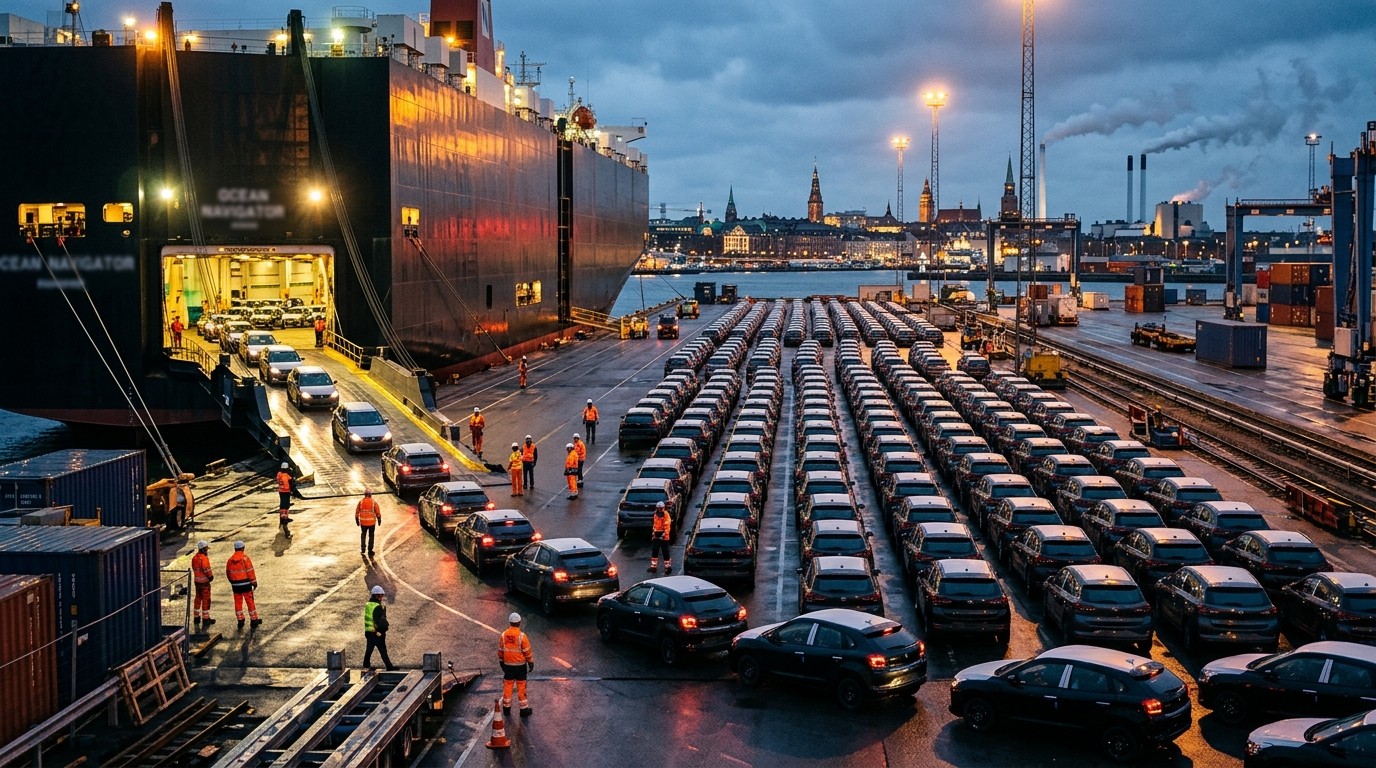
Ports tell the story without adjectives. Ro-ro ships dock. Compounds fill. Transporters fan out toward inland hubs. None of this requires a conspiracy. It requires freight rates, factory slots, and a bet that European buyers will choose value. The bet is paying.
Inventory risk sits with whoever misreads mix. If hybrids keep selling, the compounds clear. If a sudden tariff lands, someone eats storage fees. Traders already model that. Factories should too.
A Case Study The Rest Of The World Should Watch
Other regions like to treat Europe as a museum of regulation. That joke writes itself. The useful lesson is colder. If you set climate rules, energy prices, and trade policy without a ruthless plan for cost, someone else will sell the compliant product into your driveway. You can call that dumping. You can call it competence. The driveway does not care about the label.
Countries still building a mass auto sector should study the duty gap around hybrids. Countries trying to keep a mass auto sector should study how fast share can move when the product is “good enough” and the payment is kinder. Delay is a strategy only if your rival is also delaying. This rival is not.
Europe is teaching a master class in how noble targets and high input costs can open a market you thought you owned.
What Management Teams Can Still Do
Cut complexity. Too many platforms, too many unique parts, too many trim lines that exist because a committee liked a sketch. Kill the slow sellers. Put software teams next to the people who actually bolt the car together. Negotiate energy like it is a raw material, because it is. Stop pretending a luxury halo will subsidize a weak compact forever.
None of that is glamorous. All of it is cheaper than waiting for a perfect tariff. A tariff might come. It might not cover hybrids. It might arrive after another two points of share are gone. Hope is not a sourcing plan.
- Fewer architectures, higher volume per line.
- Honest pricing instead of list prices nobody pays.
- Dealer incentives tied to turn, not theater.
- Supplier contracts that survive a two-week halt without a funeral.
Workers will ask why discipline starts with them. Fair question. Discipline that starts only with them fails. Discipline that starts with product clutter and energy contracts has a chance.
Investors Should Stop Treating This As A One-Quarter Story
If you hold European auto names, the August print is not a curiosity. It is a volume and mix risk that bleeds into residuals, dealer working capital, and the political option value of tariffs. If you hold logistics and port operators tied to inbound finished vehicles, the same print is a volume tailwind with policy risk attached. If you hold battery materials, ask who actually wins the pack, not who wins the speech.
I am not handing out tickers. I am saying the share shift is now large enough to show up in ordinary financial statements, not just in color commentary. Write-downs, margin cuts, idle weeks: those are already on the tape.
The Human Texture Behind The Percentages
A line worker in Piedmont does not experience “twelve percent.” He experiences a roster. A designer in Wolfsburg does not experience “hybrid mix.” She experiences a cancelled clay model. A buyer in Lyon experiences a lower monthly debit and a cabin screen that feels current. All three stories are true at once. Articles that pick only one are selling a side.
That is why the tone around this topic gets sharp. It is not only trade theory. It is identity, bills, and the fear that a skill built over decades can leave in a shipping schedule.
What Comes Next If Nothing Material Changes
Share keeps grinding higher in the value bands. Locals defend premium and fleets. Governments float hybrid duties, then water them down after retailers complain. A few plants go from pause weeks to permanent shift cuts. Election flyers mention factories. The next summer of sales data looks like this summer, only louder.
Alternatively, a hard tariff lands, prices jump, and the political argument flips from jobs to inflation. Either path is messy. The clean path already left the station when energy costs and duty design drifted out of alignment with industrial reality.
Will European groups close the cost gap? Some will on specific models. The industry as a whole will not do it by repeating last decade’s product cadence. That cadence assumed time. Time is what the import ramp just spent.
A Straight Closing Thought
Cheap Chinese cars did not hypnotize Europe. They offered a price and a powertrain that fit the rules as written. Domestic brands are buckling where cost and speed lagged. Record market share is the receipt. If leaders wanted a different receipt, they needed a different stack of energy, trade, and product decisions years ago. They can still change the next chapter. They cannot unprint August.
I keep coming back to that showroom moment. Two keys on the desk. One badge you grew up with. One payment that lets you sleep. Most people will sleep. Industries that forget that fact do not stay industries for long.