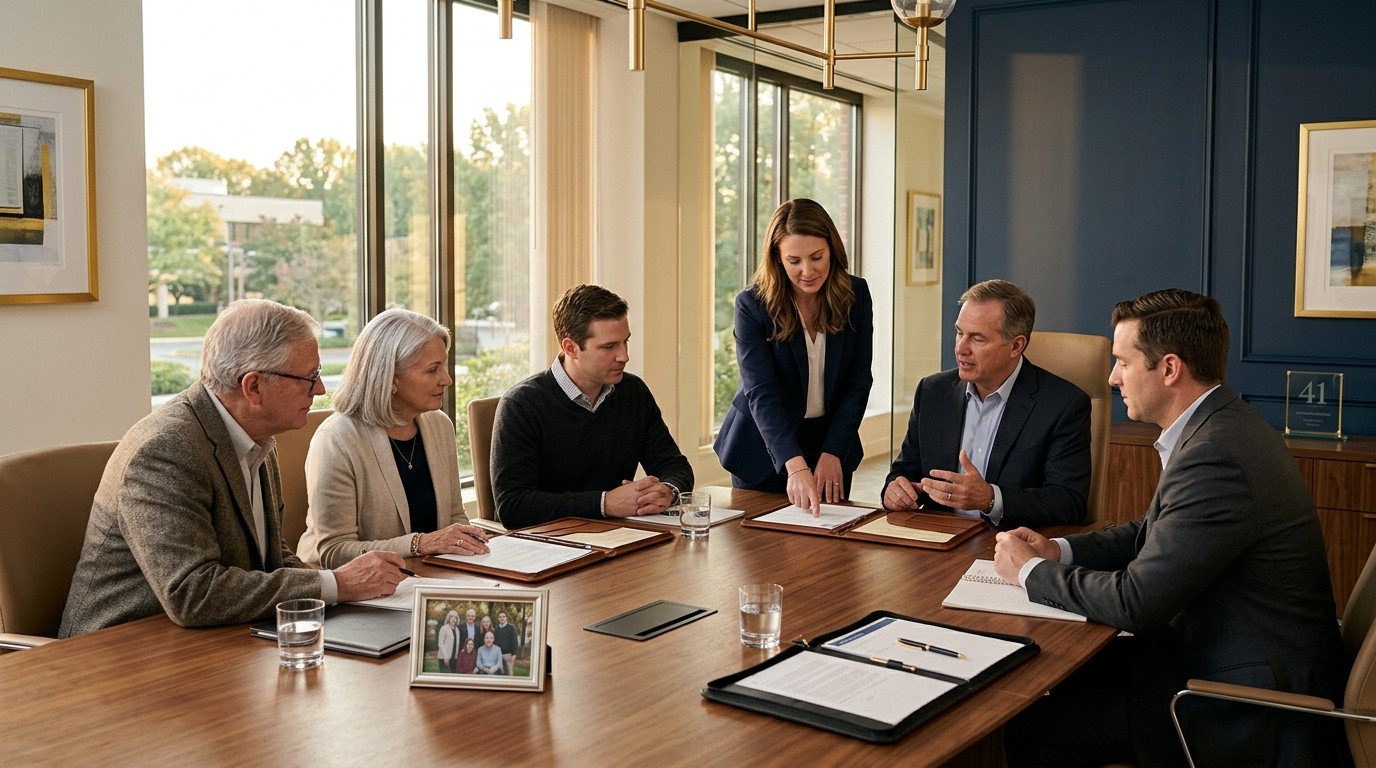

Perhaps the most interesting aspect is how ordinary the middle of a top-100 list can look until you do the math. Rank 41 is not a trophy on a shelf. It is a firm large enough to run real planning infrastructure and still small enough that leadership names are public and reachable. Tracey A. Baker serves as president, Dave D. Greene as chief executive officer, and Brian T. Jones as chairman. The public profile describes a practice that serves a wide variety of clients with planning needs across multiple generations. That sentence is easy to skim. It is also the part that decides whether the relationship will feel personal or procedural five years from now.
What A National Advisor Ranking Actually Measures
Rankings of advisory firms have a bad habit of being treated like sports tables. People glance at the order, assume higher is safer, and stop reading. I have found that approach disappoints almost everyone involved. A serious list, the kind that looks past raw assets under management, tries to weigh how a firm helps clients move through an actual financial life. Growth of assets matters. So does tenure, client breadth, and the ability to handle planning that does not fit a single product shelf. CJM Wealth Advisers landing at No. 41 tells you the firm cleared a filter that many practices never face. It does not tell you whether the investment philosophy matches yours, whether the service model fits a household that argues about vacation houses, or whether the minimum keeps you out of the room entirely.
Think of the list as a shortlist produced by someone else. Useful, yes. Final, no. Recent industry commentary keeps repeating a point that still gets ignored in kitchen-table conversations: assets under management are a scale metric, not a quality metric. A firm can gather a large book and still deliver thin planning. Another can stay smaller and go deep on tax coordination, estate documents, and the awkward conversations that happen when adult children inherit both money and opinions. The ranking in question explicitly looks beyond assets. That is the right instinct. It still leaves the personal fit test in your hands.
A ranking can open the door. Only the planning conversation tells you whether you want to stay in the room.
Seasoned wealth planning observer
Scale Without The Illusion Of Safety
$1.6 billion is a serious book. It is not a mega-platform number, and that distinction matters more than people admit. At this size, a firm can employ specialists, maintain compliance systems, and offer planning that a two-person shop often outsources in pieces. It can also still know who its clients are. Divide the assets by the account count and you get a rough average near $600,000 per account. That figure is only an average. It hides concentrated households above the $1 million threshold and smaller related accounts that sit alongside a primary relationship. Averages lie in polite ways. Still, the arithmetic suggests a client base that is affluent without being exclusively ultra-wealthy.
Forty-eight years in business is the quieter number. Longevity does not guarantee wisdom, but it does mean the firm has lived through more than one market regime. Inflation scares, rate shocks, tech bubbles, quiet decades, sudden crashes. A practice that started in the late 1970s has watched clients retire, remarry, sell companies, and argue with siblings over lake houses. In my experience, that kind of institutional memory shows up less in performance charts and more in how calmly a team handles a messy transition. You will not see that on a ranking page. You will feel it, or not, in the first planning meeting.
The Minimum Is A Filter, Not A Courtesy
The $1 million minimum asset threshold is the line most readers either clear or do not. Firms publish minimums for reasons that are partly economic and partly cultural. Planning at a high level takes senior time. If the fee on a smaller account cannot support that time, the relationship becomes a brochure with occasional check-ins. A published threshold is more honest than a soft no delivered after three meetings. It also tells you something about who sits in the waiting room. Households that meet a seven-figure minimum tend to arrive with concentrated stock, a business sale on the horizon, inherited assets, or a retirement date that is no longer theoretical.
Does a minimum mean better advice? Not automatically. It means the firm has chosen a client profile and built a service model around it. If your investable assets sit well below that line, admiring the ranking will not change the intake policy. If you are above it, the next question is whether the firm wants the complexity you actually have, not just the assets you can transfer.
A Snapshot Of The Public Profile
Before going further, it helps to put the disclosed facts in one place. These are starting points for questions, not a substitute for Form ADV, a service agreement, or a conversation with the people who would actually run your plan.
| Detail | What Is Publicly Stated |
| Ranking position | No. 41 on a national advisor list for 2026 |
| Assets under management | About $1.6 billion |
| Accounts under management | 2,667 |
| Years in business | 48 |
| Geographic reach | Accepts clients in all 50 states |
| Offices | Physical offices in Virginia |
| Minimum | $1 million asset threshold |
| Location | Falls Church, Virginia |
| Leadership | President, chief executive officer, and chairman named publicly |
Notice what is missing. Fee schedule. Custodian. Typical portfolio construction. Whether the firm is a pure fiduciary on every account type. How often plans are refreshed. Whether tax preparation sits in-house or with outside accountants. A ranking page is a postcard. The relationship lives in the documents you have not seen yet.
Multi-Generational Planning Is The Real Product
The public description emphasizes clients with a breadth of planning needs across multiple generations. That phrase deserves more attention than the rank. Money that stays in one household for one retirement is complicated enough. Money that has to survive a founder, a spouse, two adult children who do not speak the same financial language, and a grandchild with a trust is a different craft. I have watched otherwise competent portfolio managers freeze when the meeting stops being about allocation and starts being about fairness. Who gets the vacation property. Who is trustee. Whether the family business should be sold or split. Those questions do not have a benchmark.
A firm that claims this kind of work should be able to describe, in plain language, how it coordinates investment management with estate documents, beneficiary designations, and the tax picture. Coordination sounds dull. It is where wealth is accidentally lost. An IRA titled one way and a will written another way is a classic quiet error. So is a trust that nobody has reviewed since the children were in middle school. Multi-generational planning is less about a fancy family-office label and more about someone noticing the mismatch before a death or a divorce makes it permanent.
- Investment policy that can be explained to a spouse who does not attend every meeting
- Estate documents that match account titles and beneficiary forms
- A tax view that includes capital gains, retirement withdrawals, and charitable intent
- A communication plan for adult children who will eventually inherit decisions, not just assets
- A process for concentrated stock, business interests, or real estate that does not fit a model portfolio
If a firm cannot walk through those items without retreating into jargon, the multi-generational claim is marketing. If it can, you are looking at the actual service, and the ranking becomes a secondary detail.
Virginia Roots And A National Client Map
CJM Wealth Advisers keeps its physical presence in Virginia, with offices tied to Falls Church, while stating that it accepts clients in all 50 states. That combination is increasingly common and still worth unpacking. A local office gives you a place to sit down. A national client map means the team is used to working across time zones, state tax quirks, and households that split the year between two climates. Remote planning can be excellent. It can also turn into a portal login and a quarterly PDF if nobody owns the relationship.
Ask how meetings actually happen. Some clients want a conference room on Fairview Park Drive. Others want a video call that does not require a flight. Neither preference is more sophisticated. The mismatch is what creates friction. A firm that has served clients for nearly five decades in one region may have a strong local referral culture. Expanding acceptance nationwide does not automatically mean the same density of attention in every state. Geography is not destiny. It is a logistics question you are allowed to ask out loud.
Leadership You Can Name
Tracey A. Baker, Dave D. Greene, and Brian T. Jones are the names attached to president, chief executive, and chairman roles. Named leadership is a small mercy in an industry that sometimes hides behind brand architecture. You still should not assume you will meet the chairman at your annual review. Larger books distribute client work across advisors, planners, and service staff. The useful question is who owns your plan day to day, who covers that person on vacation, and how decisions get escalated when a market drop collides with a family event.
Continuity matters more than a title. Forty-eight years implies succession has already happened at least once, or is underway. Firms that handle succession badly lose clients in clusters. Firms that handle it well barely make a headline. If you are interviewing, ask how the next generation of advisors is introduced to existing households. A graceful answer sounds specific. A vague answer sounds like a brochure.
Titles tell you who runs the firm. The service calendar tells you who runs your money.
How Households Actually Use A Firm At This Scale
Clients who clear a $1 million threshold rarely show up with a single tidy brokerage account. The pattern I see, again and again, looks more like a drawer that has not been sorted. A rollover IRA from a former employer. A taxable account built during a career. Employer stock. A rental property the family is sentimental about. Maybe a trust from a parent who was careful on paper and silent in conversation. The advisor’s job is not to impress you with a product. It is to decide what should be consolidated, what should stay where it is, and what should be sold even if the tax bill stings.
At $1.6 billion across 2,667 accounts, the firm is large enough that not every relationship looks identical. Some households want a disciplined portfolio and a once-a-year planning refresh. Others want help coordinating with an estate attorney and a CPA through a liquidity event. A good firm can do both without pretending they are the same engagement. When you read that the practice serves a wide variety of clients, read it as a claim about range. Then test the range against your own mess, not against an idealized case study.
Questions Worth Asking Before You Transfer A Dollar
Rankings create a false sense that the hard work is done. It is not. The hard work is the interview, and it should feel slightly uncomfortable. You are hiring someone to sit inside decisions that will outlast a market cycle. Courtesy is fine. Vagueness is not.
- Who is the lead advisor, and how many households does that person actually serve?
- How is the firm paid, and what does the fee cover beyond portfolio management?
- Are there proprietary products, revenue-sharing arrangements, or custody relationships you should see in writing?
- How often is the financial plan updated, and what triggers an unscheduled review?
- How does the team coordinate with your attorney and tax professional?
- What happens to your relationship if your lead advisor leaves?
- How are adult children brought into the conversation, and when?
- What does the firm refuse to do, even for a large account?
That last question is underrated. A firm with standards will decline work that does not fit. A firm that says yes to everything is either unusually gifted or unusually eager. I lean toward the second reading until proven otherwise.
Fees, Fiduciary Duty, And The Fine Print You Should Demand
The public ranking snapshot does not publish a fee schedule for CJM Wealth Advisers, so anyone quoting a number is guessing. Do not guess with your own money. Advisory fees in this part of the market are often asset-based, sometimes with a planning retainer, sometimes with project fees for a one-time engagement. The percentage matters less than the scope. A lower fee that covers only trading can be more expensive, in outcome terms, than a higher fee that includes tax-aware withdrawals and estate coordination. You are not buying a discount. You are buying attention.
Fiduciary status is another phrase that gets waved around until it loses shape. Ask when the duty applies, to which accounts, and whether any part of the relationship sits under a different standard. Put the answer next to the Form ADV brochure. If the spoken version and the written version diverge, believe the written one. This is not cynicism. It is how the industry is built. Registration, custody, and disclosure exist because memory is a poor filing system.
A practical fee conversation:
  What is included
  What is billed separately
  What outside professionals still cost
  What would change the fee next year
Retirement Is A Planning Problem Wearing An Investment Costume
Many households that meet a seven-figure minimum are within a decade of drawing on the portfolio, or already are. The investment debate, stocks versus bonds, active versus passive, can swallow the meeting. The decisions that change a retirement are often elsewhere. When to claim benefits. How to sequence withdrawals so taxes do not spike in a single year. Whether a Roth conversion makes sense before required distributions begin. How a surviving spouse’s cash flow changes if the higher earner dies first. None of that is glamorous. All of it is wealth management in the only sense that matters.
A firm with nearly five decades of client history should have seen these transitions enough times to have a method. Ask for the method, not a promise of returns. Markets will do what they do. A withdrawal plan that ignores taxes is a plan that donates optional money to the calendar. I have found that couples relax once someone maps the first five years of retirement income in actual dollars, not in percentages. Percentages feel like theory. A monthly number feels like groceries, travel, and the gift you wanted to make to a child without wrecking the plan.
Risk Is Not A Slider On A Questionnaire
Risk tolerance forms are a starting ritual. They are not a strategy. Two people can both circle “moderate” and mean opposite things. One cannot sleep if the account drops ten percent. The other cannot stand the idea of outliving the money. A serious advisor separates the emotional tolerance from the financial capacity to take risk, then tells you when those two conflict. That conversation is where trust is either earned or performed.
At the account volumes CJM Wealth Advisers reports, model portfolios are almost certainly part of the machinery. Models are not a flaw. They keep implementation consistent and reduce the chance that every client gets a bespoke experiment. The flaw appears when a model ignores a concentrated position, a pending home sale, or a pension that already covers basic living costs. Customization should show up at the planning layer even when the portfolio layer is disciplined. If someone tells you every client is entirely unique and also entirely in the same five funds, ask which sentence is true.
Tax Efficiency Without The Magic Trick
Tax-aware investing is one of those phrases that sounds like a product and behaves like a habit. Asset location, harvesting losses when they exist, placing income-heavy holdings in tax-deferred accounts, timing gains around a low-income year. None of this requires a secret. It requires someone who looks at the tax return and the portfolio in the same week. Multi-generational households add another layer: gifts, trusts, step-up in basis, and the difference between what feels fair and what the tax code rewards.
You do not need your advisor to replace your CPA. You do need them to speak to your CPA without you translating. Firms that treat tax as an annual surprise are choosing a simpler business model. Firms that treat tax as part of the plan are doing the work the ranking language gestures toward when it talks about navigating a financial life. Ask for an example, anonymized, of a decision that changed because of taxes. Specifics beat slogans.
Comparing Fit Across Different Household Stages
Not every affluent household needs the same firm, even when the asset number clears the same hurdle. Stage matters. A couple still accumulating, with equity compensation and young children, has a different calendar from a widow managing a trust and a charitable pledge. The table below is a thinking tool, not a scorecard of any single practice.
| Household Stage | What Usually Matters Most | Where Firms Drift |
| Late career | Equity comp, savings rate, tax brackets | Over-trading the portfolio, ignoring benefits |
| Early retirement | Withdrawal sequence, health coverage, cash buffer | Treating retirement like a smaller version of work |
| Established retirement | Required distributions, gifting, survivor income | Set-and-forget reviews |
| Multi-generational transfer | Trusts, titles, family communication | Talking only to the original client |
CJM Wealth Advisers’ stated focus on planning needs across generations suggests the last row is not an afterthought. Treat that as a hypothesis. Confirm it by asking how many client families include adult children in at least one meeting a year. A number, even a rough one, tells you more than a mission statement.
The Psychology Of Handing Over The Keys
There is a personal side to this that rankings never capture. People delay hiring an advisor because hiring one feels like admitting the spreadsheet on the kitchen table is no longer enough. Sometimes it is not. Sometimes the spreadsheet is fine and the household simply wants a second set of eyes before a large decision. Both motives are legitimate. What is less legitimate is outsourcing judgment entirely. A good relationship leaves you more fluent, not more dependent. You should be able to explain your plan to a skeptical friend without calling the office for a script.
Couples complicate this further. One partner often drives the advisor search. The other arrives wary, or bored, or quietly relieved. I have sat in enough of these conversations, in a journalistic sense and a practical one, to know the quiet partner is frequently the person who will live with the plan longest. A firm that schedules the first meeting at a time only one spouse can attend is optimizing for speed. A firm that insists on both, when both exist, is optimizing for a relationship that survives the first disagreement. That preference is not romantic. It is operational.
What Rank 41 Does Not Promise
It does not promise outperformance. It does not promise that your calls will be returned in an hour. It does not promise that the investment style will feel familiar if you have spent twenty years picking individual stocks. It does not promise that a $1 million minimum will be waived because your situation is interesting. Lists are edited artifacts. They compress a firm into a line. The line can be accurate and still incomplete.
What the position does suggest is that outside reviewers found enough substance to place the firm in a national top 100 that claims to look past assets alone. Combined with 48 years, a named leadership group, a Virginia office, and a client map that spans the country, you have a credible candidate for a shortlist. Credible is the right word. It is not a synonym for chosen.
A Practical Way To Read Any Advisor Profile
When I read a firm profile now, I use a small routine. First the constraints: minimum, location, who they will not serve. Then the tenure, because short histories hide cycle risk. Then the client description, because “everyone” is not a niche and “families” can mean anything. Then the gaps. Fees, custody, planning cadence, succession. The gaps are where the next conversation lives. CJM Wealth Advisers’ public snapshot fills the first half of that routine cleanly. The second half is your job, or your attorney’s, or both.
- Confirm the minimum still applies to your account type
- Read the latest brochure and disciplinary disclosures yourself
- Ask for a sample review agenda, not a performance tear sheet
- Bring last year’s tax return to the second meeting, not the first
- Decide in advance what would make you walk away
Walking away is allowed. A ranking is not a contract. Households sometimes stay with a poorly matched firm because leaving feels like admitting a mistake. The more expensive mistake is staying out of politeness. Money is patient about many things. It is not patient about a service model that does not fit.
Estate Planning Sits Next To The Portfolio, Not Under It
Wealth that is meant to cross generations fails in boring ways. Outdated beneficiaries. A trust that names a successor trustee who moved abroad and does not want the job. Real estate titled in one name while the financial plan assumes joint ownership. Charitable intent that was discussed at dinner and never written down. An advisor does not replace estate counsel. An advisor who never asks whether counsel has been in the file recently is managing a portfolio that may not belong to the people the client thinks it belongs to.
This is where the multi-generational claim either becomes real or stays decorative. Ask how the firm tracks beneficiary reviews. Ask whether they will attend a meeting with your attorney. Ask what they do when two siblings want different things and both are clients, or one is. Conflict policies are not an insult. They are a sign the firm has already met the situation you are hoping to avoid. According to planners who work with inheriting families, the hardest meeting is rarely the one about asset allocation. It is the one about who gets to decide.
Communication Cadence Is A Hidden Fee
Some clients want a portal and silence. Others want a voice on the phone when headlines get loud. Neither is wrong, and a firm cannot be both for everyone at the same intensity. With thousands of accounts, communication has to be designed. Designed does not mean impersonal. It means someone decided what a review includes, how fast a trade-related question is answered, and what counts as an emergency. You should hear that design before you sign.
I prefer firms that can describe a bad week. What happened in the last sharp selloff. Who called whom. Whether the message was “stay the course” without looking at cash needs, or whether someone checked the withdrawal calendar first. Generic reassurance is cheap. A specific recollection is evidence of a process. Forty-eight years gives a firm plenty of bad weeks to draw from. Use that.
Review rhythm worth confirming: annual plan, midyear tax check, event-driven call, heir introduction.When A National List Is Worth Your Afternoon
Lists earn their keep when you do not already have a trusted name. They narrow a chaotic market into something a person can research. They also create a herd. Households in the same social circle often end up interviewing the same three firms because those firms ranked well and a neighbor mentioned them. That is fine if the fit is real. It is lazy if the fit is borrowed. Your neighbor’s pension, business sale, and family dynamics are not yours. Rank 41 is an invitation to do primary research, not to outsource it.
Primary research looks unglamorous. Read the disclosures. Compare the minimum to your actual investable assets, not your home equity, unless the firm counts housing, which most do not. Write down the three outcomes you want in the next five years. A retirement date. A gift to a child. A sale of a concentrated position without a tax surprise. Take those outcomes into the meeting and see whether the advisor reorganizes the conversation around them or around a model. The second pattern is common. The first is what you are paying for.
A Note On Expectations And Market Noise
Every ranking season arrives with market commentary attached, as if the list and the tape were the same story. They are not. A firm’s place on a 2026 list reflects a methodology applied to a track record of client service and scale. It does not forecast next year’s return. If someone uses a ranking to imply a performance edge, slow the conversation down. Advisory value shows up in avoided mistakes, coordinated decisions, and behavior when prices fall. Those things are hard to rank and easy to feel after a few years. Give the relationship time, and give yourself an exit criterion so time does not become inertia.
There is a metaphor I keep coming back to. Hiring an advisor is closer to choosing a long-term physician than to picking a restaurant from a crowded review site. You want competence, availability, and a person who will tell you no. Star ratings help you build a list of clinics. They do not take your blood pressure. CJM Wealth Advisers has the public markers of a clinic worth visiting if you meet the threshold and want planning that stretches past a single retirement date. The visit is still required.
How To Talk About This At Home
Money conversations stall when one person arrives with a ranking and the other arrives with anxiety. Try a smaller frame. Not “should we hire the firm at No. 41,” but “do we want professional coordination for the next decade, and does this profile match how we live.” Falls Church may be convenient or irrelevant. The million-dollar line may be cleared or not. The multi-generational language may describe your children or describe someone else’s. Sort those facts at the table before you sort managers.
If you are the adult child of someone already working with a firm of this kind, the useful move is curiosity rather than a surprise audit. Ask to understand the plan. Ask who to call. Rankings do not transfer loyalty, and loyalty should not transfer blindly either. Families that handle this well treat the advisor relationship as shared knowledge, not as a sealed folder. That is a cultural choice as much as a financial one.
Red Flags That Outrank Any List
A few patterns should end a search regardless of where a firm sits on a national table. Pressure to move assets before you have read disclosures. Vague answers on fees. Reluctance to include a spouse. Promises that a particular return is likely. Dismissal of your existing attorney or CPA. A minimum that is waived with a story that does not appear in writing. None of these are implied by a No. 41 placement, and none of them are cured by one. Process protects you. Charm does not.
On the other side, green flags are quieter. A clear scope. A named service team. A willingness to say a request is outside the firm’s lane. Documents that match the pitch. A planning agenda that mentions taxes, estate titles, and cash flow in the same breath as investments. If CJM Wealth Advisers shows you those things in a live meeting, the ranking did its job. If the meeting cannot produce them, the ranking is just a number you saw on a Thursday morning.
The best advisory relationships make the ranking irrelevant within a year, because the work has become specific to your life.
Independent planning commentator
Putting The Numbers Back In Proportion
$1.6 billion. 2,667 accounts. 48 years. A $1 million minimum. Offices in Virginia. Clients accepted nationwide. Leadership you can name. A No. 41 placement on a 2026 list that claims to weigh more than assets. Hold those figures lightly and use them hard. They tell you this is an established practice with enough scale to run a real planning operation and enough focus to publish a threshold. They do not tell you the fee, the fit, or the feeling of the third meeting, which is often when the real questions arrive.
If you are building a shortlist, put the firm on it when the profile matches your asset level and your need for advice that crosses generations. Then do the unfashionable work. Read. Ask. Compare. Talk to your spouse. Decide what success looks like in five years, in dollars and in family calm. Rankings will be updated. Your plan has to live longer than the list. That, more than any position between 1 and 100, is the standard worth keeping.
And if the number still feels like the point, sit with this for a moment. The households that get the most from a firm like this rarely mention the ranking after the first month. They mention the call that happened before a home purchase, the tax projection that changed a withdrawal, the meeting where an adult child finally understood the trust. Those are small scenes. They are also the entire product. Everything else is context.
]]>