
Have you noticed how the cost of a simple chocolate bar seemed to climb forever last year? I certainly did. One day you are grabbing your usual snack without a second thought, and the next you are double-checking the price tag in mild disbelief. That sticker shock came straight from the cocoa market, which went on an absolute tear. Now the picture looks different. Fresh numbers on cocoa processing just landed, and they are stronger than most people expected. Chocolate company shares have started to move higher as a result. The big question floating around trading desks and kitchen tables alike is whether names like Hershey finally look like a solid place to put money.
What The Latest Cocoa Processing Numbers Really Tell Us
A recent industry survey showed that third-quarter cocoa processing in both Asia and Europe came in ahead of forecasts. That kind of beat rarely goes unnoticed. In Asia the jump was especially eye-catching. Processing climbed nearly thirty percent and hit its highest quarterly mark since 2011. Europe managed a more modest but still meaningful gain of just over three percent compared with the same period a year earlier. That marked the first time European grindings had risen on a year-over-year basis since early 2024.
Why does this matter so much? Grindings serve as a pretty reliable real-time proxy for demand from chocolate makers. When processors run more beans through their plants, it usually means they are preparing for higher production of chocolate products. After months of demand destruction caused by sky-high cocoa prices, any sign of recovery gets attention fast.
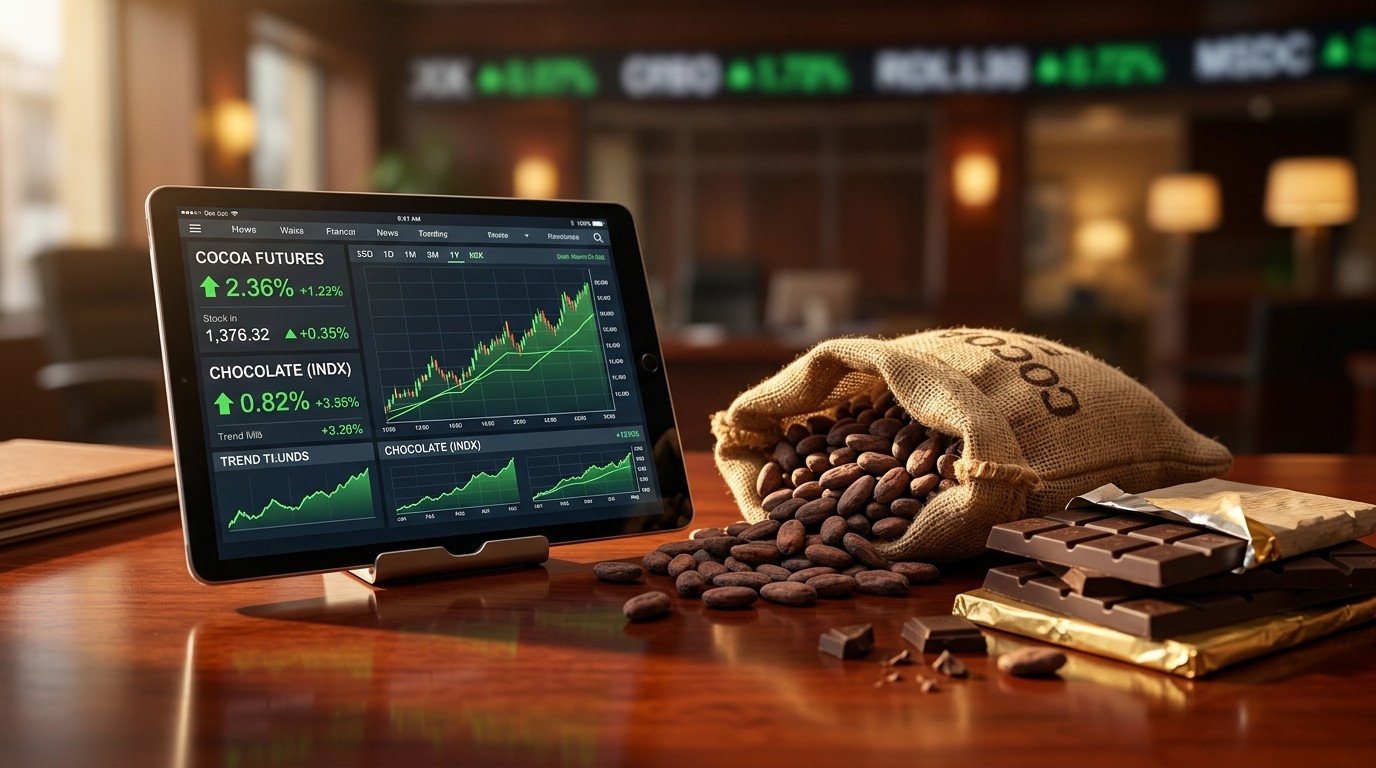
New York cocoa futures reacted the same day the data hit. Prices moved higher by about half a percent and settled near fifty-seven hundred sixty-two dollars a ton. That level sits roughly one hundred fifty-seven percent above the low printed earlier this year around twenty-two hundred forty-three dollars. Still, it remains more than fifty percent below the extreme peaks near twelve thousand dollars that traders saw at the height of the shortage late last year. The market had already been leaning bullish. These numbers simply poured a little more fuel on that sentiment.
The market was already trending in a bullish direction and this will add to the sentiment.
Weather and supply risks in West Africa have not disappeared, of course. Anyone who follows agricultural markets knows those regions can swing the balance of the entire global cocoa trade with a single poor rainy season. That lingering uncertainty keeps a floor under prices even as processing activity improves.
Why Lower Bean Costs Suddenly Matter Again
Remember the chaos of 2024? Cocoa prices went vertical and forced chocolate manufacturers into some uncomfortable decisions. Many reformulated recipes, reduced bar sizes, or simply raised retail prices until consumers pushed back. Demand took a clear hit. Now the situation has flipped. Bean costs have come down enough this year to restore healthier processing margins. That improvement encourages companies to ramp activity back up.
I have watched this cycle play out in other soft commodities before. When input costs retreat from extreme highs, the first thing processors do is protect or rebuild volume. Several chocolate companies have openly said they intend to focus on volume sales growth again. Stronger European grindings could be an early signal of that shift. Companies are preparing product for shelves rather than simply managing through a crisis.
Of course, not every observer is ready to declare victory. Some analysts point out that the rebound partly reflects weak year-ago comparisons after earlier sharp declines. Soft comparisons can make percentage gains look more impressive than the underlying recovery actually is. Fair point. Still, a twenty-nine percent surge in Asia is hard to dismiss as pure base-effect noise.
Chocolate Stocks Catch A Bid
Equity markets wasted little time reacting. Over the past five trading sessions several major chocolate-related names posted solid gains. Nestlé and Barry Callebaut each advanced more than six and a half percent. Mondelez climbed close to six percent. Lindt added over five percent. Hershey itself rose roughly three and a half percent. Those moves are not accidental. Investors appear to be pricing in the possibility that margin pressure is finally easing and that volume can stabilize or even grow again.
For long-term holders of these stocks the recent strength feels like a breath of fresh air. Many of these names spent months underperforming broader market indexes while the cocoa crisis dragged on. A turn in the fundamental backdrop gives portfolio managers a reason to re-examine positions they may have reduced or avoided.
Yet the rally remains selective. Not every chocolate name has participated equally. Hershey’s more modest gain compared with some European peers suggests investors still want clearer proof that the company’s own volume and share trends are improving. That proof may arrive sooner than people think.
The Critical Halloween Test For Hershey
One consumer staples analyst recently highlighted something important. September consumption and share trends for Hershey came in softer than expected. That soft patch raises the stakes for the October and Halloween period. Halloween remains one of the most important seasonal windows for the company. Strong performance during this stretch would support the idea that volume and share can improve into the following fiscal year. Weak results would cast doubt on that narrative.
In my view this is the kind of near-term catalyst that can separate a temporary bounce from a more durable recovery. Retailers order heavily ahead of Halloween. If those orders stick and sell-through looks healthy, the signal travels quickly through the supply chain. Processors, manufacturers, and investors all take notice.
I keep thinking about how consumer behavior shifted during the price spike. People still wanted chocolate, but many traded down to smaller sizes, private-label options, or simply bought less frequently. Reversing that habit takes time and competitive pricing. Lower bean costs give companies room to be more aggressive on promotions without destroying their own margins. That flexibility could prove decisive in the weeks ahead.
Looking Beyond The Immediate Numbers
Processing strength has not yet translated into a full, sustained recovery in end-consumer chocolate demand. That distinction matters. Grindings can rise for a quarter or two while retailers and manufacturers rebuild inventories. True demand recovery shows up in scanner data, household panel data, and eventual retail sales reports. We are not fully there yet.
Still, the direction of travel feels constructive. Lower input costs, improving processor margins, and early volume ambitions from manufacturers form a better fundamental backdrop than the one that existed twelve months ago. Weather risks in West Africa remain the wild card. A poor crop could send prices higher again and squeeze margins just as they start to heal. Conversely, a solid harvest would reinforce the current constructive tone.
Investors evaluating Hershey or its peers need to weigh several factors at once. Valuation relative to history and peers. Balance-sheet strength. Ability to innovate and protect market share. Exposure to the more resilient premium or better-for-you chocolate segments. And of course the company’s own guidance on volume recovery.
- Recent grindings data exceeded expectations in both Asia and Europe
- Lower cocoa bean costs are restoring processing margins
- Several chocolate stocks have rallied over the past week
- Halloween sales will serve as an important near-term demand test
- Supply risks in West Africa have not vanished
Perhaps the most interesting aspect is how quickly sentiment can shift in this sector. A year ago the conversation centered almost entirely on shortage and demand destruction. Today the talk has moved toward recovery, margin expansion, and volume rebuilding. That pivot does not guarantee smooth sailing, but it does change the risk-reward calculation for patient investors.
How Processing Data Connects To Investor Decisions
Commodity data can feel abstract until you connect it to company earnings. Higher grindings today often show up as better factory utilization and potentially stronger sales volumes a few months later. For a company like Hershey, which sits closer to the finished product than pure processors, the benefit arrives through improved raw material costs and eventual demand recovery at retail.
I have found that the best time to look at consumer staples names is often when the worst of the input-cost pain is already visible in the rear-view mirror but the recovery is not yet fully priced into the shares. That window can be narrow. The recent five-day rally suggests some investors are already acting on that logic.
Of course every situation is different. Hershey carries its own brand portfolio, geographic mix, and competitive dynamics. European pure-play processors face a somewhat different set of opportunities and risks. Diversified food giants with chocolate exposure sit somewhere in between. Treating the entire group as identical would be a mistake.
Margin Dynamics Worth Watching Closely
When bean prices fall, the benefit does not hit every company’s income statement at the same speed. Inventory accounting methods, hedging programs, and the mix of branded versus private-label business all influence the lag. Some firms may still be working through higher-cost inventory even as spot prices decline. Others may have already locked in lower costs for the coming quarters.
That lag creates an interesting period for analysis. Investors who dig into the details of each company’s cost structure and hedging disclosures can sometimes spot which names are likely to report the sharpest sequential margin improvement first. Those names often lead the equity group higher when the fundamental turn becomes clear.
At the same time, management teams face a strategic choice. Do they pass lower costs through to consumers via lower retail prices or more aggressive promotions in order to accelerate volume recovery? Or do they hold prices and expand margins more aggressively? Different companies are choosing different paths. Those choices will shape competitive dynamics for the next several quarters.
The Broader Context Of Soft Commodity Cycles
Cocoa is not the first agricultural commodity to experience a dramatic boom and partial bust. Coffee, sugar, and various grains have all gone through similar episodes. In almost every case the extreme price spike eventually encourages new supply, demand destruction, or both. The subsequent recovery phase can last longer than many expect because rebuilding consumer habits takes time and because producers remain cautious about expanding acreage too quickly.
In that sense the current cocoa situation feels familiar. Prices have retreated substantially from the peak yet remain elevated compared with the multi-year average before the crisis. Processing activity is recovering from depressed levels. Equity investors are beginning to look past the worst of the pain. The next phase will depend on how quickly end demand stabilizes and whether new supply arrives in time to keep prices from re-accelerating.
I remain cautiously constructive. The combination of better processing data, improving margins, and a key seasonal demand window creates a setup that is more interesting than it was six months ago. That does not mean every chocolate stock is a screaming buy. Valuation discipline and company-specific fundamentals still matter. But the sector as a whole has moved from defensive damage control into a more balanced conversation about recovery potential.
Practical Considerations For Anyone Watching These Names
Anyone considering exposure to the chocolate complex should keep a few practical points in mind. First, monitor the weekly and monthly grindings reports as they arrive. They offer one of the cleaner high-frequency signals available. Second, pay attention to retailer commentary around seasonal performance, especially Halloween and the subsequent holiday period. Third, watch management commentary on pricing and promotion strategies. Those decisions reveal how confident companies feel about demand elasticity.
Currency movements also play a role for companies with significant international exposure. A stronger or weaker dollar can amplify or mute the impact of commodity cost changes when results are translated back into reporting currency. Interest rate expectations matter too, because consumer staples often trade partly on yield and relative valuation versus the broader market.
None of this is particularly glamorous. It is the steady work of following a sector through a cycle. Yet that steady work is often where the better risk-adjusted opportunities appear. The dramatic shortage phase captured headlines. The quieter recovery phase may prove more rewarding for patient capital.
Putting The Pieces Together
The latest cocoa grindings data provide the first solid evidence in some time that processing activity is responding to lower bean costs. Asian numbers were especially strong. European figures turned positive on a year-over-year basis for the first time in a while. Futures prices firmed in response, and chocolate equities followed higher. Hershey participated but trailed some of its peers, leaving room for further upside if Halloween demand confirms the recovery narrative.
Risks remain. West African weather can still disrupt supply. Consumer demand has not yet shown a full and sustained rebound. Comparisons to weak prior periods may exaggerate the strength of the current improvement. Still, the overall direction feels better than it has in quite some time.
For investors who sold or avoided the sector during the worst of the cocoa crisis, the current environment invites a fresh look. Not every name will perform equally, and careful stock selection still matters. Yet the fundamental backdrop has shifted enough that ignoring the group entirely looks less justified than it did a year ago.
The coming weeks will bring more clarity. Halloween sell-through data, additional grindings reports, and company commentary on the holiday season will either reinforce the recovery story or raise new questions. Until then the market has already begun to price in a more constructive path. Whether that path leads to sustained gains depends on how the next few data points unfold.
In the end, chocolate remains a product people enjoy across economic cycles. The industry that delivers it is working its way through a classic commodity shock. The latest processing numbers suggest the worst of the demand destruction may be behind us. That simple observation is enough to keep a close eye on Hershey and its peers in the months ahead.
Markets rarely move in straight lines, and soft commodities are especially prone to surprise. Yet when processing activity improves, costs ease, and seasonal demand windows approach, the setup becomes more interesting than pure crisis mode. That is the environment we find ourselves in today. The data have spoken. Now the consumer and the weather will have their say.
I will be watching the Halloween numbers closely. If they come through cleanly, the recent equity rally may prove to be just the beginning of a longer recovery phase for the sector. If they disappoint, the market will likely reassess how durable the current optimism really is. Either way, the cocoa market has once again reminded everyone that even the most everyday products sit on top of complex and sometimes volatile supply chains. Understanding those chains can create opportunity when the numbers finally start to turn.