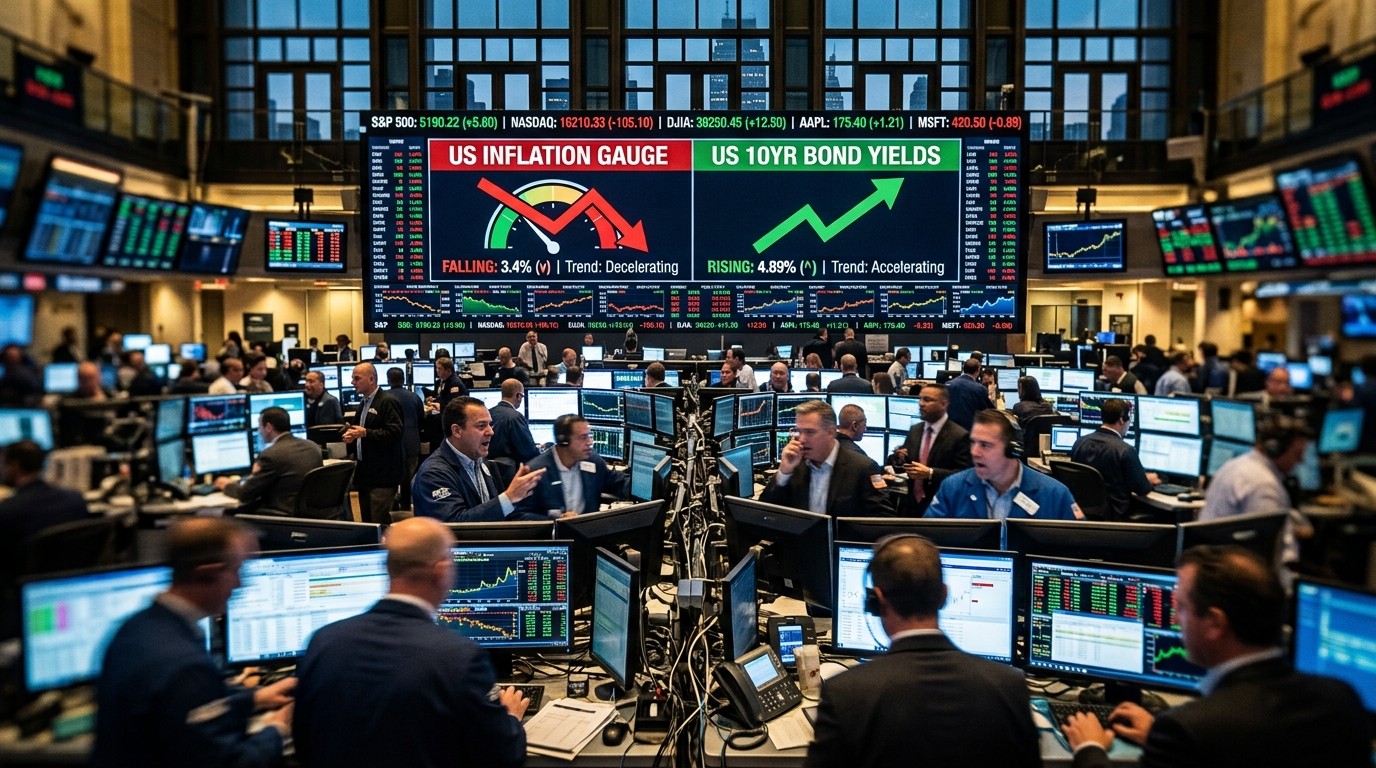

Have you ever watched a market open look almost cheerful, then feel the mood tighten before lunch? That was the vibe after the latest inflation numbers landed. The personal consumption expenditures price index rose 3.4 percent year over year in August, well below the 3.7 percent many desks had penciled in. Core PCE, which strips out food and energy, printed at 3.0 percent, also softer than expected. Equities caught a bid. Treasury yields slipped off multiyear highs. Odds of an October rate increase dropped toward 35 percent from something closer to 50 percent the day before. Then private payrolls showed a 90,000 gain against a 68,000 consensus, and the relief started to look conditional.
Why Cooler Inflation Did Not Clear The Path
I have sat through enough data mornings to know a single print rarely ends an argument. This one was genuinely helpful. It told investors the inflation fire was not burning as hot as feared in August. It did not tell them the fire was out. Markets still have to live with sticky services prices, a labor market that refuses to roll over on cue, and a growth pulse that keeps getting revised higher. That mix is why the session never turned into a full-blown melt-up.
Think of it as a weather report. The storm is weaker than the forecast. You still pack a jacket. Policy makers can wait and watch geopolitical risk, energy swings, and Friday’s official jobs report. They do not have to sprint. They also do not have permission to declare victory.
What The PCE Print Actually Said
Headline PCE at 3.4 percent year over year was the headline that traveled. The more useful piece, at least for policy talk, was the 3.0 percent core reading. Both undershot common forecasts. That gap matters because the central bank treats this gauge as its preferred inflation measure. When it cools more than models expected, rate-hike pricing usually loosens. That is exactly what happened in the first hour.
Still, cooler than expected is not the same as cool enough. Three percent core inflation is progress from the peaks of the last cycle. It is not the neighborhood policy makers have described as comfortable. I have found that markets love to treat a miss to the downside as a regime change. More often it is a single month with better luck on goods prices and a bit of help from energy.
The data today say the economy is not overheating, and that inflation was cooler than expected. There is no need to hurry with additional rate hikes.
– Market economist comment circulating on the Street
That view has a point. If growth is decent and prices are not re-accelerating in a dramatic way, patience becomes easier to defend. The counterpoint arrived in the same session. Private payrolls beat. Growth estimates for the third quarter still look firm. Second-quarter GDP was revised up to 2.2 percent. A resilient economy can keep inflation from sliding as fast as the bond market wants.
Treasury Yields, Equities, And The Relief That Stayed Contained
Yields backing off multiyear highs was the cleanest market reaction. When inflation surprises to the downside, duration usually catches a bid. Stocks liked the combination of slightly easier financial conditions and a lower chance of an immediate hike. The bounce was real. It was also polite rather than euphoric.
Why the restraint? Because traders were already looking past August prices and toward labor. A 90,000 private-payroll gain is not a boom. It is stronger than the 68,000 consensus. If Friday’s official report prints hot, the October odds can rebound and the year-end hike conversation gets louder again. In my experience, that second-order thinking is what keeps rallies from running away on inflation days.
Risk assets can handle cooler inflation. They get nervous when cooler inflation collides with a labor market that still looks tight enough to support wages. That tension is the whole story right now. Soft landing talk and higher-for-longer talk are living in the same room.
The Goldilocks Reading And Why It May Not Last
Some portfolio managers called the session a Goldilocks mix: inflation not too hot, growth not collapsing, hike odds for next month down but not to zero. That framing is neat. It is also fragile. Goldilocks only works if the next labor report cooperates and oil does not jump. A meaningful drop in crude would help the inflation path more than another speech. A spike would undo a lot of the good cheer from August PCE.
- Cooler headline and core PCE reduced the case for rushing a hike.
- Softer inflation helped pull yields off recent highs.
- Stronger private payrolls kept a later hike very much alive.
- Energy prices remain a swing factor for the next few prints.
- Friday’s official jobs report is the next live wire.
I keep coming back to that last bullet. Markets can digest one friendly inflation number. They have a harder time ignoring a labor surprise that implies demand is still running warm. Policy is data dependent in the most literal sense this month.
Why Some Voices Still Sound Unconvinced
Not everyone read the print as progress. A few economists argued that the favorite inflation gauge showed little fresh cooling in August and that September could look worse. That is a fair warning. Monthly noise cuts both ways. Base effects, energy, and housing services can shove a single reading around. If you only celebrate the undershoot, you miss the stall risk.
Perhaps the most interesting split is not bulls versus bears. It is people who treat this as permission to wait versus people who treat resilient GDP and payrolls as a reason the year-end hike is still the base case. Both can be right on different horizons. October can be a skip. December can still be live.
Today’s inflation data is somewhat better than expected, yet strong labor and GDP data suggest the print is unlikely to derail consensus expectations for another rate increase before year end.
That sentence captures the market’s half-smile. Relief, then a glance at the calendar.
How Investors May Position Into The Jobs Report
Nobody needs a heroic call here. The practical question is how to sit with two-sided risk for a few sessions. Duration benefited from the inflation miss. If payrolls come in soft, that bid can extend. If payrolls come in hot, the yield backup can resume quickly. Equities have been oddly resilient even as yields climbed over the past month. That resilience gets tested when the hike probability chart starts moving again.
I tend to think in scenarios rather than slogans.
- Soft jobs and stable energy: yields ease further, rate-hike odds fade, risk assets catch another bid.
- In-line jobs: the October skip stays priced, the late-year hike remains a debate, markets chop.
- Hot jobs: hike odds rebound, financial conditions tighten at the margin, leadership narrows again.
None of those paths require a dramatic new narrative. They require respect for the calendar. That sounds boring. Boring is often how real money avoids getting run over.
The Labor Market Is Still The Swing Vote
Inflation grabbed the morning headline. Employment decided whether the headline could stick. A 90,000 private-sector gain is not runaway hiring. It is enough to keep wage pressure from vanishing overnight. Policy makers have said they want to see the labor market cool in an orderly way. Orderly is the hard part. Too fast and growth scares show up. Too slow and inflation stays sticky in services.
Friday’s official report will be read through that lens. Average hourly earnings, the unemployment rate, and the breadth of hiring will matter as much as the headline payroll number. A strong print would not automatically force an October move. It would make a skip look less like a pause and more like a delay.
That distinction matters for stocks. A delay with falling yields is friendly. A delay with re-steepening hike odds is a different animal. Investors have been pricing resilience as a feature. Resilience can become a bug if it keeps the policy rate higher for longer than equity valuations quietly assume.
Growth Revisions Quietly Change The Backdrop
It is easy to obsess over one inflation release and miss the growth tape. Second-quarter GDP revised up to 2.2 percent is not spectacular. It is firmer than the stall story some investors wanted. Nowcasts for the third quarter have looked sturdy as well. When spending holds up, companies keep hiring. When hiring holds up, consumers keep spending. That loop is why disinflation can be uneven.
I do not see that as a reason to panic. I see it as a reason to stop treating every downside inflation surprise as the all-clear. An economy that keeps growing at a decent clip can absorb higher rates better than bears expected. It can also keep the central bank from cutting as soon as the bond market sometimes hopes.
For equity investors, that is a mixed blessing. Earnings hold up better in a resilient economy. Multiples face more competition from cash yields when policy stays restrictive. The tug-of-war between those two forces is why indexes can look calm while leadership underneath keeps rotating.
Energy, Geopolitics, And The Variables Nobody Controls
Oil is the uninvited guest at every inflation party. A meaningful retreat in crude would take pressure off headline prices and help sentiment around real incomes. A sudden jump works in the opposite direction and can drag yields higher even if core services are behaving. Geopolitical risk sits in the same bucket. Policy makers can wait to see how those risks evolve. Markets have to mark them every day.
That is why the “no need to hurry” argument feels sensible and incomplete at the same time. Waiting is rational when the incoming data are mixed. Waiting does not remove tail risk. If energy spikes, the next PCE print can look less friendly without any change in the underlying demand story.
What This Means For Different Corners Of The Market
Not every asset hears the same message. Rate-sensitive corners liked the drop in October hike odds. Parts of the market that need strong nominal growth were less impressed because the labor tape stayed firm. That split is worth watching more than the index level.
| Market sleeve | Near-term tilt | Main risk |
| Duration / Treasuries | Helped by cooler PCE | Hot Friday jobs print |
| Broad equities | Mild relief bid | Yields reversing higher |
| Small caps | Need easier financial conditions | Higher-for-longer rates |
| Financials | Can live with a skip | Curve and credit surprises |
| Energy-linked names | Tied to crude path | Geopolitical shock |
Small caps have already been lagging in a noticeable way. Higher yields and tighter financial conditions tend to pinch that cohort first. A sustained fade in hike odds would help. A one-day dip in yields probably will not rewrite the whole year.
A Practical Way To Read The Next Few Sessions
Ignore the urge to turn one morning into a thesis. Use a short checklist instead.
- Did yields stay down after the first hour, or did they bounce once payrolls hit?
- Are hike odds for October still sliding after the official jobs report?
- Is oil helping or fighting the inflation narrative?
- Are economically sensitive stocks leading, or is the bid narrow again?
- Do financial conditions ease in a lasting way, or only on the print?
If most of those answers stay friendly, the Goldilocks camp earns another week. If they flip, the market goes back to treating resilience as a policy problem. That is not dramatic analysis. It is how desks actually trade event weeks.
The Communication Problem Inside The Data
Inflation can move in the right direction and still leave everyone arguing. Part of that is math. Year-over-year rates fall slowly when the last mile is services. Part of it is psychology. After a long inflation scare, investors want a clean victory lap. Officials want more than one good month. Those clocks are not synchronized.
I have found that the most useful habit is to separate direction from destination. Direction this month was better. Destination is still above the comfort zone. That is why some strategists can sound almost upbeat while others insist progress has stalled. They are looking at different parts of the same chart.
Core at 3.0 percent is not a crisis. It is also not a reason to pretend the job is done. Markets that skip that nuance usually get surprised by the next speech or the next payrolls table.
Rate-Hike Odds Are A Weather Vane, Not A Verdict
Watching implied odds swing from about 50 percent to 35 percent in a day is catnip for headlines. Treat it as a weather vane. It tells you how the crowd updated one input. It does not lock the committee into a path. A hotter jobs report can send that number right back up. A soft report can bury the October discussion for good.
The more durable question is whether a fourth-quarter hike stays on the table. Several investors still think it does, even after the cooler PCE. Strong labor and firm GDP are the reasons. If those stay intact, skipping October is not the same as ending the tightening discussion.
The net effect is broadly supportive of risk assets and materially reduces the probability of an October rate hike, while keeping a later move on the table.
That is the compromise pricing we are living with. Supportive, not carefree.
Where Personal Judgment Creeps In
Here is my own read, offered with the usual humility that data weeks demand. The August PCE print was a genuine relief. It lowered the temperature. It gave policy makers cover to wait. It did not change the fact that inflation remains the central complaint in household budgets and in policy debates. If September goods and energy cooperate, the cooling story strengthens. If they do not, this week will look like a pause in a longer grind.
I would rather see yields ease because inflation is actually fading than because one print beat a too-high forecast. The second version is common. The first version is what equity bulls really need. We do not know which version we have until a few more months arrive.
That patience is unfashionable when screens are green. It is usually cheaper than assuming the woods are behind us.
A Longer View For Anyone Investing Past The Headline
Zoom out and the picture is familiar. Inflation came down from the emergency zone. It has been slower to finish the job. Growth surprised to the upside more often than the gloomiest forecasts allowed. Policy rates sit in restrictive territory. Markets keep trying to decide whether that mix is a soft landing or a delayed squeeze.
For long-term investors, the operational response is less exciting than the tape. Keep duration sized for two-way yield risk. Avoid building a portfolio that only works if hike odds collapse tomorrow. Respect that earnings can hold up even while multiples wobble. And remember that energy and labor can overwrite a friendly inflation morning in a single session.
Working map for the week:
  Inflation: cooler than feared in August
  Labor: still firm enough to matter
  Policy: October less likely, later hike still possible
  Markets: relief, not all-clear
If that map holds, choppy is the base case. If labor softens clearly, the map gets friendlier for bonds and for rate-sensitive stocks. If labor re-accelerates, the map tilts back toward higher-for-longer. Simple. Not easy.
The Last Mile Is Always The Noisy One
People love clean stories. Inflation down, stocks up, case closed. Real cycles rarely offer that. The last mile of disinflation is lumpy. Goods can help. Shelter can lag. Wages can stay firm even as hiring slows. One month undershoots. The next month does not. That is how you get a session that starts with a smile and ends with a shrug.
Was the inflation news good? Yes. Was it decisive? Not by itself. The market is still walking through trees, even if the path looks a little clearer than it did on Tuesday. Friday’s jobs report is the next fork. Energy is the wild card behind the trees. Policy makers can sit and wait. Portfolios still have to live with the path as it comes.
That is the unglamorous conclusion, and it is the honest one. Cooler prices bought time. Stronger payrolls spent some of that time immediately. Until both sides of the data line up for more than a day, it is too early to say the woods are behind us.