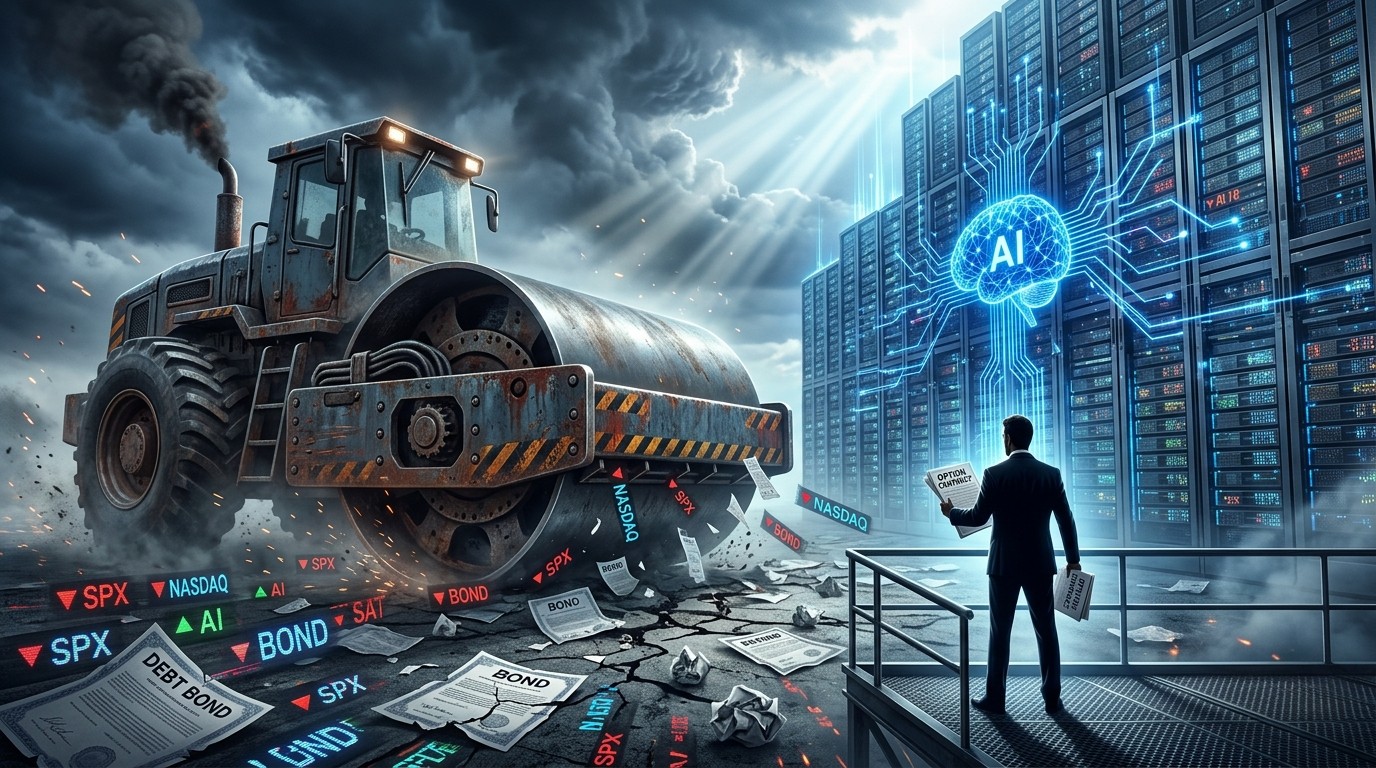

Have you ever watched something dangerous approach in slow motion and still failed to move out of the way? That is exactly how many equity holders have treated CoreWeave stock over the past several months. Warning lights flashed across the credit markets for a long stretch, yet share prices largely chopped sideways near support levels. Then the steamroller finally arrived. From last Friday’s close to Thursday morning’s 52-week lows the stock dropped a brutal 27.5 percent. A sharp 17 percent rebound followed almost immediately, only for shares to slip another 5 percent the next session. Investors who stayed put now look a bit dazed. With earnings only a few weeks away, heavy leverage, a deeply split sell-side, and short interest sitting near 15.4 percent, the setup remains primed for more explosive moves.
The Slow Steamroller Rolling Toward CoreWeave Equity
The comparison to that classic comedy scene feels almost too perfect. A guard stands in front of a steamroller that moves at a crawl, shouting “No” three times before getting flattened. The joke is that he had plenty of time to step aside. Equity traders holding CoreWeave essentially did the same thing. The credit side of the market had been flashing danger for months, yet many simply stood still and watched.
This company barely existed five years ago. Today it carries roughly $51.6 billion in debt, or about $46 billion net of cash, against a backdrop of zero historical profitability. That fact was widely known. What unsettled people more were comments from leadership about aspiring to investment-grade status so the firm could borrow “unlimited sums.” Investors were already pricing in nearly another $60 billion of debt over the next 18 months. Hearing talk of even more borrowing, especially after bonds issued only in June had already dropped 20 percent, felt like someone hitting the gas on an already overloaded vehicle.
From an options perspective the picture looked strange. Premia had fallen into the sixth percentile, roughly 1.5 standard deviations below the one-year average. At around 72 percent implied volatility the contracts were not cheap in absolute terms, yet given the deteriorating credit picture and rising leverage they still seemed too quiet. The stock itself looked somewhat complacent, grinding around historical support that dated back to May. Meanwhile the credit market was anything but calm.
What Credit Markets Were Already Saying
Bonds that priced at par in June with an 8.5 percent coupon had fallen nearly 18 percent by the end of last week. The real damage started with a sharp sell-off in late July and never fully recovered. Five-year credit default swaps told an even clearer story. They exploded from 452 basis points in early June to more than 1100 basis points this week. That level implies roughly a 60 percent probability of default over the next five years under standard recovery assumptions.
Cash flow numbers add another layer of pressure. Estimates point to $16.45 billion of negative free cash flow in the second half of this year alone, followed by another $30.6 billion of burn in fiscal 2027. At a 15 percent cost of capital the structural hurdle rate for new business is steep. Even if the company hits optimistic pricing targets through 2028, forecast debt-to-EBITDA at the end of that year still sits near 4.5 times. That is not a comfortable number for a business that has never turned a profit.
Because the equity is levered more than two-to-one, a 10 percent swing in enterprise value can translate into nearly a 22 percent move in the stock. That leverage works both ways, of course. It amplifies the upside when sentiment turns, which helps explain the violent rebound we just witnessed. Still, the underlying math remains unforgiving.
The Sell-Side Remains Deeply Split
Despite the credit deterioration, equity analysts have not reached any consensus. One major house keeps a sell rating and a $39 price target that essentially calls for the stock to be cut in half from recent levels. Other firms argue the fears are overblown and see the shares more than doubling from here. That kind of gap creates fertile ground for sharp moves in either direction.
High-profile voices have also stepped in to defend the story. The chief executive of a major chip supplier publicly downplayed systemic concerns. One well-known investment firm bought nearly 200,000 shares on the dip. Another large bank argues that the company’s ability to bring active power online at scale, combined with higher pricing from next-generation chip deployments, should drive faster revenue growth than the market currently expects. They view execution risk as the bigger issue compared with financing. Bondholders who bought the 2032 notes at par might disagree with that ranking of priorities.
In my experience, when credit and equity markets tell such different stories the eventual resolution tends to be violent. Someone is going to be proven wrong, and the path to that resolution rarely travels in a straight line.
Why Outright Directional Bets Feel Especially Risky Right Now
Earnings sit just a few weeks away. Short interest remains elevated. The stock has already shown it can drop nearly 30 percent and then rebound 17 percent inside a single week. Going long or short with naked equity exposure into that kind of environment carries more risk than many portfolios can comfortably absorb. That is where options structures start to look more attractive.
Options allow a trader to define risk more precisely while still capturing the kind of volatility this name is likely to deliver. The challenge is choosing a structure that does not require perfect timing or a precise directional call. Pure long straddles or strangles can get expensive when implied volatility sits at elevated levels. Pure short premium strategies can blow up if the stock gaps hard. A diagonal spread offers a middle path that many experienced traders favor in these mixed environments.
Breaking Down the November 80 / January 72.5 Call Diagonal
One structure that currently stands out is a call diagonal that buys the January 72.5 calls and sells the November 80 calls. At recent prices the spread could be entered for a little under $6. That represents almost 9 percent of the current stock price. Under normal conditions that debit would look expensive. After a 27.5 percent drop followed by a 17 percent surge in five sessions, the cost starts to look more reasonable relative to the realized moves.
Here is the basic construction:
- Buy the January 72.5 calls for roughly $10.25
- Sell the November 80 calls for about $4.30
- Net debit of just under $6 per spread
The short November calls help finance the longer-dated long calls. If the stock drifts higher or sideways into the November expiration, the short calls may expire worthless or can be rolled. The long January calls retain significant time value and maintain upside exposure if the bullish case eventually plays out. If the stock sells off hard, the maximum loss is limited to the net debit paid. That defined risk is attractive when the range of possible outcomes remains so wide.
Perhaps the most interesting aspect is how the structure behaves across different scenarios. A sharp move higher before November can produce solid profits if the short calls are managed carefully. A gradual grind higher into January can still work because the long calls keep their extrinsic value longer. A big downside move caps the loss at the initial debit. In a name this volatile, that kind of payoff profile feels more practical than an outright long or short position.
Understanding the Leverage Dynamics at Play
CoreWeave’s capital structure amplifies every move in the underlying enterprise value. When a company carries more than two dollars of net debt for every dollar of equity, small changes in the overall business valuation create large swings in the residual equity claim. That is pure mechanical leverage, not the options kind.
Investors sometimes forget how quickly that leverage can work against them. A modest disappointment on growth, power delivery timelines, or customer concentration can compress the enterprise multiple and wipe out a large percentage of the equity value. The reverse is also true. Positive surprises on pricing power or capacity utilization can produce outsized gains. The recent price action already demonstrated both sides of that coin within a single week.
I have found that traders who respect this leverage tend to size positions more carefully and lean toward defined-risk structures. Those who treat the stock like a typical large-cap technology name often get surprised by the magnitude of the moves.
The Role of Short Interest and Positioning
Short interest near 15.4 percent is high enough to matter. It creates the potential for short-covering rallies when positive catalysts appear, yet it also reflects genuine skepticism about the balance sheet. That dual nature adds another layer of unpredictability. Shorts can be forced to cover on good news, but they can also press their advantage on any sign of further credit stress.
Positioning among options market participants has been relatively quiet until recently. The fact that implied volatility sat in the sixth percentile while credit spreads were blowing out suggested many equity options traders were underpricing the risk of a sharp move. That complacency appears to be correcting itself after the recent price swings. Still, the options market often lags the credit market in these situations, which can create temporary opportunities for those paying attention to both.
Earnings as a Potential Volatility Catalyst
The next earnings report will arrive against this complicated backdrop. Management will need to address the pace of cash burn, the path to positive free cash flow, customer concentration risks, and the feasibility of the ambitious growth targets that underwrite the current valuation. Any perceived slippage on those fronts could reignite credit concerns and pressure the equity. Conversely, strong commentary on power delivery timelines or pricing trends could fuel another sharp rebound.
Either outcome is plausible. That is precisely why structures with defined risk and exposure to large moves make more sense than concentrated directional bets right now. The diagonal described earlier keeps the trader involved without requiring a precise forecast of the earnings reaction.
Practical Considerations Before Putting on the Trade
Every options structure carries its own nuances. Liquidity in the specific strikes matters. Bid-ask spreads on less active names can eat into theoretical edge. Early assignment risk on the short calls, while usually manageable, still needs monitoring if the stock rallies hard into expiration. Transaction costs and margin requirements also differ across brokers.
Position sizing remains the most important variable. Even a well-constructed diagonal can produce losses if the stock gaps through the long strike or if time decay works against the long calls faster than expected. Treating the net debit as the maximum risk and sizing accordingly helps keep the trade within acceptable portfolio limits.
Some traders prefer to scale into the position or adjust the strikes based on their own outlook. A more conservative version might use a higher long strike or a closer short strike to reduce the net debit further. A more aggressive version could involve longer-dated calls or different strike combinations. The core idea stays the same: use the short-term option to help finance longer-dated upside exposure while capping the downside at a known amount.
Broader Lessons From This Setup
CoreWeave is not the first growth company to face a tug-of-war between optimistic equity narratives and cautious credit markets. Similar patterns have appeared in other capital-intensive sectors over the years. What makes this episode stand out is the sheer speed of the debt accumulation and the size of the cash burn relative to the company’s short history.
The episode also highlights the value of watching credit markets alongside equity prices. Bond prices and credit default swaps often signal stress before it fully shows up in the stock. When those signals diverge sharply from equity options pricing, the opportunity for relative-value or volatility trades can appear. In this case the options market eventually caught up after a series of violent moves, but the lag created a window for those who noticed the discrepancy early.
I have found that the most consistent edge in these situations comes from respecting the information contained in the credit markets rather than dismissing it as temporary noise. Equity stories can remain compelling for long stretches even while the balance sheet deteriorates. Eventually the two markets tend to reconcile. The path of that reconciliation is rarely gentle.
Managing the Position After Entry
Once the diagonal is in place, active management becomes important. If the stock rallies strongly before the November expiration, the short calls may need to be covered or rolled to a higher strike or later date. Leaving them unattended risks assignment or the loss of further upside. If the stock sells off, the long January calls will lose value, but the loss remains limited to the initial debit. Some traders choose to roll the entire structure or reduce size if the thesis changes materially.
Time decay works differently across the two legs. The short November calls experience faster theta decay as expiration approaches, which can help the position if the stock stays below the short strike. The long January calls decay more slowly, preserving optionality. That differential is one of the structural advantages of the diagonal approach.
Volatility changes also matter. A sharp rise in implied volatility can boost the value of the long calls more than the short ones because of the longer maturity. A collapse in volatility can have the opposite effect. Traders who understand these second-order effects tend to adjust more intelligently when conditions shift.
Alternative Structures Worth Considering
The call diagonal is only one of several approaches that can fit this environment. Some traders prefer put diagonals if they lean bearish but still want defined risk. Others use calendar spreads centered on the same strike to isolate pure volatility exposure. Iron condors or butterflies can work if a trader expects the stock to settle into a range after the recent swings, though the elevated realized volatility of late makes those structures riskier than usual.
For those who want simpler exposure, long calls or long puts with carefully chosen strikes and expiration dates can still make sense if the directional view is strong and position size is kept modest. The key is matching the structure to both the market outlook and the risk tolerance of the portfolio. No single trade fits every account.
In my view the diagonal stands out right now because it balances the competing narratives without requiring a strong directional bias. The credit market is flashing caution. Equity dip-buyers remain active. Earnings loom. That combination favors structures that can profit from large moves while limiting the damage if the move goes the wrong way.
Looking Ahead at the Bigger Picture
CoreWeave sits at the intersection of two powerful themes: the explosive demand for artificial intelligence infrastructure and the classic risks that accompany rapid debt-fueled expansion. The company has built meaningful capacity in a short period and attracted high-profile partners. At the same time it has taken on a capital structure that leaves little room for execution missteps or a slowdown in customer demand.
The coming quarters will reveal whether the optimistic growth trajectory can outrun the heavy cash burn and rising interest burden. Power availability, chip supply, pricing discipline, and customer concentration will all play roles. Credit markets will continue to vote with their feet, and equity markets will react, often with a lag and sometimes with exaggerated swings.
For traders the opportunity lies less in predicting the ultimate outcome with precision and more in positioning for the volatility that the uncertainty will generate. Structures like the November-January call diagonal offer one practical way to stay involved without betting the farm on a single narrative. Defined risk, exposure to large moves, and the ability to adjust as new information arrives remain valuable traits in a name this dynamic.
The steamroller has already delivered one hard lesson. Equity holders who ignored the credit warnings paid a price. Those who respect both markets and size their exposure thoughtfully stand a better chance of navigating whatever comes next. Volatility is not going away anytime soon. The question is how each trader chooses to play it.
Markets rarely reward complacency when leverage and uncertainty collide at this scale. Staying alert to the signals from both credit and equity, keeping risk defined, and remaining flexible as the story evolves still looks like the most practical approach. The next few weeks should provide more clarity, though clarity itself may arrive through another round of sharp price action rather than a smooth resolution. That is the nature of this particular setup, and it is why thoughtful options structures continue to attract attention among those who trade it actively.