
I was watching the screens light up green this morning and felt that familiar pull. You know the one. Stocks climbing, headlines cheering, and part of you starts wondering if you should just dive in before the move runs away. Then Jim Cramer’s voice cut through the noise during his usual morning session, and the mood shifted. Something still feels off in this Tuesday advance, he said, and he is not eager to jump. That simple observation stuck with me longer than the percentage gains.
Why This Rally Feels Incomplete
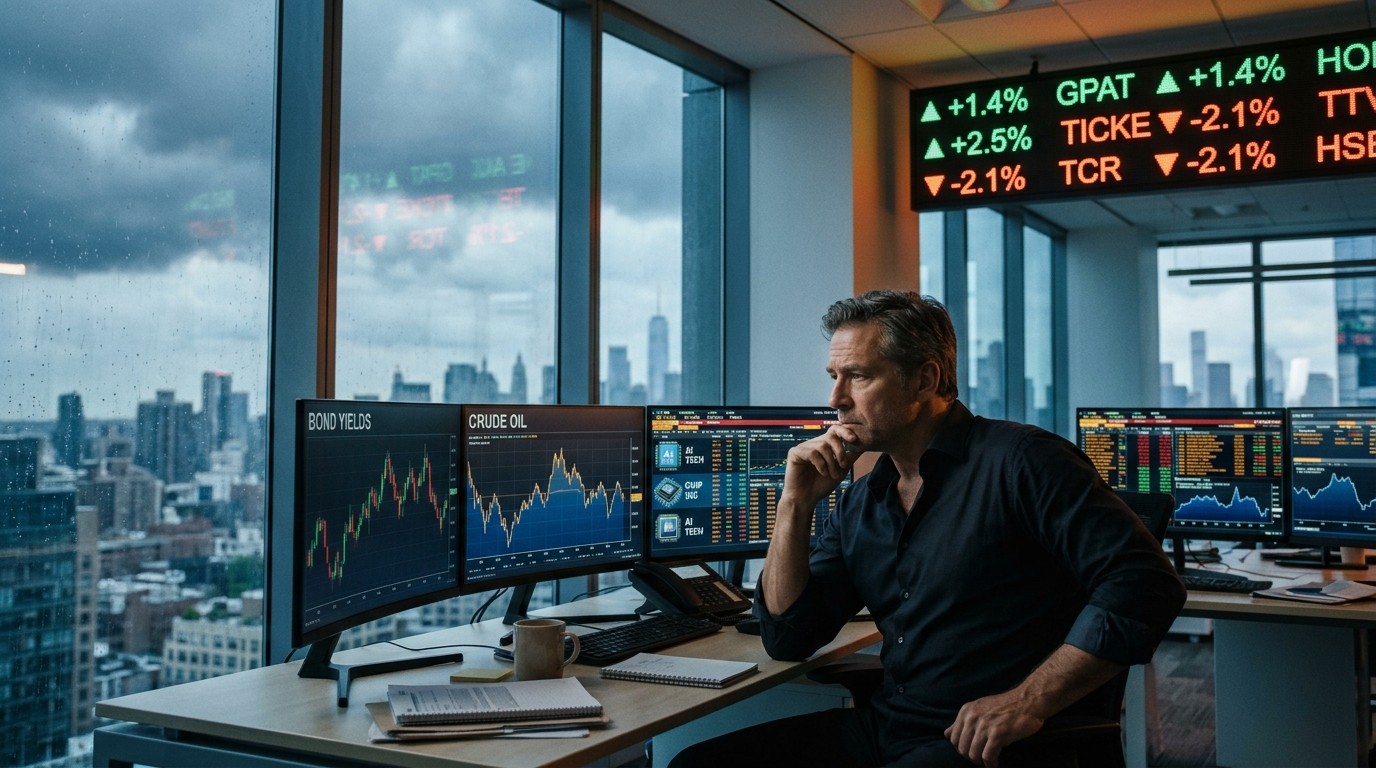
The S&P 500 moved higher today, helped by fresh optimism around major chipmakers. One standout story involved a large financing arrangement that supports artificial intelligence hardware purchases. On the surface everything looks constructive. Buyers showed up. Sentiment improved. Yet Cramer kept coming back to the same point. The advance lacks genuine conviction. It still reacts too sharply to everyday swings in bond yields and crude oil prices.
He compared those two variables to the weather. When yields climb or oil spikes, the market behaves like it is raining. When both stay calm, conditions feel sunny and buying becomes easier. “We don’t want to be in a market that’s controlled by the weather,” he explained. “We want to be in a market that’s controlled by conviction. And I don’t see a lot of conviction today.” That line captured the unease many experienced traders feel right now. The tape can rise, but the foundation still looks temporary.
Lower oil prices might normally encourage opportunistic shopping. Cramer pushed back against that instinct. He wants multiple solid reasons to buy rather than a single favorable data point. In my own experience watching these sessions, that distinction separates reactive trading from deliberate investing. The first approach often leads to quick exits when the weather changes again. The second requires patience that can feel uncomfortable while green candles keep printing.
Chip Optimism Provides Temporary Lift
Semiconductor names provided much of the early strength. The financing news around AI infrastructure gave the sector a tangible catalyst. Investors have been searching for confirmation that the artificial intelligence build-out continues at full speed. Any concrete deal that supports chip demand tends to spark buying across related stocks. Still, Cramer treated the move as surface-level enthusiasm rather than deep conviction. The broader market remains sensitive to macro variables that can reverse the tone within hours.
I have noticed this pattern more often in recent months. Sector-specific good news arrives, the averages respond, and then attention quickly returns to the ten-year yield or the latest oil inventory number. Until that sensitivity fades, every rally carries an asterisk. Traders who ignore the weather risk getting caught when conditions deteriorate without warning.
Meta’s Expanded Stock Sale Creates Ongoing Pressure
Another development that caught attention involved a large technology company upsizing its secondary equity offering. The deal grew to $25 billion from the original $22.5 billion target. Strong demand for the shares looks like a positive signal on the surface. Cramer acknowledged the healthy interest but immediately highlighted a larger concern. The company plans to sell another $60 billion worth of stock at market prices starting next year. That future supply sits over the shares like a persistent cloud.
At-the-market offerings create a specific kind of drag. Management hands execution to brokers who often sell into strength without much regard for daily price action. The continuous drip of new shares keeps the stock trading heavy. Upside becomes harder to sustain because sellers keep appearing. Cramer pointed to another major technology name that announced a sizable equity sale earlier this year, including an at-the-market component. Shares of that company have struggled to regain momentum since the announcement.
The problem with these at-the-money offerings is that companies outsource the execution to brokers who usually execute them in ham-fisted manners, without always caring about how the stock is performing in a given day.
That observation matches what many portfolio managers have quietly discussed. When a company signals it will keep selling equity for an extended period, natural buyers become more selective. They wait for better entry points or demand a higher risk premium. The result is a stock that can participate in broad market advances yet rarely leads them. For anyone holding the shares or considering a new position, the overhang deserves serious respect.
I find the psychology around these offerings particularly interesting. The market often celebrates strong demand for the initial tranche. Then the longer-term supply reality sets in and the celebration fades. Understanding that sequence helps investors avoid mistaking temporary enthusiasm for lasting support.
Boeing Earnings Trigger Sharp Reassessment
While chip names and secondary offerings occupied part of the discussion, the most dramatic individual stock move came from the aerospace manufacturer that reported results before the open. Revenue came in better than expected and free cash flow exceeded estimates. Those numbers looked respectable at first glance. Then the larger-than-anticipated loss per share and management commentary on future cash flow growth changed everything. Shares dropped nearly ten percent as the market digested the reset in expectations.
Cramer had already flagged the risk before the earnings call even began. He predicted that some analysts carried overly optimistic numbers for next year and would need to lower them. That call proved accurate. The conference call confirmed that the path to stronger cash generation would take longer than many had hoped. The sell-off intensified once those comments hit the tape.
Yet Cramer also offered a more constructive longer-term view. He described the session as a potential clearing event. Once the dust settles and estimates reset to more realistic levels, the weakness could create an attractive entry point for patient investors. That perspective separates pure reaction from measured analysis. Sharp declines after earnings often feel permanent in the moment. History shows that many of them simply remove the most aggressive expectations from the equation.
- Revenue beat expectations and free cash flow looked solid
- Loss per share came in larger than Wall Street anticipated
- Management guided toward slower cash flow improvement
- Analyst estimates for next year likely need revision lower
- The magnitude of the drop may eventually present opportunity
Watching the reaction unfold reinforced an old lesson. Good numbers in some categories cannot always overcome disappointment in the areas investors care about most. Cash generation and visibility matter enormously in capital-intensive businesses. When management dials back those expectations, the market tends to respond forcefully and quickly.
The Weather Versus Conviction Debate
Cramer’s weather analogy deserves extra attention because it captures something many investors sense but struggle to articulate. Markets that move primarily on daily fluctuations in yields or commodity prices rarely sustain meaningful advances. They produce choppy sessions filled with false starts and sudden reversals. True bull markets develop when company fundamentals, earnings momentum, and broader economic confidence drive buying decisions more than the latest tick in the bond market.
Right now the balance still tilts toward weather sensitivity. That does not mean every rally fails. It does mean each advance carries higher risk of interruption. Traders who treat every sunny day as the start of a long summer often get surprised by afternoon thunderstorms. The more disciplined approach involves waiting for clearer evidence that conviction has returned.
What would that evidence look like? Stronger breadth across sectors. Less dramatic reactions to modest yield moves. Companies guiding higher rather than simply meeting lowered expectations. Until those signs appear more consistently, caution remains the smarter default stance. I have learned over the years that missing the first part of a sustained move usually costs less than participating fully in several false starts.
Practical Lessons For Everyday Investors
Most individual investors do not need to trade every session. They need a framework for deciding when conditions favor action and when patience serves them better. Tuesday’s discussion offered several practical takeaways worth keeping close.
First, separate sector-specific catalysts from broad market health. Chip-related news can drive certain stocks higher without solving the larger issue of yield and oil sensitivity. Celebrate the individual winners without assuming the entire market has turned a corner.
Second, treat large future equity offerings as real overhangs rather than footnotes. When a company announces plans to sell tens of billions of dollars of stock over time, the shares often trade differently. The continuous supply changes the risk-reward calculation for both existing holders and potential new buyers.
Third, earnings reactions that reset expectations can create opportunity after the initial pain. The key is waiting long enough for the new information to be fully absorbed. Jumping in during the first hour of a ten-percent drop rarely produces the best results. Letting the market find a temporary floor often improves the entry price and reduces emotional decision-making.
Fourth, and perhaps most important, respect the difference between weather and conviction. Markets controlled by daily macro variables require different position sizing and different time horizons than markets driven by fundamental momentum. Matching your approach to the current environment protects capital more effectively than trying to force the same strategy onto every market condition.
Stocks In The Rapid-Fire Segment
Toward the end of the session Cramer touched on several individual names in quick succession. A major beverage company, a large package delivery firm, and a specialty materials producer all received brief comments. These rapid-fire discussions often highlight companies facing specific near-term questions rather than broad thematic ideas. They serve as useful reminders that individual stock stories continue even when the overall market narrative feels dominated by macro factors.
Investors who follow these segments carefully sometimes spot early shifts in tone. A more constructive comment on a beaten-down name can signal that the worst of the selling pressure has passed. Conversely, continued hesitation around a former favorite can indicate that the fundamental story still needs more time to improve. Either way, the rapid-fire portion adds texture to the broader market discussion.
Balancing Opportunity And Restraint
The hardest part of sessions like this one involves managing the psychological tension between opportunity and restraint. The averages are higher. Certain high-profile stories look constructive. Yet the experienced voice on the screen keeps insisting that conviction remains scarce. That tension creates the exact environment where mistakes become more common. Some investors chase the strength and get punished when the weather changes. Others sit in cash for too long and miss the eventual turn.
Finding the middle path requires honest assessment of both the tape and one’s own temperament. Not every investor needs to wait for perfect conviction. Some can successfully trade the shorter-term swings if they size positions appropriately and maintain strict risk controls. Others perform better by waiting for clearer signals and accepting that they will miss the earliest part of the move. Knowing which style fits your personality matters more than following any single commentator’s preference.
In my observation, the investors who navigate these periods most successfully tend to reduce urgency rather than increase it. They use the quieter moments to review positions, update watch lists, and clarify the conditions that would justify adding risk. When those conditions finally appear, they act with more confidence because the decision rests on a pre-defined framework rather than a reactive impulse.
Looking Ahead Without Forcing The Issue
Markets rarely stay weather-driven forever. At some point earnings momentum, economic data, or policy clarity can begin to outweigh daily yield fluctuations. Until that transition becomes more obvious, treating every advance with a degree of skepticism seems prudent. The cost of waiting a bit longer usually remains smaller than the cost of repeated false starts.
Cramer’s reluctance to jump into Tuesday’s strength does not amount to outright bearishness. It simply reflects a preference for higher-quality setups. He wants multiple reasons to buy rather than a single sunny day after a stretch of rain. That standard may feel demanding when the averages keep grinding higher, yet it has protected capital through many previous periods of choppy action.
For anyone managing money through the current environment, the message remains consistent. Respect the weather. Demand more conviction before increasing exposure. Use individual stock developments, whether secondary offerings or earnings resets, as opportunities to refine rather than abandon that disciplined approach. The market will eventually provide clearer signals. The investors who stay patient until then usually find themselves better positioned when those signals finally arrive.
Tuesday’s session offered a useful reminder that not every green day deserves celebration. Sometimes the most valuable insight comes from noticing what is still missing rather than focusing only on what is working. In that sense Cramer’s caution may prove more useful than the percentage gains themselves. Time will tell whether conviction returns soon or whether the weather continues to dominate for a while longer. Either way, the framework for deciding remains clearer after listening carefully to the morning discussion.
The real work for most investors now involves preparing rather than predicting. Review the holdings that would benefit most from stronger conviction. Identify the price levels that would make previously unattractive names more interesting. Clarify the macro conditions that would signal a meaningful shift away from weather-driven trading. Doing that preparation while the market remains choppy positions you to act with greater clarity when the character of the advance finally changes.
Until then, the safest stance looks a lot like the one Cramer described. Stay engaged. Stay informed. But resist the urge to force activity simply because the averages closed higher. Markets controlled by conviction reward preparation. Markets controlled by weather reward restraint. Recognizing which environment you are in remains one of the most valuable skills an investor can develop.