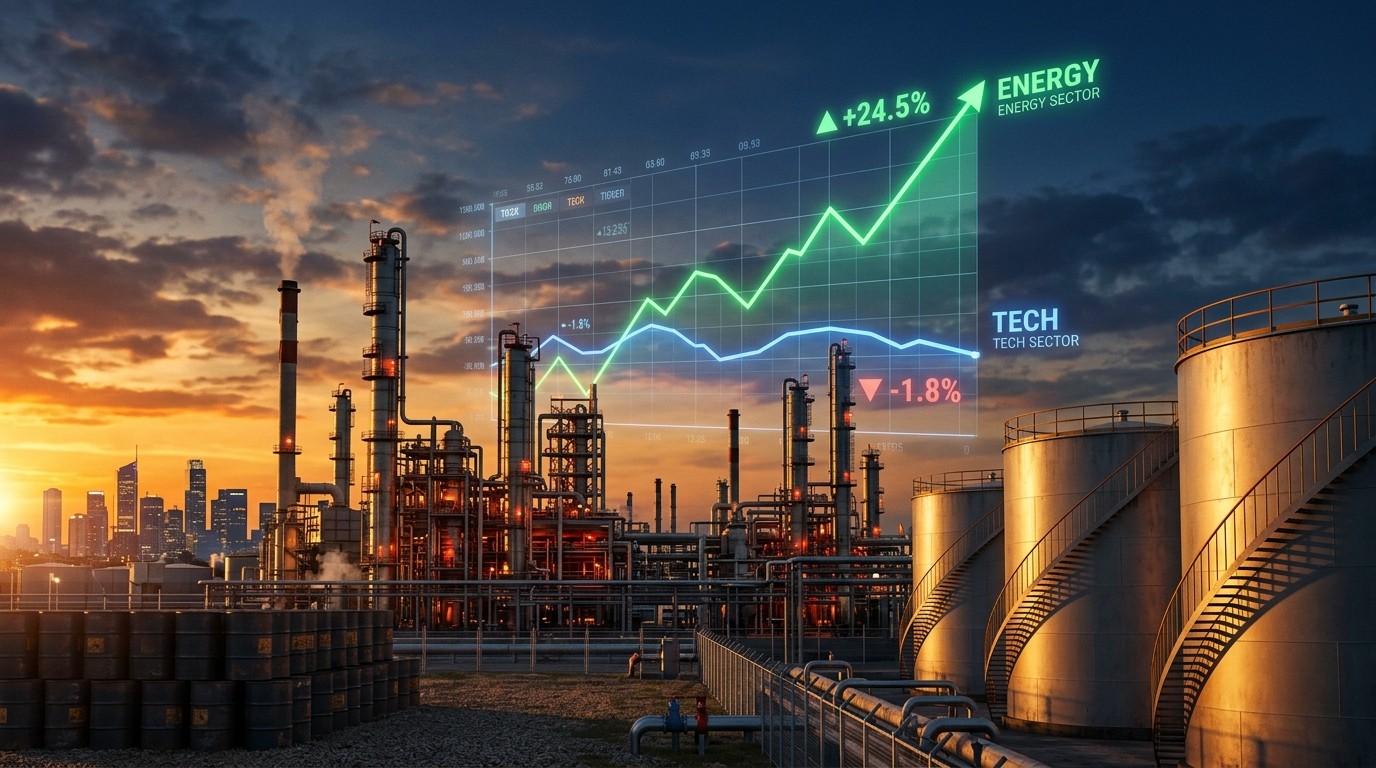

Something unexpected is happening in the markets right now, and if you have been watching only the usual tech names you might have missed it completely. Energy is not just participating in this bull run. It is leading it, and by a wide margin. I keep checking the numbers because they still surprise me every time. The Energy Select Sector SPDR Fund sits up more than fifty-three percent year to date while the broader market has managed only about fifteen. Technology remains strong at nearly thirty-seven percent, yet the recent price action tells a different story. Over the past couple of weeks tech has rolled over while energy has punched to fresh highs. That shift feels significant, and I want to walk through why it may have further to go.
Why Energy Has Quietly Taken Control Of The Market Leadership
Last week the conversation around a certain Brazilian energy name still lingered in my mind, but the charts forced a change of plans. Staying with the sector that actually carries the momentum makes more sense than chasing the narrative everyone expects. Energy has been the quiet outperformer for months, and the latest inflation data only added fuel. Headline CPI came in a tenth hotter than expected at three point seven percent. Bond yields moved higher almost immediately. That kind of backdrop usually pressures long-duration growth stocks. Energy, by contrast, tends to find support in that environment.
I have spent a fair amount of time separating the ten-year Treasury yield into its two core pieces: expected inflation and real yields. Only the real yield component is making new highs. Expected inflation sits well off its peaks. When I overlay crude oil on those three measures, the picture becomes clearer. Oil tracks real yields far more closely than the inflation expectations series. That relationship matters more than most people realize because it suggests the energy complex is responding to something deeper than temporary geopolitical noise or a single hot CPI print.
The Real Yield Signal Most Traders Are Overlooking
Real yields climbing while inflation expectations stay contained create an unusual setup. Higher real rates normally tighten financial conditions, yet energy stocks have powered higher anyway. In my view that points to genuine demand strength and supply constraints rather than pure inflation speculation. Crude itself has been coiling in a tight triangle for weeks. Falling resistance sits in the low one hundreds while rising support holds near ninety. The recent attack on a major Middle East facility added short-term noise, but the larger structure remains intact. Whichever way that triangle resolves will likely set the tone for the entire energy complex for the rest of the year.
I find myself watching that pattern more closely than usual. Breakouts from such compressed ranges often travel farther than expected, especially when the sector already holds leadership. The market is rarely this clear about where the real interest sits. Technology still attracts plenty of attention, of course, yet the relative strength numbers favor energy by a decisive margin. That gap has widened rather than narrowed in recent sessions.
Refining Margins Tell The Stronger Story
The cleanest expression of this strength, at least in my reading of the charts, lives in the refining space. Diesel crack spreads climbed from roughly twenty-five dollars a barrel at the start of the year to a peak above one hundred ten in September. They have cooled a bit toward the mid-nineties, yet the VanEck Oil Refiners ETF continues to hold near its highs. That resilience suggests the market still believes margins can remain elevated for longer than the typical cycle.
Marathon Petroleum stands out inside that group. The stock has climbed inside a well-defined channel since its 2020 low. At current levels around four hundred seventy-seven it trades far above its two-hundred-week moving average near one hundred eighty-one. Measured resistance points toward the six-hundred to six-hundred-fifty zone. That leaves meaningful room if the trend continues. I re-entered the name in the most recent portfolio rebalance and kept a significantly overweight energy allocation overall. The decision was not made lightly. These stocks look extended on almost every traditional measure, and that always raises the hair on the back of my neck.
The market is telling us that energy stocks are trading on more than just inflation expectations or geopolitical pressures. There is more to the story.
That extra layer is exactly what keeps me engaged. Active management means staying with the trade the market is focused on while still carrying a defined plan for the day it unwinds. Marathon reports third-quarter results on November 3 before the open. That event will provide the next major fundamental checkpoint. Until then the technical structure and the relative strength both favor staying long the refining theme.
How Crude Oil Structure Shapes The Entire Complex
Zoom out on the crude chart and the triangle becomes even more obvious. Price has been oscillating between that descending resistance line and the ascending support for long enough that a decisive break should carry follow-through. A move above the upper boundary would likely send the entire energy complex higher. A clean break below support would open the door to deeper profit-taking. Either outcome is clearer than the sideways grind we have seen lately.
I keep returning to the relationship with real yields because it feels underappreciated. When real yields rise and oil still finds buyers, it usually means physical markets are tight. Inventory data, refinery utilization, and export demand all feed into that picture. The diesel crack remaining elevated even after its recent pullback reinforces the idea that product markets stay strong. Refiners capture that margin, which is why names like Marathon continue to attract capital despite the stretched valuations.
Managing Risk When Everything Looks Extended
Let me be honest. Adding to energy positions at these levels makes me nervous. The charts look overbought on weekly and monthly time frames. Momentum oscillators sit near extremes. That is precisely when many investors start looking for reasons to exit. Yet the relative performance continues to favor the sector, and the fundamental drivers have not flipped. The better approach, at least in my experience, is to size carefully, keep a clear invalidation level, and let the market decide the next major move.
For Marathon the channel support provides a natural reference point. A sustained break below the rising trend line would signal the current leg higher has run its course. Until that happens the path of least resistance remains up. Portfolio construction also matters. Maintaining the overweight while pairing it with tighter risk controls on individual names helps sleep better at night. Energy leadership does not have to last forever, but fighting the current leadership rarely pays while it remains intact.
What The Bond Market Is Really Signaling
The CPI reaction offered a useful window into market psychology. Yields rose, growth stocks sold off, and energy held firm or advanced. That divergence is not random. Real yields moving higher while oil and energy equities ignore the pressure suggests underlying physical strength. Expected inflation has actually been declining from its peaks, yet energy has kept climbing. The market appears to be pricing a scenario in which real rates stay elevated without crushing demand for refined products.
I have found that watching the oil price relative to real yields often provides earlier clues than simply tracking the inflation number itself. When the two move together, the energy trade tends to have staying power. When they diverge sharply, caution is usually warranted. Right now they remain aligned enough to support the overweight stance. That does not mean every pullback should be bought with both hands. It does mean the broader thesis remains intact until the charts say otherwise.
Sector Rotation And The Shifting Leadership Landscape
Leadership changes rarely happen overnight. Technology carried the market for years, and many investors still default to those names when looking for growth. Energy stepping into the lead forces a mental adjustment. The numbers do not lie. Year-to-date performance already shows energy more than triple the broader market and well ahead of technology. The recent two-week stretch simply made the divergence harder to ignore. Shaded areas on relative strength charts highlight the shift in real time.
Perhaps the most interesting aspect is how few portfolios seem fully positioned for it. Many still carry heavy technology weights and only modest energy exposure. That imbalance can create additional buying pressure if the leadership persists. Capital has to come from somewhere, and relative performance eventually forces reallocation. I have watched this dynamic play out in previous cycles. Once the market settles on a new leader, the move can run longer than most expect.
- Energy Select Sector performance year to date exceeds fifty-three percent
- Technology remains strong yet has lost relative momentum in recent weeks
- Real yields continue making higher highs while inflation expectations lag
- Diesel crack spreads remain elevated after an extraordinary climb
- Refiners hold near highs even after modest margin cooling
Those points form the core of the current setup. None of them guarantee further upside, of course. Markets can reverse without warning. Still, the weight of evidence currently favors staying engaged with the energy theme rather than rotating back into the previous leaders simply because they feel more familiar.
Marathon Petroleum As The Cleanest Expression
Inside the refining group Marathon offers a relatively straightforward chart. The long-term channel from the 2020 low remains well defined. Price sits comfortably above major moving averages. The measured upside targets leave room if the broader energy complex continues higher. Earnings on November 3 will bring fresh numbers on margins, utilization, and guidance. That report could either reinforce the thesis or introduce new risks. Until then the technical picture supports the position.
I remain cautious about adding aggressively at these levels. The stock has already delivered substantial gains. Position sizing becomes more important the further price travels from value territory. Keeping the overall energy overweight while managing individual name risk feels like the practical middle ground. The market has rewarded that approach so far this year.
Looking Ahead At Key Levels And Catalysts
Several levels deserve attention in the coming sessions. On crude the upper boundary of the triangle sits in the low one hundreds. A daily close above that zone would open higher targets. Support near ninety remains the line in the sand on the downside. For Marathon the channel boundaries continue to provide useful reference points. A break of the rising trend line would argue for reducing exposure. As long as price respects the structure the bias stays constructive.
The diesel crack itself also warrants monitoring. A further cooling toward the seventies or lower would start to pressure refining margins and, by extension, the related equities. Holding above the mid-eighties keeps the recent strength intact. These are not precise predictions. They are simply the levels the market has already shown us. Respecting them helps avoid emotional decisions when volatility spikes.
Geopolitical events will continue to create short-term noise. The recent facility attack is a reminder that supply risks never fully disappear. Yet the larger technical and fundamental picture has absorbed those shocks without breaking the uptrend. That resilience itself carries information. Markets that shrug off negative headlines often have stronger underlying demand than the headlines suggest.
Putting The Pieces Together For Portfolio Decisions
Active managers face a constant tension between conviction and flexibility. The current energy leadership tests that balance. The data support an overweight allocation. The charts look extended. The solution is not to abandon the theme, nor is it to ignore the valuation risk. Maintaining the exposure while defining clear exit criteria strikes the more durable path. Earnings season will supply fresh information. The triangle on crude will eventually resolve. Real yields will continue to send signals.
In my experience the best trades often feel uncomfortable near the extremes. Comfort usually arrives after the move has already progressed. Energy has delivered one of those uncomfortable stretches this year. The performance gap versus technology and the broader market keeps widening rather than closing. Until that changes, staying with the leadership makes more sense than fighting it. The refining complex, and Marathon in particular, currently offer the cleanest way to express that view.
None of this constitutes a recommendation for any individual investor. Personal circumstances, risk tolerance, and time horizon always matter more than any single sector call. The charts and the relative strength simply highlight where the market is focusing its attention right now. Ignoring that focus has rarely proven profitable for long. Watching the key levels, respecting the risk, and remaining open to a change in leadership provides a practical framework for navigating the weeks ahead.
Energy has taken the lead. The question now is how long the market allows it to keep that position. The answer will arrive through price action, margin data, and the ongoing dialogue between real yields and crude. For the moment the message remains clear enough to keep the overweight in place and the risk controls tight.
The weeks ahead should bring clearer signals. Crude will break one way or the other. Refining margins will either stabilize or continue cooling. Marathon will report numbers that either confirm or challenge the current narrative. Through it all the relative performance of the energy sector against technology will remain the most important scoreboard. Leadership does not transfer permanently, yet while it lasts the market tends to reward those who stay aligned with it. That simple observation continues to guide the approach here.