
Have you ever stopped to wonder what happens when the materials that keep modern defense systems running suddenly become hard to get? I keep coming back to that question these days. The West is pouring record sums into rebuilding military capacity, yet a single chokepoint halfway around the world can still slow everything down. That reality is pushing European officials to look far beyond their usual suppliers, and one country in Southeast Asia is suddenly high on the list.
Why Europe Is Racing To Secure Alternative Mineral Sources
The urgency feels different this time. Bigger defense budgets alone cannot solve the problem when the raw ingredients for missiles, drones, sensors and armored vehicles remain concentrated in one place. Europe has watched export controls disrupt deliveries and force manufacturers to scramble. In my view, that experience left a lasting mark on policymakers. They now talk openly about the need to de-risk as fast as possible.
Internal assessments circulating among European officials have zeroed in on Vietnam. The country holds sizable deposits of rare earth elements and tungsten, two materials that matter a great deal for both civilian high-tech and military hardware. Until recently, European imports from Vietnam stayed limited mostly to tungsten and antimony. That narrow trade flow is starting to look insufficient given the scale of planned rearmament.
One official document put it bluntly: Europe cannot afford to ignore Vietnam’s potential as a supplier of critical raw materials, especially its abundant reserves of rare earths and tungsten. The language is unusually direct for diplomatic papers. It reflects a growing consensus that waiting for perfect conditions is no longer an option.
The Growing Pressure From Export Restrictions
Last year’s restrictions on certain critical materials sent ripples through European supply chains. Manufacturers of precision components and munitions felt the pinch almost immediately. Production schedules slipped. Costs rose. Engineers had to redesign parts or hunt for secondary sources that often proved more expensive and less reliable.
I’ve spoken with people close to the industry who describe a quiet scramble that still continues. Companies that once treated China as the default source of refined rare earths and tungsten compounds now maintain contingency plans that would have seemed excessive only a few years ago. The psychological shift is real. Once a supplier demonstrates it can turn the tap off, buyers start looking for other taps.
That dynamic explains why Brussels is assessing concrete cooperation possibilities with Vietnam. A spokesperson confirmed the European Commission is examining the potential for deeper collaboration in the critical raw materials sector. The wording remains cautious, as these things usually are, yet the direction of travel is clear.
Vietnam’s Mineral Profile And What It Offers
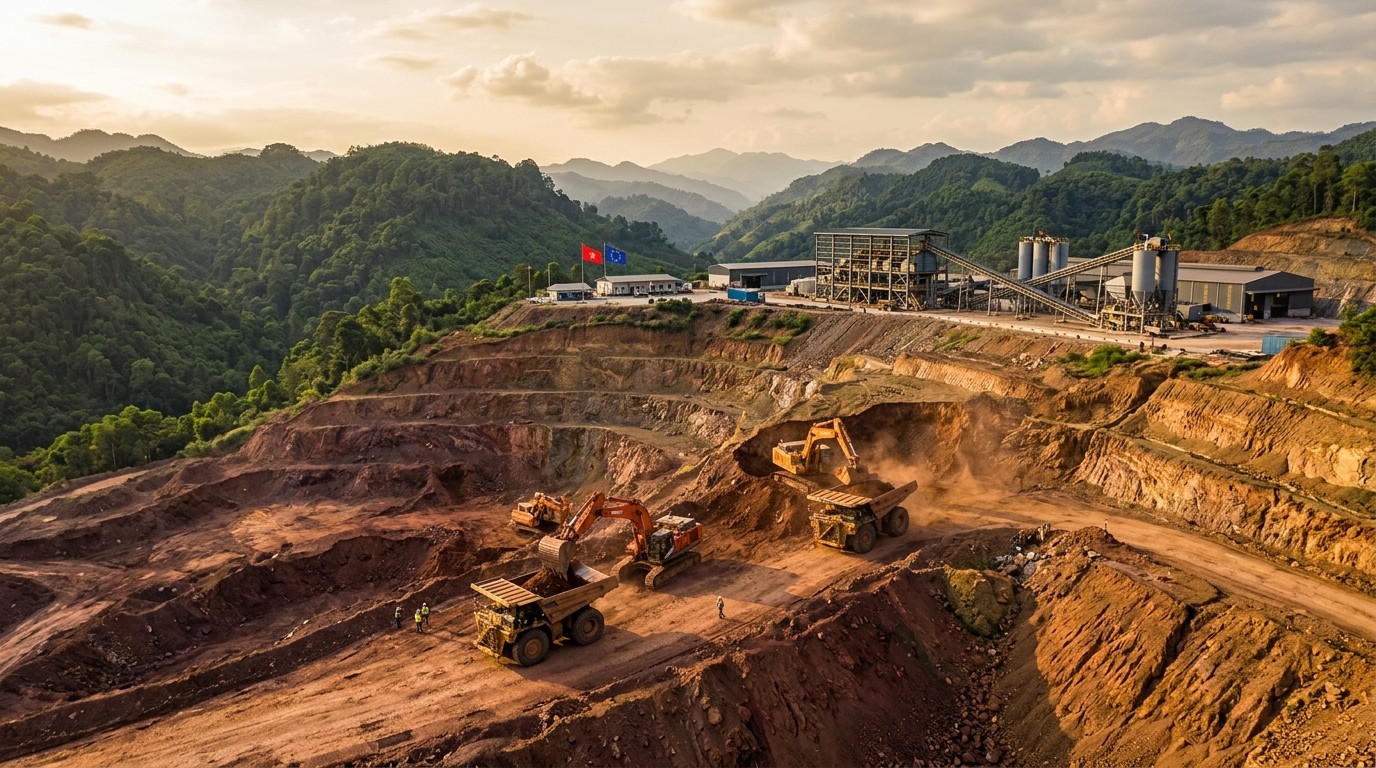
Vietnam sits on substantial deposits of several materials Europe needs. Rare earths appear in meaningful quantities, and tungsten reserves are particularly noteworthy. Tungsten’s high melting point and density make it valuable for armor-piercing applications and specialized alloys. Rare earths play essential roles in permanent magnets, sensors and guidance systems.
The country already ships some tungsten and antimony to European buyers. Expanding that trade into a broader critical-materials partnership would require investment in extraction, processing and environmental standards. Vietnam has signaled interest in developing its mining sector further, though progress has been uneven over the years.
From an investor’s standpoint, the key question is whether projects can move from exploration into consistent commercial production that meets Western quality and traceability requirements. Conflict-free and environmentally responsible sourcing has become non-negotiable for many defense contractors and their government customers. Vietnam’s ability to satisfy those conditions will determine how quickly volumes can grow.
Rearmament Timelines And Material Demand
Analysts who follow European aerospace and defense expect a multi-year rearmament cycle to gather real momentum next year and continue through the end of the decade. That timeline matters. Mines and processing plants cannot be built overnight. If Europe wants alternative supplies in place before demand peaks, the groundwork has to start now.
The list of equipment that relies on these materials is long: missiles, ammunition, armored vehicles, one-way attack drones, interceptors and advanced sensors. Each new production line adds incremental pressure on already tight markets. When one major supplier restricts exports, the secondary markets tighten further and prices respond accordingly.
In my experience watching commodity cycles, the companies that already produce and deliver materials to Western markets tend to benefit first. New projects face permitting delays, financing hurdles and technical challenges. Existing producers with proven offtake agreements sit in a stronger position during the early phase of any supply diversification push.
Market Reaction And The Rare Earth Trade
The VanEck Rare Earth and Strategic Metals ETF, which tracks companies involved in production, refining and recycling of critical minerals, offers a useful window into sentiment. After climbing through much of 2025 and early 2026 on the back of export-control headlines, the fund peaked in May and then lost nearly half its value by early autumn. That kind of retracement is familiar to anyone who has followed commodity-linked equities.
Price swings of that magnitude create both risk and opportunity. When the sector eventually stabilizes, attention is likely to shift toward miners and processors that can reliably deliver conflict-free material into Western supply chains. Not every company in the space will meet that standard. Differentiation on the basis of offtake quality and customer relationships could become more pronounced.
Perhaps the most interesting aspect is how these materials sit at the intersection of several megatrends. Defense is the most immediate driver right now, yet rare earths and related metals also matter for AI data centers, electrification and broader reindustrialization efforts. Demand is not coming from a single source.
Resource Nationalism And Global Uncertainty
Resource nationalism is intensifying across critical minerals, metals and energy. Governments are more willing to use export controls, local-content rules and strategic stockpiles as policy tools. That trend adds a layer of uncertainty as the world heads into what could be a volatile period for commodity markets.
For Europe, the calculation is straightforward even if the execution is complex. Continued heavy reliance on a single supplier creates strategic vulnerability. Diversifying sources reduces that risk, though it does not eliminate price volatility or technical challenges. Vietnam represents one potential piece of a larger puzzle that also includes partners in Australia, Africa, the Americas and domestic European projects still in early stages.
I’ve found that successful diversification strategies usually combine short-term commercial contracts with longer-term investment in mining and processing capacity. Pure trading relationships leave buyers exposed to the next policy shift. Equity stakes, joint ventures and offtake agreements tied to specific projects create stronger alignment.
Practical Challenges On The Ground
Moving from diplomatic statements to actual tonnage is never simple. Vietnam’s mining sector has faced infrastructure constraints, environmental scrutiny and the need for modern processing technology. Rare earth separation and refining remain particularly capital-intensive and technically demanding. Building capacity that meets European environmental and labor standards will take time and money.
Financing is another hurdle. Western development banks and commercial lenders have grown more cautious about mining projects in emerging markets, especially those involving sensitive materials. Blended finance structures that combine public guarantees with private capital may become necessary. The European Commission’s ongoing assessment will presumably explore these practical questions.
Traceability requirements add further complexity. Defense contractors and government buyers increasingly demand detailed documentation of origin and processing steps. Establishing audited supply chains from Vietnamese mines through intermediate processing to final European users will require new systems and third-party verification.
- Expanding existing tungsten trade into broader rare-earth volumes
- Attracting processing technology and environmental expertise
- Securing long-term offtake agreements with European buyers
- Meeting strict conflict-free and sustainability criteria
- Navigating permitting and community engagement processes
Each of those steps carries its own timeline and risk profile. Progress on one does not automatically translate into progress on the others.
Implications For Investors And Markets
For market participants, the story is less about any single country and more about a structural shift in how Western governments and companies approach critical-material security. Companies that already produce and ship material into Western markets enjoy a first-mover advantage. Those still raising capital for greenfield projects face a longer road.
Equity valuations in the rare-earth and strategic-metals space have already shown how sensitive they are to policy headlines. The sharp rise followed by a substantial pullback in the tracked ETF illustrates the point. Once the current consolidation phase ends, the market will likely differentiate more carefully between companies with proven delivery records and those still in the planning stage.
I suspect the next phase will reward operators who can demonstrate reliable, auditable supply into Europe and North America. Price alone is no longer the decisive factor. Security of supply and alignment with Western policy priorities carry growing weight in purchasing decisions.
Broader Economic And Strategic Context
The push for alternative sources sits inside a larger conversation about economic resilience. Modern economies depend on a relatively small set of materials for everything from electric vehicles to advanced electronics to defense systems. Concentration of production and refining capacity creates systemic risk. Diversification is one response. Stockpiling is another. Developing recycling capacity is a third.
Europe has already taken steps on several of these fronts. The current focus on Vietnam fits into that wider effort rather than standing alone. Success will depend on coordination between diplomatic outreach, commercial investment and regulatory frameworks that encourage responsible mining without creating endless delays.
One subtle point worth noting is the interaction between defense demand and civilian demand. AI infrastructure build-outs and electrification programs compete for some of the same materials. When both sectors expand simultaneously, the pressure on available supply intensifies. Alternative sources become even more valuable under those conditions.
Looking Ahead At Possible Paths
What happens next depends on several variables that remain hard to predict with precision. The pace of European rearmament spending, the evolution of Chinese export policy, Vietnam’s ability to scale production responsibly, and the availability of financing all matter. A favorable combination of those factors could accelerate the emergence of a more diversified supply map. A less favorable combination would leave Europe exposed for longer.
In the near term, existing producers that already serve Western markets appear best positioned. Their ability to expand output or redirect volumes can provide bridge capacity while longer-term projects mature. That dynamic tends to favor established names over pure exploration stories, at least until new mines reach commercial production.
I’ve found that commodity markets rarely move in straight lines. Periods of intense focus on security of supply often give way to complacency once immediate pressures ease. Maintaining momentum on diversification after the current urgency fades will be a political and commercial test. The countries and companies that treat the issue as structural rather than cyclical are more likely to build lasting positions.
Practical Considerations For Supply Chain Planners
Companies responsible for securing materials face a set of practical choices. Short-term contracts with new suppliers can reduce immediate exposure. Longer-term agreements and equity participation create deeper ties but require greater capital commitment and risk tolerance. Many organizations will likely pursue a mix of both approaches.
Quality and consistency remain non-negotiable. Defense applications in particular demand tight specifications. A new source that cannot meet those standards reliably will struggle to win lasting business, regardless of geopolitical appeal. Technical due diligence therefore sits alongside political and commercial analysis.
Environmental and social performance also matters more than it once did. European buyers operate under public and regulatory pressure to demonstrate responsible sourcing. Projects that lag on these dimensions face higher hurdles to acceptance even if the geology is attractive.
Considering Europe’s need to rearm and de-risk as fast as possible, alternative suppliers with proven reserves cannot be overlooked.
That sentiment, expressed in internal assessments, captures the mood. The challenge now is translating recognition into concrete volumes of material that reach European factories on schedule and within specification.
The Role Of Existing Producers Versus New Entrants
A recurring theme in these discussions is the relative advantage of companies already producing and delivering. New projects face years of development. Even when financing and permits fall into place, ramp-up periods can be lengthy and full of unexpected technical issues. Producers with operating mines and established logistics channels can respond more quickly to incremental demand.
That does not mean new capacity is irrelevant. Long-term security of supply ultimately requires additional production. The sequencing matters, however. Bridge supply from existing sources buys time for new projects to mature. Markets that understand this sequencing tend to price the two categories differently.
Recycling and secondary recovery also form part of the picture. Recovering rare earths and tungsten from end-of-life products or industrial scrap can ease pressure on primary supply. Europe has been investing in these capabilities, though volumes remain modest relative to primary demand. Scaling recycling will take continued policy support and technological progress.
Balancing Speed And Standards
One tension that keeps surfacing is the need for speed versus the insistence on high environmental and governance standards. Europe wants alternative supplies quickly, yet it also wants those supplies to meet criteria that many existing producers outside traditional Western jurisdictions find demanding. Resolving that tension will require pragmatic compromises and capacity-building support.
Vietnam’s own policy choices will influence the outcome. Clear regulatory frameworks, transparent permitting processes and credible enforcement of environmental rules would make the country more attractive to European partners. Inconsistent application of rules or sudden policy shifts would have the opposite effect.
Diplomatic engagement alone cannot substitute for commercial viability. Projects must generate acceptable returns for the capital invested. That means realistic cost structures, reliable logistics and offtake terms that work for both sides. Idealism about diversification will only carry the process so far.
What Success Could Look Like
A successful diversification effort would not eliminate Chinese supply entirely. It would reduce concentration risk to a level that feels manageable. Multiple sources of rare earths and tungsten, each capable of meeting Western standards, would give European manufacturers greater flexibility and bargaining power. Price spikes triggered by policy decisions in any single country would become less severe.
For Vietnam, success would mean higher-value mineral exports, technology transfer and deeper integration into global high-tech and defense supply chains. Those benefits are not automatic. They require sustained investment and policy consistency over years rather than months.
Investors watching the space should focus less on daily price moves and more on the gradual build-out of alternative capacity. Contracts signed, processing plants commissioned and first commercial shipments are the milestones that matter. Rhetoric is easy. Deliverable tonnage is harder and more revealing.
Final Thoughts On A Structural Shift
The conversation about critical materials has moved from specialist circles into mainstream strategic planning. That shift is unlikely to reverse. Defense requirements, technological competition and the simple arithmetic of concentrated supply have made resource security a permanent item on the agenda.
Europe’s interest in Vietnam forms one chapter in a longer story. Other potential partners exist, and domestic European projects continue to advance, albeit slowly. The combination of these efforts will determine how resilient Western supply chains become over the next decade.
In the end, the countries and companies that treat security of supply as a core competency rather than a temporary concern will shape the next phase of the critical-materials market. Vietnam has the geological endowment. Whether it can convert that endowment into reliable, high-standard supply for European buyers remains an open and consequential question. The answer will influence not only defense production schedules but also the broader trajectory of industrial policy in the years ahead.
Watching this process unfold has reinforced a simple observation. When strategic necessity collides with geological reality, capital and diplomacy tend to follow. The current moment feels like one of those collisions. How efficiently the resulting investments are deployed will decide whether Europe truly manages to de-risk its most sensitive material flows or merely redistributes the risk in more complicated ways.
The coming years will test the seriousness of the diversification agenda. Announcements and assessments are useful starting points. Consistent delivery of material that meets the required specifications will be the real measure of progress. For now, the direction is set. The hard work of building alternative supply chains has only just begun.