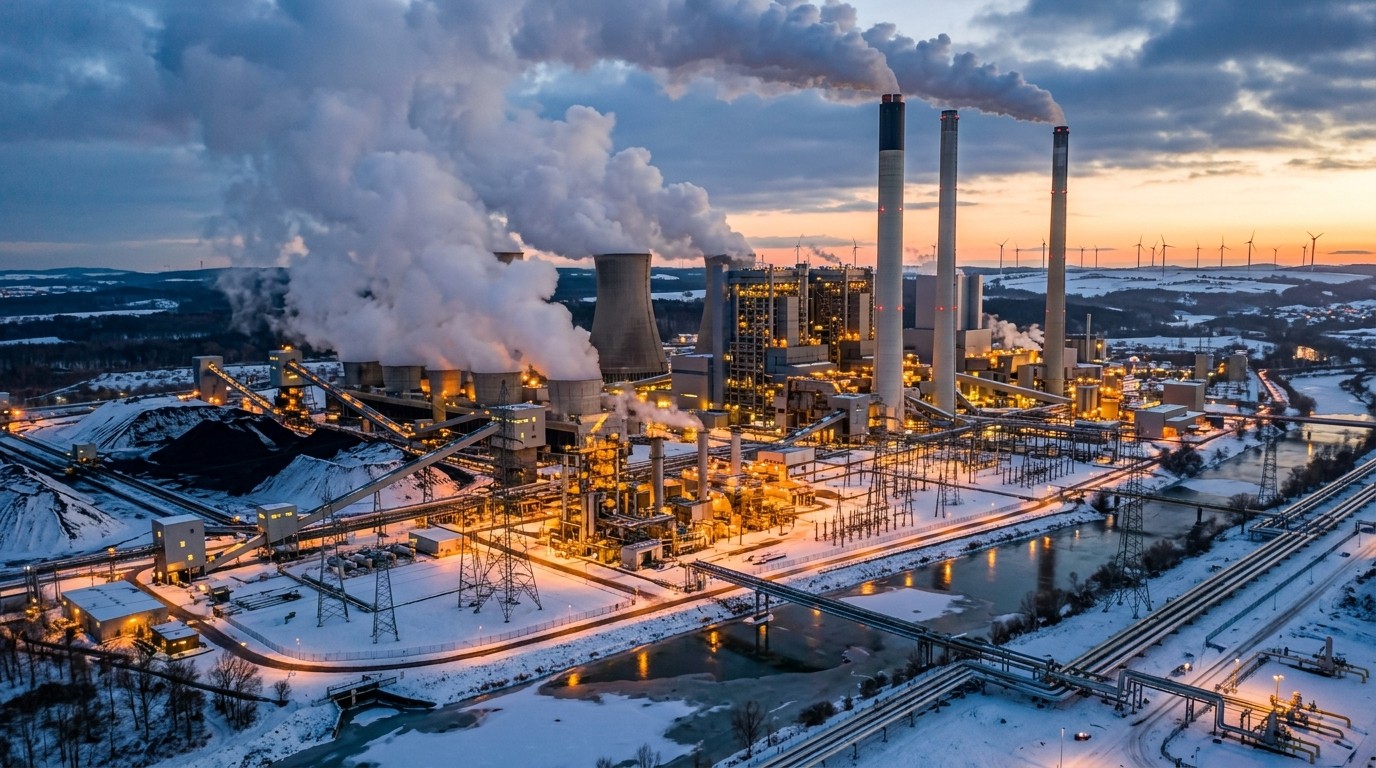

Have you ever watched energy markets flip on a dime and wondered if the clean transition talk was just a temporary pause button? That is exactly what seems to be happening across parts of Europe right now. With global LNG supplies squeezed tighter than expected and gas prices climbing back toward crisis levels, the handful of coal plants still standing are suddenly looking like the smart money play again. I have been following these shifts for a while, and the latest numbers on profitability spreads make it hard to ignore. Winter is coming, grids need stability, and the remaining coal capacity in places like Germany and Poland is stepping back into the spotlight.
Why Coal Is Suddenly Making Money Again
The core story is straightforward yet surprising. Gas-fired generation has become expensive enough that older coal units, once written off as climate liabilities, now deliver positive margins. One key measure for lignite-based power in Germany has climbed as high as 72 dollars per megawatt-hour this month. Last year at the same point, that figure sat at zero. That is not a small move. It signals real economic pressure returning to the system.
Analysts tracking the situation note that these healthier spreads should hold through March. That timing matters. It covers the heart of the heating season when electricity demand rises and renewable output can turn unreliable. In my view, this is less about a full-scale coal renaissance and more about pure pragmatism. When gas costs spike and LNG cargoes struggle to move freely, operators look at whatever capacity remains available and put it to work.
The LNG Bottleneck and Its Ripple Effects
Global LNG markets are tight. Supply routes face disruptions, and the flow out of key chokepoints has slowed. Europe feels this acutely because it leaned heavily on seaborne gas after earlier pipeline reductions. Higher import costs translate directly into higher generation costs for gas plants. Meanwhile, coal units that were kept as backups or scheduled for gradual retirement find themselves competitive once more.
Demand destruction has already trimmed some gas use, yet the need for firm, dispatchable power has not disappeared. Grids still require plants that can ramp up when the wind drops or the sun sets. Coal fills that role in several markets. The result is a temporary boost in coal burn even as the longer-term trend points downward.
Higher gas prices have reduced the expected decline in countries where gas generation and spare coal capacity remains available.
That assessment captures the moment well. Structural decline continues, but the pace slows when relative prices favor coal. Total European coal demand is now projected around 276 million tons for the year, down from the previous year’s 292 million yet higher than earlier forecasts. The adjustment reflects exactly this gas-price effect in Germany and Poland, the two countries holding most of the remaining operational or standby coal fleet.
Germany and Poland at the Center
Germany closed significant coal capacity in recent years to meet climate goals. The remaining plants were meant to serve as a bridge or emergency reserve. Poland has always relied more heavily on coal and has moved more slowly on phase-outs. Together they host the bulk of Europe’s leftover coal power assets. When gas becomes costly, those assets start earning again.
I find the German numbers particularly striking. Lignite, often seen as the dirtier end of the coal spectrum, is posting solid positive margins. Hard coal units benefit too. Operators who kept plants available rather than dismantling them early now look prudent. The spreads are not guaranteed forever, of course. A mild winter or a sudden influx of LNG could reverse the picture quickly. Still, for the months ahead the economics favor running the coal fleet harder.
Weather adds another layer of uncertainty. Cold spells can push demand higher and force greater use of every available generator. Recent geopolitical tensions that rattled oil and gas markets globally have already fed into price spikes. Any further weather extremes would amplify the effect on coal utilization beyond what planners expected earlier.
Balancing Climate Ambitions With Grid Reality
Here is where the conversation gets complicated. European countries have spent years committing to lower emissions and retiring coal. Those targets remain in place. Yet the physical need for reliable power does not vanish simply because policy prefers cleaner sources. When gas prices surge, the system leans on what is still connected to the grid.
This creates a tension that policy makers and operators navigate carefully. Keeping some coal capacity online as insurance has proven useful during tight periods. At the same time, every extra ton burned slows the emissions trajectory. The current profitability window does not erase the structural decline; it merely softens the slope for one season.
In my experience watching these markets, pure ideology rarely wins when the lights risk going out. Grid operators prioritize stability first. Investors and plant owners respond to price signals. The combination produces exactly the kind of short-term rebound we are seeing now.
How Profitability Is Measured
Power plant economics often hinge on the spark spread or dark spread concept. For gas it is the spark spread; for coal it is the dark spread. These calculations subtract the cost of fuel and carbon allowances from the electricity selling price. When the result turns positive and stays positive, operators have a clear incentive to generate.
Right now the dark spreads for European coal look healthy. The jump from zero last year to tens of dollars or euros per megawatt-hour this year is meaningful. It does not mean every plant runs flat out. Maintenance schedules, environmental limits, and local regulations still apply. But the financial barrier that kept some units offline has dropped.
- Higher wholesale power prices driven by gas costs
- Stable or only moderately rising coal fuel costs relative to gas
- Existing carbon pricing that coal plants already factor into their margins
- Available spare capacity that can respond quickly
Those four elements line up in favor of coal right now. The carbon price remains a headwind, yet it has not been high enough to wipe out the fuel-cost advantage that coal currently holds over gas.
Looking Ahead Through the Winter
Forecasts suggest the elevated spreads could persist into early spring. That gives plant owners a clear window to maximize output while conditions remain favorable. After that, much depends on weather, LNG arrival rates, and any further shifts in global supply.
Europe has already seen demand destruction in some industrial sectors as high energy costs forced cutbacks. Households have also adjusted habits. Even so, the residual need for baseload and flexible generation keeps conventional plants relevant. Renewables continue to grow, yet they still require backup on calm, cloudy days.
Perhaps the most interesting aspect is how quickly market conditions can reopen the door for fuels that policy had hoped to close. I have seen similar patterns before. High prices bring older capacity back into the money. Low prices accelerate retirements. The cycle is not new, but the scale of the recent gas tightness has made the swing more visible.
Broader Implications for Energy Security
Energy security has returned as a live topic. Diversification of supply, storage levels, and the ability to call on domestic resources all matter more when imports face constraints. Coal plants that remain operational provide a domestic buffer. They burn fuel that is often sourced closer to home or from more varied global suppliers than LNG.
This does not reverse the long-term move away from coal. Most European governments still plan further closures. Yet the current episode underscores a practical lesson: transition timelines need flexibility for periods of stress. Rigid schedules can collide with physical reality when markets tighten.
Operators who maintained plants in a state of readiness rather than full mothballing now benefit. Those who moved faster toward permanent shutdown have fewer options. The difference shows up in both grid reliability and company cash flow during high-price months.
What the Numbers Tell Us About Demand
Annual coal demand across Europe is still falling, just more slowly than once projected. The revised figure of roughly 276 million tons reflects the moderating influence of expensive gas. Without that price spike, the drop would have been steeper. Poland and Germany account for a large share of the adjustment.
Other countries with little remaining coal capacity feel the gas price pressure differently. They lean harder on imports, nuclear where available, or demand response. The countries that kept some coal options open experience a partial offset. That contrast is worth watching as the season progresses.
| Factor | Impact on Coal Use | Current Status |
| Gas prices | Strong upward | Elevated versus recent years |
| LNG supply flows | Constraining | Tightened by global conditions |
| Remaining capacity | Enabling | Concentrated in key markets |
| Weather risk | Potential amplifier | Winter season ahead |
| Long-term policy | Downward pressure | Phase-out plans intact |
The table above summarizes the push and pull forces. Short-term economics favor higher coal generation. Longer-term policy still points the other way. Markets are living in the middle of that tension right now.
Investor and Operator Perspectives
From an investor standpoint, the sudden profitability offers a reminder that energy assets can regain value quickly when fundamentals shift. Plants previously valued mainly for their exit timeline or land potential now generate operating cash. That changes short-term calculations even if the ultimate retirement date stays the same.
Operators face practical questions. How hard should they run the units while margins are good? What maintenance can be deferred or accelerated? How do they manage emissions allowances and local air-quality limits while maximizing output? These are the day-to-day decisions that turn a positive dark spread into actual generation.
I have noticed that some market participants treat these periods as temporary gifts rather than structural changes. They capture the upside without assuming it will last. That mindset seems healthy. Energy markets have delivered enough surprises in recent years that humility about the next six months is warranted.
The Role of Conventional Generation in Modern Grids
Modern power systems increasingly rely on variable renewables. That growth is real and continues. Yet the physics of electricity still demand that supply match demand in real time. When wind and solar output drop, something else must fill the gap. Gas has been the preferred flexible fuel in many markets. When gas itself becomes scarce or expensive, coal steps in where it is still available.
This dynamic is not unique to Europe. Other regions have seen similar temporary rebounds in coal use during periods of gas tightness or extreme weather. The difference in Europe is the strong policy overlay that aims to phase coal out entirely. The current episode tests how that policy interacts with short-term market signals.
Grid operators value the inertia and voltage support that large thermal plants provide. Those technical attributes are harder to replace quickly with batteries or demand-side tools alone. Keeping a subset of coal plants available preserves options. Running them when economics improve is a logical next step.
Potential Risks and Reversals
Nothing in energy markets stays fixed for long. A surge in LNG arrivals, milder temperatures, or a drop in power demand could shrink the dark spreads again. Carbon prices could rise further and erode coal margins. Policy interventions could limit running hours even when plants are profitable.
There is also the risk of over-reliance. If operators and governments treat the current profitability as a reason to slow broader diversification, the system could face deeper stress later. The better approach, in my opinion, is to use the cash flow from this period to support flexibility investments elsewhere while the coal units still operate under temporary favorable conditions.
Geopolitical developments remain an open variable. Any further disruption to global energy flows could extend the window of coal competitiveness. Conversely, a resolution of current supply constraints would likely restore the previous downward trajectory more quickly.
Lessons From Previous Price Spikes
Europe has lived through high gas prices before. The earlier crisis taught hard lessons about storage, demand response, and the value of diverse generation. Many of those lessons still apply. Storage levels matter. Industrial flexibility helps. And having some firm capacity in reserve reduces the pain when imports tighten.
What feels different this time is the stage of the energy transition. More renewables are on the system. More coal has already left. The remaining coal fleet is smaller, yet it still carries meaningful weight in the two largest remaining markets. That concentration makes the profitability story more visible.
Looking back, the plants that survived earlier waves of closures now serve as a real-world stress test of how far the system can lean on cleaner sources alone. The answer so far is that it can lean quite far under normal conditions, but extreme price or weather events still pull conventional plants back into active service.
What Comes After the Winter Window
Once March passes and heating demand eases, the pressure on coal may ease too. Spreads could compress. Operators would then return to planning around longer-term phase-out schedules. Some plants might move into deeper reserve. Others could face accelerated retirement if the economics no longer justify keeping them available.
The structural decline in European coal demand is expected to resume. The current year simply shows a shallower drop than previously modeled. That adjustment is already baked into updated forecasts. Future years will depend on how quickly gas markets rebalance and how fast alternative capacity comes online.
In the meantime, the profitability of the remaining fleet offers a clear market signal. When the alternative fuel becomes expensive enough, older assets regain relevance. The signal is temporary, but it is real and measurable in the spreads that plant owners watch every day.
Putting the Episode in Perspective
Energy transitions are rarely linear. They advance in fits and starts, interrupted by price spikes, weather extremes, and geopolitical shocks. The present episode with European coal is one more reminder of that pattern. Climate targets and market reality both matter. Ignoring either creates risk.
For now, the numbers show that Europe’s last-standing coal plants have found a profitable niche for the months ahead. Gas remains costly. LNG flows remain constrained. Winter demand is approaching. Under those conditions, coal generation that can still run does run, and it earns a return while doing so.
Whether this becomes a one-season story or a longer pause in the decline depends on factors still unfolding. I will be watching the dark spreads, the weather forecasts, and the LNG arrival data closely. Those indicators will tell us how long the current profitability window stays open.
The broader takeaway is simple. Power systems need both ambition and flexibility. Ambition drives the long-term shift toward cleaner sources. Flexibility keeps the lights on when markets tighten. Right now, Europe’s remaining coal plants are providing that flexibility and getting paid for it. That combination may not last forever, but it is the reality of this particular winter season.
As the weeks progress, the interaction between high gas prices and available coal capacity will continue to shape generation mixes in key markets. Grid stability remains the priority. Economic signals continue to guide day-to-day decisions. And the tension between near-term needs and longer-term goals stays firmly in view. That is the landscape operators, investors, and policy makers are navigating today.
One final observation. Markets have a way of testing assumptions. The assumption that coal’s role in Europe was already finished has met a temporary counter-example in the form of positive dark spreads and rising utilization. The counter-example is limited in scope and likely limited in duration. Yet it is large enough to revise demand forecasts and keep a set of plants online that might otherwise have stayed quiet. In energy, limited and temporary still matter a great deal when the alternative is tighter supply and higher prices for consumers and industry.
The coming months will show how this chapter resolves. For the moment, the story is clear: global gas constraints have handed Europe’s remaining coal plants a profitable stretch at a time when the system needs every reliable megawatt it can find. That is the situation on the ground, and it is worth understanding in full as winter approaches.